Liquidity drives project finance appetite
27 October 2023

This report on project finance and PPP also includes: PPP activity rebounds in 2023
Activity in the Gulf region has triggered a boom in the project finance market, with Saudi Arabia leading the way on the back of schemes linked to its Vision 2030 strategy.
Deals are fanning out from power and water and infrastructure schemes into unexplored territory: hydrogen projects and ever-larger solar power plants have opened up opportunities for international and regional banks that are awash with liquidity and looking for long-term means to deploy it.
Deal advisers attest to the vibrancy of Saudi Arabia, the largest regional projects market with $1.2tn-worth of known work in the pipeline. The kingdom has seen the largest project financing this year, a facility worth at least $6bn arranged for the Neom green hydrogen project.
“Saudi Arabia is a market that really is firing on all cylinders,” says Rob Harker, a partner at law firm DLA Piper, which advised Neom Green Hydrogen Company in connection with its green hydrogen and ammonia project in Saudi Arabia.
“That demand is not limited to utility sector projects. In addition to the very large solar and wind projects – including a Saudi solar deal that is 1.1GW – we are also seeing a large volume of social infrastructure projects being procured across the GCC, including in education, healthcare, social accommodation and transport,” he adds.
“Bank debt – both regional and international – is still the principal source of financing for these projects. However, robustly structured projects should also be attractive, particularly on a refinancing, to a capital markets issuance.”
Robust liquidity support
There is increased liquidity in the regional banking market, notes John Dewar, partner in international law firm Milbank’s global project, energy and infrastructure practice, which advised the export credit agencies (ECAs) and commercial banks in connection with Project Lightning, Abu Dhabi National Oil Company’s offshore power transmission project.
“With the bullish medium-term oil price outlook, there is significant liquidity in the Saudi and UAE bank markets, with these banks looking to on-lend their petrodollar deposits on a longer-term basis.”
This still poses some challenges. Analysts note that despite the bountiful credit availability, things can change.
“There is still a lot of liquidity in the system in the GCC, but some have voiced concerns that liquidity in the banking market could dry up in the future if they have to compete with projects that are much larger in scale,” says Christiane Kuti, a director at Fitch Ratings.
“Overall liquidity in the market could get tight at some point, although we are not there at the moment.”
Even then, notes Kuti, a lower oil price could add impetus to the need to develop frameworks to make projects more bankable, and provide an opportunity for the capital market to play a bigger role.
Most of the larger deals are witnessing a heterodox mix of local and international banks participating. For example, a consortium of five local and international banks has agreed to provide $545m of financing for the Rabigh 4 independent water producer project in Saudi Arabia, with Standard Chartered Bank lining up alongside Bank of China and the local trio of Saudi National Bank, Riyad Bank and Saudi Investment Bank.
The Chinese bank presence is a pointer. “We have seen Chinese banks participating in project finance deals, and that is set to continue as they are not as constrained as some of the regional banks in terms of the tenor on which they can lend. Their ability to lend on a longer-term tenor is sometimes attractive for sponsors and developers,” a source tells MEED.
The flipside of this is that Chinese lenders are less knowledgeable about the market.
Global uncertainties
Despite the robust oil price climate, project financings across the Middle East and North Africa (Mena) region have had to cope with a choppy global interest rate environment, with inflationary pressures also impinging.
Higher interest rates have militated against the use of capital market instruments in some regional deals. For Abu Dhabi’s subsea transmission system deal, which reached financial close earlier this year, higher interest rates were responsible for adding $200m to the $3.8bn deal.
This has implications for other projects that are seeking refinancing on the capital market. In Saudi Arabia, BlackRock-led investors in Saudi Aramco’s gas pipeline network attempted early in 2023 to raise $4.5bn from a sale of bonds to refinance a multibillion-dollar loan. The 10-year mature sukuk (Islamic bond) tranche spread placed it about 120 basis points above where Aramco bonds maturing in October 2030 were trading, according to Reuters’ calculations.
Another consortium led by US-based energy infrastructure investment firm EIG Global Energy Partners had also looked to the bond markets to refinance.
“The EIG and BlackRock-led consortiums investing in Saudi Aramco’s oil and gas pipelines infrastructure have been looking to refinance more than $20bn of acquisition debt,” says Dewar.
“Both have been active in the bond market, but the interest rate environment has moved against bonds, so there has been an increasing focus by borrowers on accessing other longer-term liquidity sources, particularly from the highly liquid regional banks.”
Capital market instruments
For the moment, capital market instruments are largely confined to refinancing rather than greenfield projects. However, once some of these projects are financed, it could encourage others to lend on that basis.
“Once a project has been up and running, and it has got consistent revenue from the offtaker of the electricity or the water, and they are paying an index-linked revenue stream that is 100 per cent take or pay and insulated from the erosion of any inflationary pressures, that is very attractive for bondholders, pension funds and other institutions that want stable revenues,” says one industry insider.
Beyond the Gulf, Egypt has managed to attract project finance for its renewable energy schemes, with significant ECA support. In March 2023, a $690m non-recourse financing was arranged for the 500MW Gulf of Suez Wind 2 project in Egypt.
The renewable energy push has continued after Cairo’s hosting of the 2022 Conference of the Parties of the UN Framework Convention on Climate Change (Cop27). The drive has included the Amunet wind and Abydos solar projects closed by Amea Power, as well as the Gulf of Suez Wind 2 project sponsored by Engie, TTC-Eurus and Orascom.
“They are both important deals in a global context because they mark the first occasions on which the Japanese ECAs have co-financed with the International Finance Corporation and the European Bank for Reconstruction & Development, respectively, opening up important new financing opportunities in emerging markets,” says Dewar.
Support from ECAs is particularly valued in Egypt, given the economic challenges the country is facing.
A planned polypropylene complex due to be developed in Egypt’s Suez Canal Economic Zone has been put on hold, with the $1.7bn project developed by Red Sea Refining & Petrochemical Company having been affected by the depreciation of the Egyptian pound.
More regional financing
Another emerging theme will be for the larger Mena banks to play a bigger role in regional project financings.
The likes of First Abu Dhabi Bank have been active across GCC borders, including in Saudi Arabia. Given their healthy liquidity profiles, the biggest banks in the GCC are better positioned for longer-tenor project finance deals than ever before.
Not that it will be plain sailing. Structural impediments will still have to be overcome.
For example, most Saudi banks still need to get consent from the Saudi Arabian Monetary Agency (Sama) to participate in dollar loans. “That can constrain their ability to operate outside the kingdom,” says Dewar.
“There is a regulatory preference for them to make Saudi riyal loans rather than dollars. But because of the increase in dollar liquidity, there is much more availability in the Saudi market than there was a year ago.”
Project finance will remain a critical part of the funding mix in the Mena region. As Fitch Ratings notes, the significant growth needed to achieve the GCC’s investment requirements cannot be attained using traditional financing channels, such as on-balance-sheet funding by governments. Instead, there is a need to broaden the investor base, including through project financing.
The likelihood of a more benign global interest rate environment in 2024 should pave the way for a reassertion of capital market-based deals, making the next few months busy ones for banks and deal-makers across the Mena region.


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Contractor wins $105m Medina university hospital deal
22 September 2026
-
 Oman tenders Thumrait Industrial City infrastructure
22 September 2026
-
 Kuwait halves drilling contractor pool
22 September 2026
-
 Abu Dhabi expects 45% emissions cut as electricity demand rises
21 September 2026
-
 Seven bid for Bahrain highway upgrade
21 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Contractor wins $105m Medina university hospital deal
22 September 2026
Riyadh-based construction firm Al-Mansouria General Contracting Company has been awarded a SR396m ($105.6m) contract to complete the remaining construction works on the Taiba University Hospital project in Medina.
The contract scope includes structural completion, remaining civil works, mechanical, electrical and plumbing installations, specialised clinical fit-outs and medical gas infrastructure to bring the long-stalled facility into operation.
Located on King Khalid Road along Medina’s Third Ring Road, the teaching hospital will have a capacity of 563 beds.
The contract duration is three years, with delivery targeted for late 2029.
The latest award follows a prolonged procurement cycle that began more than a decade ago as part of a public budget drive to expand Saudi Arabia’s higher education infrastructure.
The project’s first phase was initially signed in December 2011 with local firm Al-Muhaidib Contracting under a SR500m ($133.3m) contract.
Groundbreaking for the eight-storey complex took place in July 2013. The project covers a gross floor area of more than 200,000 square metres.
Progress stalled shortly thereafter due to reported structural delays and the reallocation of public capital budgets across the kingdom’s social infrastructure pipeline.
 READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Nuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19870032/main.jpg -
Oman tenders Thumrait Industrial City infrastructure
22 September 2026
Oman’s Public Establishment for Industrial Estates (Madayn) has tendered an estimated RO15m ($39m) contract to develop infrastructure for Thumrait Industrial City.
The tender was issued on 14 September, with bids due by 12 November.
The scope covers site-wide utilities and services, including an internal road network, stormwater channels and culverts. It also includes installing sewerage and water networks, along with landscaping works.
In addition, Madayn intends to build plug-and-play industrial units and a facilities building.
The first phase of the development will cover about 120,000 square metres (sq m).
Thumrait Industrial City is located in Oman’s Dhofar Governorate and spans an area of more than four million sq m.
The project location is close to concession blocks, quarry sites and the Najd agricultural areas. It is positioned to attract industrial investments in sectors such as mining and minerals processing (including gypsum and cement), food production, and a range of light and general manufacturing activities.
In March, Madayn said it is preparing to invest more than RO245m ($637m) to upgrade and expand infrastructure across its industrial cities between 2026 and 2030, as part of efforts to attract new investment and advance economic diversification.
According to media reports, Madayn chief executive Dawood Bin Salim Al-Hadabi said the programme is part of an expanded, phased plan aligned with Oman Vision 2040 and the authority’s long-term Madayn 2040 strategy.
The objective is to deepen Oman’s industrial base and spread growth across the sultanate’s governorates.
Madayn said the pipeline comprises about 90 strategic projects to improve industrial-city infrastructure, extend serviced land and increase the overall ease of doing business for investors.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19866218/main.jpg -
Kuwait halves drilling contractor pool
22 September 2026
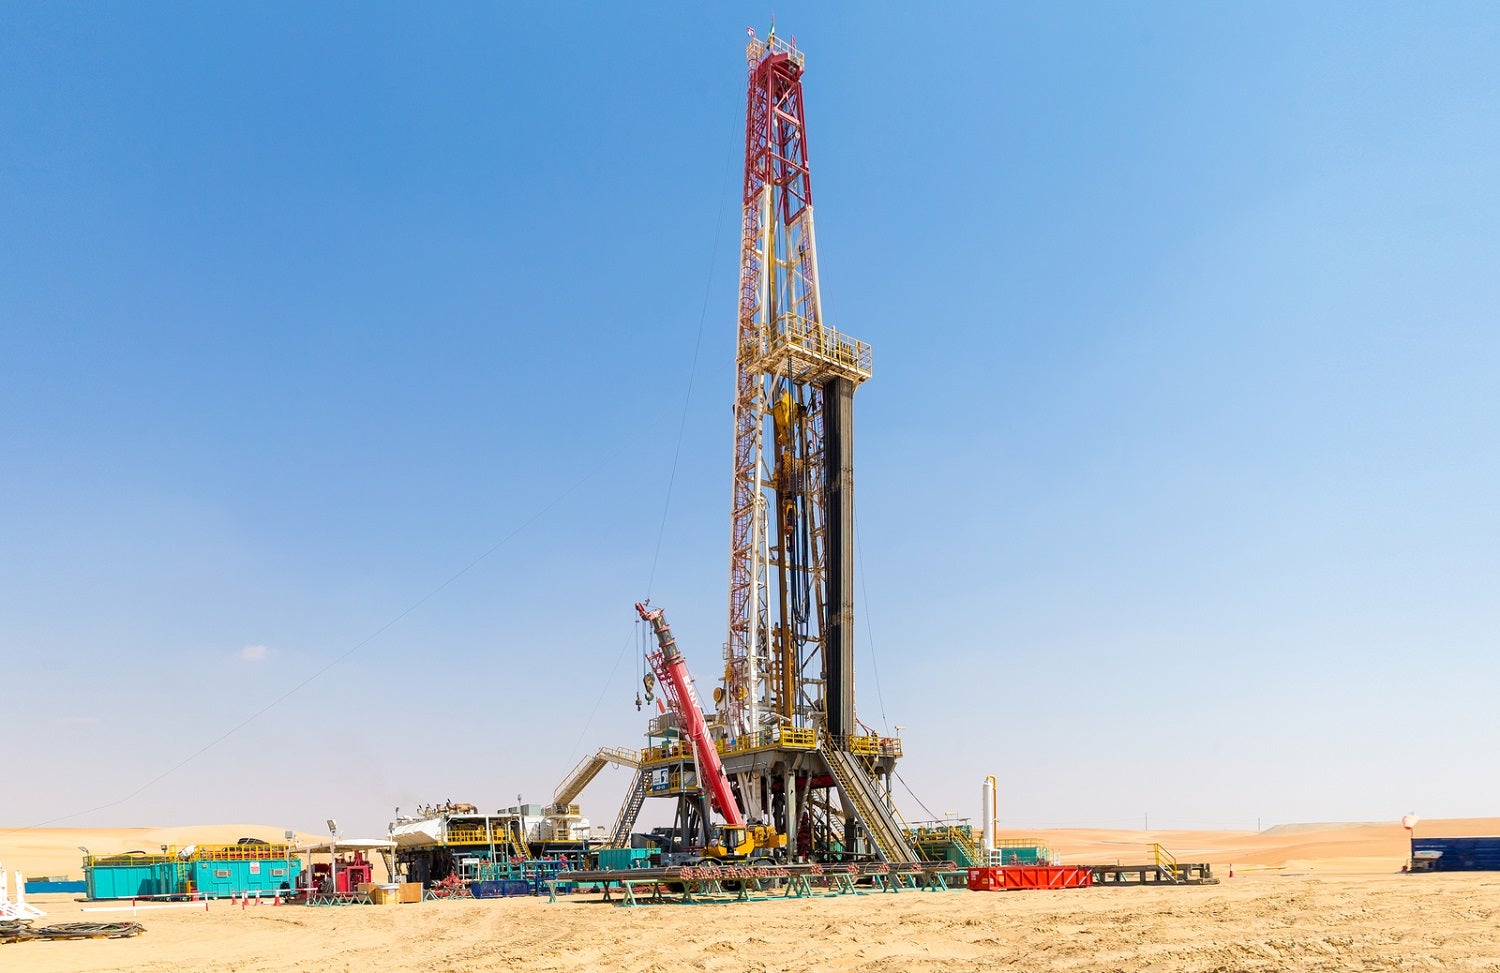
State-owned upstream operator Kuwait Oil Company (KOC) has reduced the number of approved contractors for onshore drilling and shallow-well maintenance from 51 to 24.
Firms that are no longer qualified include major contractors such as Italy’s Saipem, Oklahoma-based Helmerich & Payne and Houston-based Patterson-UTI Energy.
The latest list still includes a wide range of Kuwaiti, regional and international companies, according to the latest update on its electronic system, published on 21 September 2026.
The full list of contractors that are now qualified to participate in tenders is:
- Burgan Company for Well Drilling, Trading & Maintenance (Kuwait)
- Kuwait Drilling Company (Kuwait)
- Sun Drilling Kuwait (Kuwait)
- TDL Kuwait for Oil Rigs & Natural Gas Extraction Activities, Services and Facilities (Kuwait)
- United Precision Drilling (Kuwait)
- Abraj Energy Services (Oman)
- Adnoc Drilling Company (UAE)
- Arabian Drilling Company (Saudi Arabia)
- Anton Oilfield Services (China)
- China Oilfield Services (China)
- Egyptian Drilling Company (Egypt)
- CNPC Bohai Drilling Engineering Company (China)
- Great Wall Drilling Company (China)
- John Energy (India)
- Kerui Oilfield Service (China)
- KCA Deutag Drilling (Germany)
- Mohammed Al-Barwani Petroleum Services (Oman)
- Nabors Drilling International (US)
- National Drilling & Services Company (Oman)
- Sea & Land Drilling Contractors (Oman)
- Sinopec International Petroleum Service Corporation (China)
- Karamay Jianye Energy (China)
- Modern Drilling Company (Egypt)
- Grey Wolf Drilling International (US)
An earlier list, which was published on 11 February, included 51 qualified companies.
The reduction in qualified drilling contractors follows KOC’s notice on 27 April this year, informing existing qualified contractors that they would need to reapply.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19863744/main3435.jpg -
Abu Dhabi expects 45% emissions cut as electricity demand rises
21 September 2026
Register for MEED’s 14-day trial access
Abu Dhabi-based Emirates Water & Electricity Company (Ewec) expects carbon emissions from power and water production to fall by more than 45% by 2035 as the UAE expands renewable energy and reverse osmosis (RO) desalination.
The state offtaker's latest long-term system planning forecasts emissions will decline from about 42 million tonnes in 2019 to approximately 23 million tonnes in 2035.
The reduction is expected despite annual electricity demand that is forecast to rise by about 70% in 2026-33.
Ewec said the expansion of renewable energy and the shift towards RO desalination will be the principal drivers of the reduction.
The company plans to increase Abu Dhabi's solar capacity to 14GW by 2030 and more than 35GW by 2035. This will be supported by up to 15GW of battery storage capacity.
According to regional project tracker MEED Projects, Ewec has over $16bn-worth of power and water projects in the execution stage as part of its long-term procurement programme to increase renewable energy and low-carbon water production capacity.
This includes a 5.2GW Abu Dhabi solar and battery energy storage system (bess) round-the-clock renewable energy project, as well as three 1.5GW solar photovoltaic independent power projects (IPP): Al-Ajban, Al-Khazna and Al-Zarraf.
It also comprises the 1GW Al-Dhafra open-cycle gas turbine power plant, the 2.5GW Taweelah C combined-cycle gas turbine (CCGT) plant and a separate 400MW bess IPP.
As previously reported, it is expected that the developer's agreement for the 3.3GW Al-Nouf 1 CCGT IPP will be signed by the end of the year, while contractors are preparing to submit bids for a separate 2.6GW power plant project in Ajman.
The expansion of solar and battery storage is expected to reduce the system's reliance on gas-fired generation. However, gas-fired generation will continue to provide flexibility to support the system and balance intermittent renewable power output, according to Ewec.
The offtaker also expects RO desalination to account for more than 95% of total water production by 2035, with the procurement programme supporting the Abu Dhabi Department of Energy's Clean Energy Strategic Target 2035 for electricity production and the UAE Net Zero by 2050 Strategy.
READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFNuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19849749/main.jpg -
Seven bid for Bahrain highway upgrade
21 September 2026
Register for MEED’s 14-day trial access
Seven contractors have submitted bids for the next phase of the Sheikh Jaber Al-Ahmed Al-Sabah Highway upgrade project.
According to results published by the Bahrain Tender Board, the firms that have submitted bids include:
- Nass Contracting Company
- Haji Hassan Group
- Almoayyed Contracting Group
- Mohammed Abdulmohsen Al-Kharafi & Sons
- Eastern Asphalt & Concrete Production
- Cebarco Bahrain
- Kingdom Asphalt
The contract scope includes expansion works on 2 kilometres of the highway. It consists of a four-lane dual carriageway with service roads on both sides.
The scope of works also includes excavation and backfill work, construction of stormwater drainage networks, a pumping station, installation of ducts for future utilities, upgraded street lighting, traffic signs and directional signage.
The project aims to improve traffic capacity, reduce congestion and enhance safety along the transport corridor linking Manama with industrial zones.
In April, MEED reported that Bahrain had approved a financing agreement framework to fund the construction of the next phase of the Sheikh Jaber Al-Ahmed Al-Sabah Highway upgrade.
In March last year, the Kuwait Fund for Arab Economic Development and the Bahraini government signed a KD10m ($32.4m) loan agreement to fund the second phase of the project, which is expected to cost about $404m.
This was followed in September 2025 by the appointment of US-based Parsons Corporation on a $1.5m contract to provide pre-contract engineering consultancy services for the project.
According to data from regional project tracker MEED Projects, construction of the first phase was completed in 2020.
A joint venture of local firm Nass Contracting and Kuwait’s KCC Engineering & Contracting undertook the main construction works.
READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFNuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19847073/main.png