Lebanon economic recovery postponed
4 June 2024

The visit to Lebanon by the IMF in May reveals a stark picture of an economy now in its fifth year of intense turmoil following its October 2019 exchange rate collapse, and one which now faces significant additional headwinds.
The IMF’s end-of-mission statement identified a lack of action on economic reforms as exerting a heavy economic toll, while flagging negative spillovers from fighting on the country’s southern border as an exacerbating factor for the already dire economic and social situation.
Yet, despite this apparent dismal assessment, Lebanon can legitimately claim to have turned a corner last year.
Implementing monetary and fiscal reforms has seen the phasing out of monetary financing, the termination of the electronic foreign exchange platform, tighter fiscal policy, and steps towards the unification of exchange rates.
These measures have helped contain exchange rate depreciation, stabilise the money supply and reduce inflationary pressure, the IMF said.
Nassib Ghobril, chief economist at Beirut-based Byblos Bank, agrees. “Last year was a very good year for Lebanon, the first year where the economy was on track to post a positive growth rate since 2017,” he says.
After the first nine months of 2023, Ghobril’s forecast for real GDP growth was 2%, driven by stellar tourism activity that so far that year had produced knock-on benefits for 14 sub-sectors, in addition to improved activity in the wider industrial, agricultural and services sectors.
“And then 7 October and 8 October happened, and that created a shock that put a hold on this momentum — and that’s continuing,” he says.
Contingent growth
Lebanon’s economic outlook now hinges largely on the outcome of the conflict in Gaza and the related violence between Hezbollah and the Israeli Defence Forces, which has forced widespread displacement of the southern population, besides disrupting agriculture and tourism.
Looking ahead, Ghobril predicts a continuation of the current status quo, which would result in a real GDP contraction of 0.5-1% in 2024, at 40% probability. If the conflict expands – also a 40% probability – then it could realise a more serious contraction of 15-20%.
On the other hand, says Ghobril, in a ceasefire scenario, which he puts at 20% probability, “the sooner it happens, we would have a rebound in growth based on the positive shock, the reconstruction of the south and better visibility”.
Tourism revival, important to Lebanon as a hard currency generator, is highly contingent on a stable security situation, even beyond the southern areas most impacted by the fighting.
Minister of Economy and Trade Amin Salam warned in February that it was unclear if visitors from the Lebanese diaspora and elsewhere, who injected about $5-7bn into the economy last summer, would come to the country this season. In Q1 2024, total passenger numbers at Beirut International airport decreased by 6.7% in year-on-year terms to 1.27 million, according to Banque Audi figures.
The conflict’s direct impact on the south has been stark. According to Banque Audi, more than 6,000 acres of forest and agricultural land have been damaged, up to 2,100 acres completely burned, and more than 60,000 olive trees destroyed.
Meanwhile, an estimated 93,000 people have been internally displaced, contributing to an estimated 75% decline in economic activity in the south. The sense that the Israel-Hamas war has stunted Lebanon’s recovery is hard to avoid, rolling back the progress seen in 2023.
Fiscal stabilisation
The IMF has nevertheless lauded the government’s measures to boost revenue collection from VAT and customs, which it said helped close the fiscal deficit to zero last year.
“Looking ahead, we anticipate the fiscal balance to remain close to zero in 2024, on limited financing options and improved revenue collection permitted by the exchange rate adjustment on custom duties and VAT. CPI inflation is expected to stabilise on lower unsterilised interventions of Banque du Liban,” says Thomas Garreau, an analyst at Fitch Ratings.
Balancing current spending looked to be within reach. The government’s budgeted figures for 2024 envisage public spending amounting to $3.4bn, matched by public revenues of $3.4bn, despite an increase in public sector wages of $40m a month.
Exchange rate stabilisation is a clear win for Lebanon. The pound has been stable at £Leb89,500 to the dollar since the end of July 2023 despite multiple security incidents not related to the conflict in the south of the country.
“That’s still ongoing because the central bank managed last year to sterilise liquidity and Lebanese pounds from the market to reduce the differential between the quasi-official exchange rate of the central bank and the parallel market rate, and to stop the speculation on the currency. So it managed to stop the depreciation of the currency,” says Ghobril.
Foreign exchange reserves, which eroded heavily in the post-2019 crisis period, appear to have steadied. The liquid foreign assets of the central Banque du Liban grew by $382m in Q1 2014, reaching $9.6bn.
As Banque Audi notes, the cumulative growth of $1bn in the central bank’s liquid foreign assets since the end of July 2023 is mostly linked to its refraining from any government finance.
Yet the more lasting changes needed to shift the dial on Lebanon’s economic narrative remain elusive.
Bank deposits are frozen, notes the IMF, and the banking sector is unable to provide credit to the economy, as the government and parliament have been unable to find a solution to the sector’s crisis.
Addressing the banks’ losses while protecting depositors is seen as indispensable to economic recovery.
It does not help that the country has been without a president since October 2022, leaving caretaker Prime Minister Najib Mikati without a full mandate to undertake reforms.
This matters because banking system recovery hinges on political will to implement reforms. Yet the vacuum at the presidential palace leaves little prospect of imminent progress on this front.
“Despite some politicians’ comments, I do not see prospects of an end to the political deadlock as long as the war is ongoing in the south. And even if it suddenly stopped, you would need several months for an overall settlement to materialise on the domestic political front,” says Ghobirl.
The present situation leaves Lebanon politically and economically hobbled, with fears of worse to come due to external events beyond its control.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Kuwait on track to hit oil production target
7 October 2026
-
 Al-Yamamah signs Saudi 380kV transmission deals
6 October 2026
-
 Eagle Hills plans new Syria projects
6 October 2026
-
-
 Dubai issues PMC tender for four stormwater projects
6 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Kuwait on track to hit oil production target
7 October 2026
Kuwait is on track to meet its target of having 4 million barrels a day (b/d) of oil production capacity by 2035, according to Kuwait Petroleum Corporation (KPC) chief executive Shaikh Nawaf Al-Sabah.
Al-Sabah also said Kuwait is on course to increase non-associated gas production to 2 billion cubic feet a day by 2040.
His comments come amid an ongoing crisis in Kuwait’s oil and gas sector linked to the regional conflict that began when the US and Israel attacked Iran on 28 February.
The subsequent war has significantly disrupted shipping through the Strait of Hormuz, which is a crucial export route for Kuwaiti crude oil.
Kuwait is currently producing around 2 million b/d of oil, down from 2.6 million b/d before the US and Israel attack.
Speaking at a conference in London, Al-Sabah said: “We have the capacity to go back up to our current maximum sustainable capacity of 3 million b/d, if we have the export routes available, and this comes down to the ability to move oil through the Strait.”
KPC is investing $9bn-$10bn a year in capital expenditure to meet its oil and gas production goals, according to Al-Sabah.
He said: “We are doing this because we recognise that it is our hydrocarbons that will be most in demand a decade from now, and two decades from now – in fact, for the rest of our lifetimes.”
Project Seef
KPC is pushing ahead with the Al-Seef project, which focuses on developing three large offshore oil discoveries, Al-Sabah said.
The offshore fields are known as Nokhatha, Julaia and Jazza. The development was first announced in February this year, about two weeks before the US and Israel attack on Iran.
Al-Sabah said KPC is continuing with the project and believes the three fields collectively hold more than 3 billion barrels of recoverable oil.
He said: “We are asking international oil companies to partner with us to develop those resources under an operating services contract.
“So, we’re moving ahead according to the exact same schedule that we had put together even before the war began.”
Al-Sabah did not say which international oil companies KPC has approached to help develop the three offshore fields.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20315147/main.jpg -
Al-Yamamah signs Saudi 380kV transmission deals
6 October 2026
Riyadh-headquartered Al-Yamamah Steel Industries has signed two supply contracts with Algihaz Contracting Company for the construction of 380kV ultra-high-voltage transmission lines in Saudi Arabia’s Western Region.
The contracts cover the supply of steel towers and are worth a combined SR254.28m ($67.8m).
In a disclosure to the Saudi Exchange (Tadawul), the firm said the first contract is valued at SR135.65m ($36.2m), while the second is worth SR118.63m ($31.6m).
Both contracts have a one-year duration, with supply scheduled to begin in March 2027. The financial impact of the contracts is expected to start appearing in Al-Yamamah Steel’s results in the first quarter of 2027.
Algihaz is currently carrying out construction works for several transmission projects, including Saudi Energy’s $206m Bisha 380/132kV BSP connection project, for which it was appointed the main contractor in 2025.
The project involves a double-circuit 380kV overhead transmission line connecting the Bisha PV bulk supply point to the existing bulk supply points in Aseer Province.
The deals also add to a series of steel tower contracts secured by Al-Yamamah Steel for 380kV transmission projects in the Western Region.
In September, the company signed a SR103.14m ($27.5m) contract with the Saudi branch of National Power Construction Corporation to supply steel towers for a 380kV ultra-high-voltage line. Supply under that contract is due to begin in February 2027.
Al-Yamamah Steel also signed a SR176.48m ($47.1m) contract in November 2025 with Arabian Electrical Transmission Line Construction Company to supply steel towers for another 380kV ultra-high-voltage line in the Western Region.
The company has expanded its tower production capacity in recent years to meet expected demand for steel towers used in electricity transmission lines. Its 2024 annual report said it had added production lines and a galvanising plant in Jeddah Industrial City for this purpose.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20308551/main.jpg -
Eagle Hills plans new Syria projects
6 October 2026
Abu Dhabi-based real estate developer Eagle Hills has signed a framework agreement with Syria’s Ministry of Public Works & Housing to develop a series of residential and tourism community projects across several Syrian governorates.
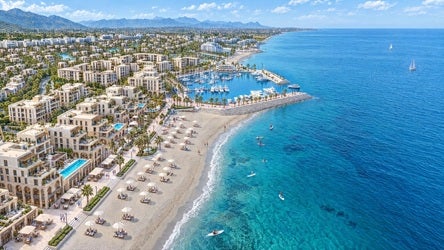
The first phase will include Damascus Heights in the capital and Latakia Yachts & Marina on the Mediterranean coast.
Damascus Heights is planned as a mixed-use community comprising homes, retail, hospitality and business facilities, supported by schools, healthcare services, green areas and resident amenities.
Latakia Yachts & Marina is planned as a waterfront destination anchored by a marina, with homes, hotels, branded residences and leisure offerings.
During development and operation, the projects are expected to support economic activity and tourism, create jobs across construction, hospitality and services, and add new housing, community facilities and tourism infrastructure.
Syrian professionals and businesses are expected to play a central role in both delivery and operations, creating opportunities for contractors, suppliers and service providers, strengthening local supply chains and SMEs, and supporting skills development and knowledge transfer.
Eagle Hills is also inviting applications for investment participation from Syrians in Syria and abroad, with priority for qualified Syrian individuals, businesses and institutions.
Following the signing, both projects will proceed to implementation, with enabling and construction works expected to begin shortly in Damascus and Latakia.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20308460/main.jpg -
Contractors submit revised bids for Dukhan field facilities upgrade
6 October 2026
Contractors have submitted revised proposals to QatarEnergy for a key tender to upgrade facilities at the Dukhan oil field in Qatar, about 80 kilometres west of Doha.
Following the submission of the initial round of bids for the project on 9 August, QatarEnergy requested revised proposals from contractors, which they submitted by 27 September, sources told MEED.
The following local contractors, among others, are understood to be bidding for the DPFU Phase 1B (Part 2) tender, according to information obtained by MEED Projects:
- Doha Petroleum Construction Company (Dopet)
- Galfar Al-Misnad Engineering & Contracting
- Qatar Engineering & Construction Company (Q-con)
QatarEnergy originally stipulated a bond validity of 150 days (until 23 December) and a bid validity of 120 days (until 23 November) for the project.
The engineering, procurement, installation and commissioning scope covers upgrades to 56 oil manifolds, 108 gas-lift manifold slots, chemical injection systems and key pumping facilities, along with associated piping, instrumentation, control, electrical and civil works.
The scope includes the demolition of obsolete equipment, degassing station enhancements, and full testing and handover. It also encompasses additional capacity enhancement works under Part 3, mainly the installation of new oil export and produced-water transfer pumps, along with supporting facility modifications.
The project involves complex interfaces and shutdown-critical activities, requiring expertise in live-plant integration.
QatarEnergy issued the tender for the DPFU Phase 1B (Part 2) project on 8 June and initially set a bid submission deadline of 26 July, later extending it to 9 August.
Dukhan, Qatar’s first and only onshore oil field, was discovered in 1938, with oil production starting in 1939-40. The country currently produces about 1.8 million barrels a day (b/d) of crude, with the Dukhan field accounting for about 350,000 b/d.
The Dukhan oil field covers about 80km by 8km and consists of four reservoirs: Khatiyah, Fahahil, Jaleha and Diyab. The first three are oil reservoirs. The more recently developed Diyab reservoir contains non-associated gas and is estimated to hold around 2 billion barrels of crude oil reserves. Diyab lies on Dukhan’s southern flank.
ALSO READ: QatarEnergy selects contractors for offshore oil field expansion
https://image.digitalinsightresearch.in/uploads/NewsArticle/20306273/main5440.jpg -
Dubai issues PMC tender for four stormwater projects
6 October 2026
Dubai Municipality has invited consultants to bid for a contract to provide construction supervision services for four stormwater projects.
The bid submission deadline is 29 October.
All four projects are part of the municipality’s Tasreef programme, intended to increase Dubai’s rainwater drainage capacity by 700% by 2033 and provide capacity for the emirate’s needs for the next 100 years.
The tender for TF-06-S1 Supervision of Stormwater Drainage System Projects – Package 4 was issued on 6 October.
The consultancy covers the following projects:
- TF-06-C1: Construction of a stormwater pond connecting Al-Maktoum Airport and Dubai South
- TF-06-C2: Construction of a stormwater drainage system connecting Al-Maktoum Airport and Dubai South
- TF-07-C1: Construction of a stormwater drainage system on Sheikh Zayed Bin Hamdan Road connecting developers
- TF-24-C1: Connecting developers’ areas to the stormwater networks in Dubailand
In documents seen by MEED, the municipality said it will require a dedicated supervision team for each project.
The consultancy will cover construction supervision, including the deployment of resident engineers, civil engineers, inspectors, quantity surveyors, land surveyors and planning engineers. Mechanical engineers will also be required, along with health and safety personnel and NOC engineers, depending on the project.
TF-07-C1 is the same strategic stormwater drainage project that Dubai Municipality recently tendered for construction, with contractors preparing to submit bids on 22 October.
The project covers more than 100 million square metres between Sheikh Mohammed Bin Zayed Road and Emirates Road, and from Expo Road to Dubailand.
It will provide stormwater infrastructure and service connections for more than 20 private developers and Al-Yalayis 5, as well as supporting major roads in the Jebel Ali area. The construction scope includes a major gravity drainage system with pipeline diameters of up to 3,000mm.
TF-24-C1 is one of three water infrastructure tenders issued by the municipality in August, as reported by MEED. The project will connect developers’ areas in Dubailand to the stormwater network. It includes 18 kilometres (km) of stormwater drainage pipelines with diameters of up to 1,800mm and 3.5km of gravity sewer pipelines with diameters of up to 1,000mm.
Bidding for the engineering, procurement and construction contract was recently extended to 1 October, with Nael Construction & Contracting and Al-Nasr Contracting Company among those expected to make an offer for the project.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20305174/main.jpg