Kuwaiti banks hunt for growth
15 August 2024
The broader economic backdrop for Kuwaiti lenders is relatively more challenging than for peers in other Gulf states, with the state budget back in deficit territory and oil revenues down 20% in 2023-24.
The Washington-based IMF estimates real economic activity to have fallen by 2.2% in 2023, with the oil sector contracting by 4.3% due to Opec+ production quota cuts.
Even so, Kuwaiti lenders have managed to put in some decent performances, benefitting – like their Gulf peers – from stronger net interest margins (NIMs) that have flowed from the global high interest rates of recent years.
Overall banking sector profits grew at an impressive 28.7% in 2023, according to Kamco Invest Research.
This year, profit performances are unlikely to match such increases. Traditionally the country’s largest bank, National Bank of Kuwait (NBK), for example saw a 6.2% increase in first-half 2024 profits to KD292.4m ($953.6m).
Kuwait Finance House, newly enlarged since its acquisition in February this year of Ahli United Bank (AUB), creating one of the largest Islamic banks globally, reported a 2.3% increase in net income to KD341.2m ($1.12bn) for the same period.
Policy pressure
Higher interest rates have exerted a negative impact on lending in Kuwait; according to the IMF, growth in credit to the non-financial private sector fell in 2023 to only 1.8% as bank lending rates rose in response to gradual policy rate hikes by the Central Bank of Kuwait (CBK), broadly in line with global monetary policy tightening.
However, it added that in light of prudent financial regulation and supervision, banks have maintained strong capital and liquidity buffers, while their profitability has rebounded from pandemic lows, and non-performing loans remain low and well provisioned for.
One challenge facing Kuwaiti lenders is that the domestic market still does not provide sufficient lending opportunities to materially impact their performances. In part, this reflects familiar issues related to Kuwait’s unique political structure.
“Political conflicts involving the parliament and the government delayed the much-needed fiscal and economic reforms, which have put pressure on growth and limit the credit growth potential of the banking sector,” says Gilbert Hobeika, a director at Fitch Ratings.
This has implications for Kuwait’s lenders because if they cannot grow domestically, they will likely look beyond the country’s borders.
Looking beyond Kuwait is designed to create market share and build stronger franchises.
KFH is a case in point. Upon completion of its merger with AUB Kuwait, it is now placed as a rival of NBK in terms of size, giving it the critical mass to enable it to consider expanding into other GCC markets. Market speculation has centred on the potential acquisition of a large stake in Saudi Investment Bank.
There is also the prospect of another large domestic merger, with Boubyan Bank and Gulf Bank, two Kuwait-listed sharia-compliant lenders, undertaking an initial feasibility study for a potential tie-up. Further consolidation moves could see a conventional lender absorbing an Islamic player or gaining an Islamic subsidiary. All options remain open.
Relative weakness
That focus on inorganic expansion also reflects the weaker profitability seen in Kuwait’s banking sector relative to other GCC banking markets.
There are several reasons for this, says Hobeika. “One is that Kuwait has one of the highest loan loss allowance coverages of stage three loans, meaning that while you could see in the region of 70-120% in the GCC, in Kuwait banks could reach 500% and on average around 250%. This is because the CBK is much more conservative than any other regulator in the region.”
The other point is the pressure on Kuwaiti banks’ NIMs. Different considerations explain why Kuwaiti banks have not benefitted from higher NIMs in the same way as Saudi or UAE banks have.
“The dynamics are really different,” says Hobeika. “One is the pricing cap set by the Central Bank, and then you’ve got the fixed interest rates on retail loans, so they cannot increase their pricing. Then you’ve got a huge amount of murabaha on the Islamic side, which are fixed for long durations.”
In an overbanked economy such as Kuwait, the result is increased competition, with banks bidding to take a piece of a small cake.
That said, the effective supervision of the CBK provides for some additional support for banks.
“They will provide some relief for them to be able to generate efficient operating profit, to support their capital and internal generation of capital. Even if the performance is lower, it’s still sufficient to support internal capital generation,” says Hobeika.
The NIM situation reflects Kuwait’s distinctive policy approach. CBK does not systemically follow the US Federal Reserve’s interest changes, meaning that typically, every two or three changes made by the Fed will be followed by a single change in Kuwait.
According to an analysis by Kuwait-based research firm Marmore, the approach of skipping interest rate tweaks has meant that while the overall NIM has changed in line with the global policy rate, the magnitude of change has been smaller. For that reason, NIMs might not decline for all Kuwaiti banks in the anticipated forthcoming easing cycle.
Marmore notes that this year, while banks such as NBK expect their NIMs to be stable, other banks have highlighted the difficulty in providing guidance for NIMs given the uncertainty over the timing and magnitude of rate cuts.
And while some Kuwaiti lenders have not gained as much benefit as other Gulf banks from higher interest rates, they may yet feel the positive impact from lower rates, given that retail loans are fixed.
These advantages may seem marginal, but in a global climate where lower interest rates will reduce the capacity to generate easy profits as in past years, they may prove to be welcome for Kuwait’s lenders.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Borouge puts butene-1 expansion project on hold
16 November 2026
-
 Contractor wins Saudi Energy substation deal
16 November 2026
-
 WEBINAR: End-of-Year Mena Market Review
13 November 2026
-
 Syntys breaks ground on 20MW Qatar data centre
13 November 2026
-
 Riyadh airport tenders general consultancy services
13 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Borouge puts butene-1 expansion project on hold
16 November 2026

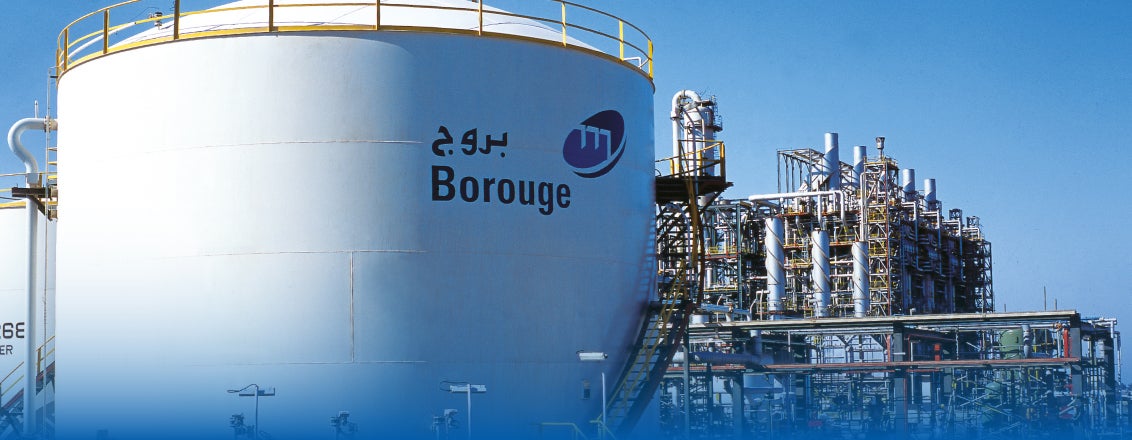
Abu Dhabi petrochemicals producer Borouge, now part of Austria-headquartered Borouge International, is said to have put on hold a project to increase butene-1 production from the olefins conversion unit (OCU) at its Borouge 2 facility in Ruwais Industrial City.
Under the proposed project, Borouge planned to produce 60,000 tonnes a year (t/y) of butene-1 from the existing fractionator column while limiting propylene production from the OCU to 500,000 t/y.
The company intended to achieve this by adding co-monomer production technology and selective hydrogenation units, while retaining the capability to run the unit at its original design capacity of 752,000 t/y of propylene and 39,000 t/y of butene-1. The scope also entailed expanding butene-1 storage capacity by converting existing N1 mixed-butane spheres into dedicated butene-1 units.
According to sources, Borouge informed contractors in the weeks after receiving bids that it had decided to shelve the tender.
Contractors submitted technical bids for the engineering, procurement and construction (EPC) package by 1 September 2025, following several extensions to the original 23 June deadline. Borouge had initially released an advanced tender notice in May last year, followed by the main EPC tender on 4 June, and hosted a site visit for bidders on 25 June.
Contractors understood to have submitted bids include:
- Galfar Emirates (UAE subsidiary of Oman’s Galfar Engineering & Construction)
- Target Engineering Construction (UAE)
US-based Lummus Technology was previously awarded the contract to provide the process design package for the new co-monomer production unit as the OCU licensor. Lummus sub-contracted the extended process design package and basic engineering works to South Korea’s Samsung E&A. Borouge had targeted an EPC contract award in the first quarter of 2026.
Butene-1 is a colourless gas primarily used as a co-monomer in the production of high-grade polyethylenes and poly(1-butene), serving end markets such as specialty films, bags and food packaging.
ALSO READ: Borouge prepares to tender construction works for ethane cracker expansion
Borouge International was formed through the combination of Adnoc Group and OMV’s shareholdings in Borouge and Austria-based Borealis, alongside the acquisition of Canada-based Nova Chemicals. In July, Adnoc announced it would transfer its holding in Borouge International to its global investment arm, XRG.
Borouge began operations in 2001 with 450,000 t/y of polyethylene capacity. The Borouge 2 and Borouge 3 expansions raised overall capacity to 2 million t/y in 2010 and 4.5 million t/y in 2014, respectively. Once the Borouge 4 expansion is commissioned, total production capacity will increase from 5 million t/y to 6.4 million t/y, creating the world’s largest single-site polyolefins facility.
Borouge 4 will add two polyethylene units with a combined capacity of 1.4 million t/y (700,000 t/y each) based on Borealis’s third-generation Borstar technology, supplied by a 1.5 million t/y ethane cracker and associated derivative units.
ALSO READ: Borouge restores Ruwais complex after Iranian attacks
https://image.digitalinsightresearch.in/uploads/NewsArticle/21443754/main.jpg -
Contractor wins Saudi Energy substation deal
16 November 2026
Local firm Alfanar Projects has signed a contract with Saudi Energy, formerly Saudi Electricity Company, to build a 115/13.8kV substation in Al-Aqiq, Al-Bahah province, a source confirmed to MEED.
The station will receive electricity at 115kV and step it down to 13.8kV for local distribution. The scope of work includes site preparation, civil works, substation buildings and foundations, and the supply and installation of power transformers and associated electrical equipment.
Seventeen firms submitted bids for the project in May. The bidders included:
- Al-Babtain Contracting
- Al-Gihaz Holding
- Al-Haider Company
- Alfanar Projects
- Cepco
- Energy & Infrastructure Company (Eico)
- Expertise Contracting
- Haif Company
- JAL International
- Maetel Saudi Arabia Construction Company
- Mohammed Al-Ojaimi Group
- Nesma Infrastructure & Technology
- Nour Energy Company
- PA Cost International
- Sama Energy
- Saudi Projects & Supplies Company
- Tareg Al-Jaafari Contracting Establishment
According to regional project tracker MEED Projects, AlFanar Projects had won up to eight awards for substation projects this year, prior to the Al-Aqiq award.
The largest is a contract worth more than SR122m ($32.5m) to construct a 132/13.8kV substation for the Expo 2030 Riyadh site.
The firm was one of four contractors selected by Saudi Energy to deliver electricity infrastructure for the site, MEED reported in August.
Recent contracts include the 380kV Tumair PV substation (#9127), the Busita-C 132/33kV substation, the 132/13.8kV substation north of Al-Kharj (#8721) and the Al-Sahafa 132/13.8kV new substation (#8316).
Saudi Energy has tendered several other 380kV substations and associated transmission lines this year, including projects serving planned solar and wind developments in the kingdom’s central, western and southern regions.
Earlier, in November, MEED exclusively reported that China’s TBEA Shandong Luneng Taishan Cable Company (TBEA) and Egypt’s Elsewedy had submitted the lowest bids for two substation projects in Riyadh Province, estimated to cost a combined $100m.
The tenders for the Thadeq PV and Qiddiya 2 bulk supply points were issued earlier this year, with bids submitted in August and November, respectively.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21443095/main.jpg -
WEBINAR: End-of-Year Mena Market Review
13 November 2026
Webinar: The big questions shaping the Gulf market. You decide what gets debated.
Tuesday 24 November 2026 | 11:00 AM GST | Register now
What makes this session particularly interesting is that the audience gets to decide the agenda. Registrants can vote for the topics they’d like Ed and Colin to debate, with the most popular questions forming the final shortlist for the live session.
Topics in the ballot:
- Is the Gulf trying to build too much, too quickly?
- Saudi Arabia or the UAE: where would you place your next big bet?
- Are gigaprojects the best use of public money?
- Who is really responsible when projects go wrong?
- Should the lowest-price tender become a thing of the past?
- Can private capital take over from the government in financing infrastructure and diversification?
- Is the Gulf’s AI and data centre boom a smart bet or the next overbuilding risk?
- Should the Gulf double down on hydrocarbons to fund diversification?
- Is localisation strengthening the economy or making delivery harder?
- Are Gulf countries building complementary economies or competing for the same customers?
The session will also feature live audience polling and Q&A, giving attendees an opportunity to share their views.
Hosted by:
Edward James, head of content and analysis at MEED
 A well-known and respected thought leader in Mena affairs, Edward James has been with MEED for more than 19 years, working as a researcher, consultant and content director. Today, he heads up all content and research produced by the MEED group. His specific areas of expertise are construction, hydrocarbons, power and water, and the petrochemicals market. He is considered one of the world’s foremost experts on the Mena projects market. He is a regular guest commentator on Middle East issues for news channels such as the BBC, CNN and ABC News and is a regular speaker at events in the region.
Colin Foreman, editor of MEED
 Colin Foreman is editor and a specialist construction journalist for news and analysis on MEED.com and the MEED Business Review magazine. He has been reporting on the region since 2003, specialising in the construction sector and its impact on the broader economy. He has reported exclusively on a wide range of projects across the region including Dubai Metro, the Burj Khalifa, Jeddah Airport, Doha Metro, Hamad International airport and Yas Island. Before joining MEED, Colin reported on the construction sector in Hong Kong.https://image.digitalinsightresearch.in/uploads/NewsArticle/21380319/main.gif
-
Syntys breaks ground on 20MW Qatar data centre
13 November 2026
Register for MEED’s 14-day trial access
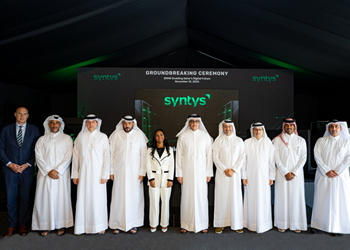
Qatari data centre developer Syntys has broken ground on a 20MW facility to support hyperscale, cloud, artificial intelligence (AI) and advanced computing deployments.
The groundbreaking ceremony took place on 12 November. It was attended by Qatar’s Communications & Information Technology Minister, Mohammed bin Ali bin Mohammed Al-Mannai, along with representatives from Ooredoo Group, Microsoft, Google, Kahramaa, the National Cyber Security Agency, Qatar Free Zones Authority and local banks.
Syntys said the facility is being developed on an existing company campus, where power, fibre connectivity and an operational team are already in place. The company has yet to disclose the project value or planned completion date.
The facility is designed to meet Tier 3 requirements and accommodate a range of rack densities, including higher-density configurations for graphics processing unit (GPU)-based AI and high-performance computing workloads.
It will operate as a carrier-neutral facility, allowing customers to select connectivity providers and establish network resilience in line with their own technical and operational requirements.
The project forms part of Syntys’ strategy to expand its Qatar platform through acquisitions and new development. Earlier this year, the company acquired QData QFZ, adding two operational, Tier 3-compliant, carrier-neutral facilities to its portfolio.
Syntys now owns and operates four campuses in Qatar, allowing customers to establish primary and disaster-recovery environments at separate in-country locations.
The company also designs and operates the facilities supporting Ooredoo’s sovereign AI cloud, which uses Nvidia Hopper GPUs.
The development comes as Qatar implements its Digital Agenda 2030, which identifies digital infrastructure as one of six strategic pillars and targets about QR40bn ($11bn) in economic impact by 2030.
The data centre is expected to support the growth of in-country digital services and enable sensitive workloads to remain within Qatar’s national borders.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21378257/main1028.png -
Riyadh airport tenders general consultancy services
13 November 2026
Register for MEED’s 14-day trial access
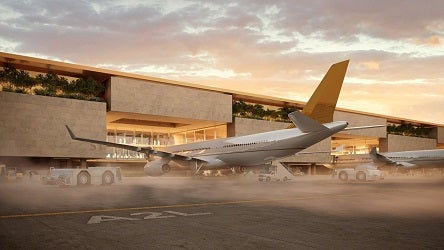
Saudi Arabia’s King Salman International Airport Development Company has tendered a contract for general consultancy services for the King Salman International airport project in Riyadh.
Tender documents were issued on 1 November and consultants have until 29 November to submit bids.
Tender clarification queries closed on 11 November, following a mid-bid briefing meeting. Technical and commercial bids will be evaluated in December.
The selected consultant will provide comprehensive engineering services, covering design, construction and completion stages, delivered through individual service orders issued by the client.
The scope of services includes:
- Preparing requests for proposals for design and engineering-related packages;
- Conducting technical feasibility studies;
- Preparing design and related documentation for aviation and non-aviation assets, support facilities and commercial real estate across the airport masterplan;
- Managing regulatory compliance and securing approvals from entities including the General Authority of Civil Aviation and Riyadh Airports Company;
- Providing design peer review services to evaluate third-party designs for completeness, constructability, value engineering and code compliance.
Under the procurement conditions, bidders must comply with local content rules established by the Local Content & Government Procurement Authority, including an audited baseline local content score, a target score and a Saudisation plan.
Multinational firms operating in the region must also hold an active regional headquarters licence issued by Saudi Arabia’s Investment Ministry. Subcontracting will be restricted to a single tier.
Planned to cover an area of 57 square kilometres (sq km), the project includes approximately 45 sq km of aeronautical land and an estimated 10 sq km terminal footprint featuring the Iconic Terminal, Terminal 6 and private aviation facilities.
The airport is designed to handle 120 million passengers and 2 million tonnes of cargo a year by 2030, rising to 185 million passengers and 3.5 million tonnes of cargo by 2050, with an ultimate capacity of 225 million passengers.
The remaining 12 sq km of the site is allocated to Airport City, an urban development that will accommodate about 80,000 residents and will include residential, commercial, hospitality, retail, entertainment, logistics and industrial assets.
The airport masterplan was launched in November 2022 by Crown Prince Mohammed bin Salman bin Abdulaziz Al-Saud. The project is backed by the Saudi sovereign wealth vehicle, the Public Investment Fund, as part of Saudi Arabia’s Vision 2030 economic transformation strategy.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21377681/main.jpg