Kuwaiti banks enter bounce-back mode
10 August 2023

With low levels of non-performing loans (NPLs) and improving funding metrics, 2023 is proving to be a solid year for Kuwaiti banks. At the same time, the promise of project-related lending is also starting to firm up on the horizon.
Profitability is trending in the right direction, with half-year results in 2023 revealing robust performances for the largest banks in the tightly knit firmament of 11 Kuwaiti banks.
While unlikely to repeat last year’s growth levels, which saw net income increase by 25.3 per cent on average thanks in part to bulging interest margins, lower loan impairments and a continued focus on cost efficiencies, this year’s six-month reporting cycle indicates double-digit growth will be repeated for the full year.
National Bank of Kuwait (NBK), the country’s largest lender, reported a 16 per cent increase in first half 2023 profits to KD275.3m ($895.3m), as interest income rose. Total assets in the first half increased by 5.3 per cent to KD36.1bn ($117.4bn).
As NBK chief executive Isam al-Sager noted: “Strong business growth, robust liquidity and prudent levels of asset quality will continue to drive profit growth throughout 2023.”
Robust fundamentals
Improving NPL metrics – already the lowest in the GCC – and solid funding growth are driving improvements for the country’s banks.
The IMF noted in an assessment earlier this year that banks remain well capitalised and liquid — comfortably exceeding prudential regulatory requirements. Last year, the average capital adequacy ratio was 17.3 per cent, above the 12 per cent limit required by the Central Bank of Kuwait (CBK).
NPLs remain low by regional standards, at least in part because Kuwait’s small and medium-sized enterprise (SME) sector is not as vibrant as some other Gulf states, meaning fewer insolvent customers to deal with. The average bank’s customer portfolio comprises Kuwaiti nationals who work in solid government jobs and are considered low-risk customers.
Another supporting factor in terms of asset quality is the solid performance of Kuwait’s real estate sector, which has relatively little exposure to foreign investments – removing the risk of speculation-driven increases affecting the banking market.
On a note of caution, Ashraf Madani, vice-president and senior credit officer at Moody’s Investors Service, says there have been some issues for Kuwaiti banks with foreign operations, in Turkey and Egypt, for instance.
“Foreign currency translations have also impacted capital. So we saw a slight decline in the capital ratio over the past two to three years. But there’s still strong capitalisation,” he says.
“Most banks have large corporate borrowers that have been in the business for quite some time. They have established long-term relationships with the banks, and the portfolio has good seasoning.”
The funding side is also improving, Madani notes, and this year there seems to be higher growth from the deposit side compared to the credit side, which is slightly favourable for the funding of banks.
Growth in the pipeline
Lending to the private sector should remain strong, despite a series of interest hikes that have grown by 250 basis points since the global monetary policy tightening cycle began in 2022.
Lending growth averaged a healthy 7.7 per cent last year, although this year will not be as high.
“This year, our expectation is that the credit growth in the system will be around 3 per cent,” says Madani.
“That’s for two reasons. Number one is that we don’t expect the exceptional growth last year to continue on the consumer side because we’re coming from a high base already in 2022.
“And number two, there are some repayments on the corporate side this year, and these are basically offset by some good project awards on the corporate side. There are some big projects awards happening this year.”
Another push for credit growth will come from a new mortgage law, under which local lenders can provide a housing loan of up to KD140,000 ($455,000) and on which the state will cover the interest for the first KD70,000 ($227,000) on behalf of the borrower.
An increase in project awards this year could technically drive credit higher, but expected tepid growth on the consumer side will likely exert a smothering effect on total loan performance.
On the regulatory side, the Central Bank’s regular review of the adequacy of its financial regulatory perimeter and macroprudential policy toolkit have won the IMF’s plaudits.
The fund said the CBK will continue to regularly stress test the banking system's resilience to emerging financial stability risks, and said the existing blanket guarantee on bank deposits should be gradually replaced with a limited deposit insurance framework to address moral hazard.
Meanwhile, the interest rate cap on commercial loans should be phased out to support efficient risk pricing and credit supply to SMEs.
Though NBK, once the largest GCC bank by assets, has been overtaken in size by the region’s emergent banking behemoths such as the UAE’s First Abu Dhabi Bank and Saudi National Bank, it and other national heavyweights remain active lenders with a keen interest in servicing economic opportunities in Kuwait and beyond.
Big ticket mergers are not in the pipeline this year, but after the tumult of recent years, Kuwaiti lenders will be happy with stable, if unspectacular, growth.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Read the November 2026 MEED Business Review
4 November 2026
-
 UAE economy shows resilience
4 November 2026
-
 Kuwait appoints KPMG for ports strategic plan
4 November 2026
-
 Combined Group signs Kuwait upstream contract
4 November 2026
-
 Qiddiya seeks interest for water infrastructure packages
4 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Read the November 2026 MEED Business Review
4 November 2026
Download / Subscribe / 14-day trial access The GCC projects market continues to show resilience against a deteriorating macroeconomic backdrop, with clients committing capital despite the regional fallout from the US-Iran conflict.
 According to the IMF, every GCC economy except Oman is projected to contract in 2026. Yet government-backed infrastructure spending has cushioned the blow, led by the UAE, where contract awards are up 6.1% year-on-year.
But beneath the headline figures, signs of a slowdown are emerging. Falling residential activity, a retreat in Saudi Arabia’s gigaproject spending and a sharp decline in tendering suggest that the market faces a tougher test as the conflict continues.
Read more in our November issue Agenda feature.
Our 22-page market focus on the UAE examines how state-backed capital, greater freedom to increase oil production following the UAE’s exit from Opec, and continued investment in energy, transport and water infrastructure are helping the country absorb the economic shock of the Iran conflict.
It also looks at how Abu Dhabi is adjusting its diplomatic approach, and the risks that remain for the wider economy.
This month’s industry report turns to project finance, examining how Gulf lenders are reassessing risk amid regional instability, higher costs and tighter credit limits. While infrastructure funding needs remain undiminished, the conflict is changing the way projects are financed, with lenders paying closer attention to physical security, insurance and risk allocation.
The report also examines the slowdown in public-private partnership activity across the Middle East and North Africa, where the value of awards has fallen sharply despite a pipeline of major deals still to come.
We also speak to WSP’s regional president Dean McGrail about the resilience of the Gulf construction market, the shift towards infrastructure investment and the opportunities emerging in aviation.
H&H chairman Shahab Lutfi discusses how the Dubai developer is pressing ahead with contract awards despite rising costs and softer sales, while the UAE Ministry of Energy & Infrastructure’s Mohammed Al-Mansoori explains how the country is strengthening supply-chain resilience and maintaining infrastructure delivery in the face of disruption.
Elsewhere, we examine the global stadium construction market, where annual spending is forecast to jump by 39% in 2027 as governments prepare for major sporting events, and look at the economic consequences of the Strait of Hormuz closure.
We hope our valued subscribers enjoy the November 2026 issue of MEED Business Review.
Must-read sections in the November 2026 issue of MEED Business Review include:
> AGENDA: GCC projects market holds its nerve
> INTERVIEW: Stability holds as project work continues
> INTERVIEW: H&H continues to deliver Dubai projects
INDUSTRY REPORT:
Project finance
> Project financiers hold the line
> PPP activity fades amid regional instability> INTERVIEW: Building resilience into infrastructure delivery
> STADIUMS: Stadium spending set to jump 39% in 2027
> REGIONAL CONFLICT: Hormuz closure wipes out growth in 2026
 > UAE MARKET FOCUS:
> GOVERNMENT: Abu Dhabi mends fences with Riyadh
> ECONOMY: UAE growth holds up as regional risks persist
> BANKING: UAE banks profit as credit growth surges
> UPSTREAM: Adnoc steps up crude expansion
> DOWNSTREAM: Adnoc funnels billions into boosting gas processing
> POWER: Gas-fired projects drive resilience in UAE power sector
> WATER: Tasreef scheme drives UAE water investment
> CONSTRUCTION: State-backed spending cushions UAE construction slowdown
> TRANSPORT: Infrastructure drives UAE growth agenda
> MANUFACTURING: UAE vehicle manufacturing push moves into production> MEED COMMENTS:
> Regional tensions strengthen the case for GCC rail
> Focus turns to the Northern Emirates
> Gulf data centre ambitions face delivery test
> Qatar buys LNG reliability beyond Hormuz> GULF PROJECTS INDEX: Saudi Arabia drives Gulf projects market higher
> SEPTEMBER 2026 CONTRACTS: Middle East contract awards
> ECONOMIC DATA: Data drives regional projects
> OPINION: When football meets politics
> BUSINESS OUTLOOK: Finance, oil and gas, construction, power and water contracts
To see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/21089562/main.gif -
UAE economy shows resilience
4 November 2026
 Commentary
Colin Foreman
EditorState-backed capital is carrying the UAE projects market through the economic shock of the Iran conflict. Government and government-related entities have accounted for $22.4bn of the $34.6bn of contracts awarded in Dubai so far this year, almost two-thirds of the total, according to regional project tracker MEED Projects. Private developers have deferred new launches, and off-plan residential sales in the emirate fell from $9bn in February to $4bn in August.
In Abu Dhabi, state-affiliated developers and cultural agencies are accelerating destination projects on Yas and Saadiyat islands, including the $1.7bn Sphere Abu Dhabi venue.
The energy sector is adding momentum. The UAE’s exit from Opec in May has freed Abu Dhabi National Oil Company (Adnoc) to make greater use of its spare crude capacity, and the company is on course to exceed its 2024 upstream project spending this year. Adnoc Gas has awarded $8.2bn of contracts for the second and third phases of its rich gas development programme.
The $3bn Taweelah C combined-cycle gas turbine plant accounted for most of the $4.17bn of power contracts awarded by early September, while Dubai’s AED30bn ($8.1bn) Tasreef stormwater programme is driving water sector activity.
MEED Projects tracks $103bn of transport schemes at pre-execution stages, including rail links that would give exporters routes that avoid the Strait of Hormuz.
Non-oil activity is also holding up. The UAE purchasing managers’ index compiled by financial information and analytics provider S&P Global reached a 20-month high of 55.3 in September. Net profits at the 10 biggest UAE banks rose 7% to AED47.8bn ($13bn) in the first half, supported by loan growth of 21%.
Meanwhile, Abu Dhabi is repairing relations with Riyadh after a year of friction over Yemen and Sudan. On 8 October, the two countries signed a memorandum of understanding covering power grid interconnection and freight rail.
Risks remain. The Washington-based IMF expects the GCC economy to contract by 3.8% this year, with recovery dependent on shipping through Hormuz returning to normal. US scrutiny of Iran-linked transactions is also tightening compliance demands on UAE banks. That said, there are reasons to be hopeful. The IMF expects the economy to rebound in 2027 with 7.7% GDP growth.
MEED’s November 2026 report on the UAE includes:
> GOVERNMENT: Abu Dhabi mends fences with Riyadh
> ECONOMY: UAE growth holds up as regional risks persist
> BANKING: UAE banks profit as credit growth surges
> UPSTREAM: Adnoc steps up crude expansion
> DOWNSTREAM: Adnoc funnels billions into boosting gas processing
> POWER: Gas-fired projects drive resilience in UAE power sector
> WATER: Tasreef scheme drives UAE water investment
> CONSTRUCTION: State-backed spending cushions UAE construction slowdown
> TRANSPORT: Infrastructure drives UAE growth agenda
> MANUFACTURING: UAE vehicle manufacturing push moves into productionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20947110/main.gif -
Kuwait appoints KPMG for ports strategic plan
4 November 2026
Register for MEED’s 14-day trial access
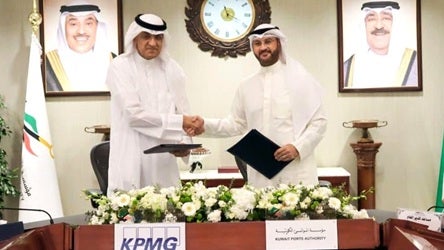
Kuwait Ports Authority (KPA) has appointed the local office of UK-headquartered KPMG to develop its ports strategic plan, which aims to improve the competitiveness, connectivity and performance of Kuwait’s commercial ports.
KPMG will act as lead consultant on the strategic consultancy engagement, with Netherlands-based Haskoning Nederland and local engineering firm Dar Gulf Consult providing engineering consultancy support.
KPMG will consolidate the three consultants’ work into a single strategic plan. It will lead the market, commercial and organisational analysis, as well as develop and implement the strategy.
The scope is split into two workstreams. The first covers strategy development, planning and an implementation framework, including an assessment of KPA’s current market position and performance.
The resulting strategic options and roadmap will be developed into detailed functional plans, supported by key performance indicators, a risk framework and a monitoring plan.
Under the second workstream, KPMG will set up and lead a strategic technical support office for 36 months. The office will provide KPA with strategic oversight, technical advisory services and integrated project management support.
KPA operates Kuwait’s three main commercial ports: Shuwaikh Port, Shuaiba Port and Doha Port.
In line with the New Kuwait Vision 2035 development strategy, KPA is transitioning its operations into high-efficiency smart ports by investing heavily in automated machinery, deeper navigational channels and significant berth capacity expansions.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21106611/main.jpg -
Combined Group signs Kuwait upstream contract
4 November 2026
Register for MEED’s 14-day trial access
Kuwait-headquartered Combined Group Contracting Company has signed a contract to repair and revamp production facilities in West Kuwait, according to a company statement.
State-owned upstream operator Kuwait Oil Company (KOC) awarded the contract, valued at KD9.7m ($31.4m).
The contract has a five-year term.
KOC issued the invitation to bid on 5 October 2025. The initial bid deadline was 4 January 2026, and a pre-tender meeting was scheduled for 4 November 2025.
The contract award to Combined Group was approved on 13 September 2026.
Kuwait’s oil and gas sector is currently in the midst of a major crisis, as disruptions to shipping through the Strait of Hormuz have dramatically reduced exported crude oil volumes.
The disruptions are the result of a regional war that started on 28 February when the US and Israel attacked Iran.
The disruptions to shipping in the Strait of Hormuz are also creating significant challenges for oil and gas construction projects, which normally import equipment and materials through the waterway.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21120792/main.png -
Qiddiya seeks interest for water infrastructure packages
4 November 2026
Register for MEED’s 14-day trial access
Qiddiya Investment Company (QIC) has issued an expression of interest for two water infrastructure packages at Qiddiya City, southwest of Riyadh.
According to a source, the first package covers a wastewater treatment plant with a capacity of 60,000 cubic metres a day (cm/d).
The second package involves a wastewater treatment plant with a capacity of 9,000 cm/d. It will also include a “sizeable” reverse osmosis (RO) facility, a source close to the project told MEED.
The deadline for submissions of interest is 8 November.
The infrastructure package will cater to Saudi Arabia’s 360-square-kilometre Qiddiya entertainment city.
QIC, which is owned by Saudi Arabia’s Public Investment Fund (PIF), is overseeing the development of Qiddiya City, including its supporting utilities infrastructure.
In October 2024, MEED reported exclusively that QIC planned to tender its utilities packages individually under an engineering, procurement and construction model.
QIC had previously planned to procure the infrastructure through a public-private partnership (PPP). However, it cancelled this approach despite receiving two bids for a multi-utility package in 2020.
The original utilities package covered power generation, water desalination, sewage treatment and water transmission networks.
In September 2023, QIC signed infrastructure contracts worth SR2.29bn ($611m) with a joint venture of Saudi Real Estate Infrastructure Company (Binyah) and InfraRoad Contracting.
The contracts covered a wider infrastructure package at Qiddiya’s Resort Core, including roads, utility networks, water storage facilities and pumping stations, as well as the construction of a sewage treatment plant (STP).
Two other major PIF-backed developments, the Red Sea project and Amaala, have each awarded multi-utility packages using a PPP model, while contractors are preparing to bid for two separate wastewater treatment plants for Oxagon, Neom’s industrial cluster.
In September, the utilities system serving Saudi Arabia’s Red Sea tourism destination reached commercial operation, marking the start of a 25-year concession for one of the world’s largest integrated off-grid utilities projects.
The project, known as the Marafiq Red Sea Project or Red Sea Utilities Multi-Utilities Project, includes three seawater RO plants, an STP, a waste management centre and 32,500 refrigeration tonnes of district cooling capacity.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21111446/main.jpg