Kuwait navigates unchartered political territory
29 August 2024

Kuwait’s political situation and its near-term prospects for governance continue to hinge on the dramatic suspension of the nation’s parliament by Emir Sheikh Meshal Al-Ahmad Al-Sabah.
This drastic measure by the country’s leader came in response to a deepening political stagnation in Kuwaiti politics that has seen successive formations of parliament and government deadlocked over the most fundamental of fiscal legislation: approving the budget and raising the debt ceiling.
Underlying these stumbling blocks are allegations of fiscal and budgetary malfeasance levelled by the elected lawmakers in parliament at the ruler-appointed and ruling family-led cabinet.
In recent years, the proceedings in parliament have become increasingly acrimonious, with lawmakers frequently demanding the right to question cabinet members – a demand that has instead often simply resulted in the dissolution of the government.
Kuwait’s political system has often been described as a “democratic experiment”, as it was a first in the GCC to devolve significant legislative authority to a chamber of fairly freely elected representatives.
On 10 May, however, after the fourth election in four years in pursuit of a functioning government resulted in the same rigmarole, the emir triggered the system’s inbuilt circuit breaker for the first time since its establishment and effectively placed the experiment on hold.
Two days later, the emir announced the formation of a new cabinet headed by Sheikh Ahmad Abdullah Al-Sabah as the returning prime minister. The country’s oil, finance and foreign ministers all retained their posts as well, making it a continuity cabinet, but in the absence of parliament.
Officially, the rules allow for the suspension of parliament for up to four years, enabling direct rule by the emir and his cabinet in the interim. Kuwait has thus returned, temporarily, to something of a default setting for the GCC. But it is a dramatic turn of events for Kuwait given the country’s well-worn electoral legacy – even as its other positively regarded attributes, such as a relatively free press, remain intact.
Project revitalisation
The emir’s decision is nevertheless being viewed in many quarters as a potentially positive development, not least in the projects sector. The political deadlock plaguing the country has been a salient problem for contractors in recent years due to the way parliamentary objections have impeded project spending.
Indeed, political disputes over capital expenditure have come close to scuttling Kuwait’s projects sector, which has seen its activity plummet over the past decade, with the country’s $16.5bn in contract awards in 2016 plunging to just $2.6bn in 2019 and averaging less than $4bn in the past five years. Given the parallel $100bn in project completions over the past 10 years, this fall in awards has resulted in a $50bn net decline in the value of projects under execution.
This loss of value from the projects sector has been detrimental to Kuwaiti contractors, who have been looking abroad in increasing numbers for alternative avenues of work. The drop-off in value in the project market has also been even more dramatic in certain industries, including the oil sector, where the total value of active projects fell from $65bn in early 2019 to just over $5bn by early 2023.
The reduction in oil sector projects, where constant work is required to maintain the performance of the infrastructure, is a threat to the main driver of the Kuwaiti economy and government revenues.
Given the country’s limited diversification and the accounting of the oil sector for 60% of Kuwait’s GDP and 90% of government revenue, the potential long-term consequences of the nation’s political dysfunction metastasising into dysfunction in the oil sector are considerable.
It is not surprising then that one of the first things on the agenda since the suspension of parliament has been the revival of oil sector projects – with the country’s Central Agency for Public Tenders now meeting three days a week since July to advance the tendering of major schemes.
Political correction
Political reform is also on the table. In his televised address to the nation on 10 May, the emir stated: “The recent turmoil in the Kuwaiti political scene has reached a stage where we cannot remain silent, so we must take all necessary measures to achieve the best interest of the country and its people.”
The presentation of the challenges facing the country in existential terms underlined the heightened perception that Kuwait was careening towards disaster amid political paralysis, falling oil infrastructure investment and snowballing expenses.
However, regardless of the “unimaginable, unbearable difficulties and impediments”, facing the country, the retaking of direct control by the emir and cabinet is no assurance that the trouble is over. The country still faces stark policy choices, including how to tackle its burgeoning public wage bill, which currently stands at about 30% of the country’s GDP and is only set to grow with rising pay and pensions.
These are costs that Kuwait cannot bear without robust oil sector development, and even that might not be enough. Economic projections have suggested public salaries could make up as much as 75% of the budget within five years, which could rapidly shrink the fiscal space for any other spending.
This is a burgeoning dilemma for the country that cannot be tackled overnight, but with four years of determined and unencumbered course correction, Kuwait could at least develop some more options.
Constitutional amendments could also be unveiled to prevent a return to political paralysis when a parliament re-forms. The ability of the house to override the emir’s veto with a simple majority, as well as to hold votes of no confidence for ministers, are two areas where changes could be made to smooth the political process – for example by requiring a super majority to overturn the emir’s veto or by making the conditions necessary to challenge the confidence in a minister more stringent.
Regardless, what is abundantly clear is that the existing system was not functioning as required – at the most fundamental level – in making basic legislative progress. Everything could now get back on track, but there are ample more “difficulties and impediments” to address, and Kuwait needs fresh solutions.
This month's special report on Kuwait includes:
> GOVERNMENT: Kuwait navigates unchartered political territory
> ECONOMY: Fiscal deficit pushes Kuwait towards reforms
> BANKING: Kuwaiti banks hunt for growth
> OIL & GAS: Kuwait oil project activity doubles
> POWER & WATER: Kuwait utilities battle uncertainty
> CONSTRUCTION: Kuwait construction sector turns corner

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 GCC projects market holds its nerve
1 November 2026
-
 Ashghal tenders Mekeines-Umm Bab link road
30 October 2026
-
-
 Contractors submit Riyadh Expo KSA pavilion bids
30 October 2026
-
 Oman announces $790m industrial investment deals
30 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
GCC projects market holds its nerve
1 November 2026
The war in the Gulf is now inflicting deep damage on the region’s economies. In its October World Economic Outlook, the IMF forecasts contraction in every GCC state except Oman in 2026. Saudi Arabia’s real GDP is projected to shrink by 3.3%, after 4.6% growth in 2025, and the UAE’s by 3.9%, after 6.2% growth.
 The IMF expects Kuwait’s economy to contract by 16.7%, Qatar’s by 15.6% and Bahrain’s by 11.3%, as energy and transport disruption cuts exports. Oman, with routes outside the Strait of Hormuz, is forecast to grow by 4.1%.
The fund has cut its 2026 forecast for the Middle East and Central Asia by 2.2 percentage points since April, to a contraction of 0.3%, citing a longer closure of the strait than it had previously assumed. The revision for Saudi Arabia is 6.4 percentage points. The IMF now assumes the strait will reopen in March 2027, with a return to prewar conditions broadly by October 2027.
There is little sign of an early end to hostilities. On 10 October, a Houthi-attributed strike on a passenger terminal at Riyadh’s King Khalid International Airport killed 12 people and injured 309, according to Saudi Arabia’s General Authority of Civil Aviation. Airport operations were suspended and several international airlines cancelled flights.
Yet the region’s projects market is holding up far better than its economies. Data from MEED Projects shows that contract awards in 2026 have proved resilient, with clients across the GCC continuing to commit capital to new schemes.
The GCC projects market has absorbed almost eight months of conflict better than its economies
Resilient awards
The UAE leads the regional market for a second consecutive year, with the value of contract awards 6.1% higher than in the same period of 2025. Oman and Kuwait are also running ahead of last year’s pace, despite the IMF’s forecast that Kuwait’s economy will contract by about a sixth.
Saudi Arabia has awarded $68.8bn of contracts so far this year, 13% less than in the same period of 2025. Given that the kingdom has been the main target of the Houthi campaign, and was already revising its spending priorities before the conflict, the decline is modest.
The comparison is against a high base. The past three years have seen unprecedented GCC capital expenditure, supported by higher oil prices, residential demand and national vision programmes. More than three quarters has been concentrated in Saudi Arabia and the UAE.
The gap between economic output and project spending reflects the nature of the projects market. Governments and state-linked entities can sustain capital budgets through a downturn using reserves and borrowing. GDP contraction, by contrast, reflects lost oil and gas exports, tourism and trade.
The UAE’s performance this year has been driven by the gas and transport sectors, which have recorded the strongest growth. Construction, the country’s largest sector, has declined as the real estate market has cooled.
Abu Dhabi has been the standout performer. Contract awards in the capital are up 35% on the same period of last year, with growth across the construction, gas, oil and transport sectors.
Public spending is a central reason for that resilience. Fitch Ratings expects Abu Dhabi’s spending to rise by 19% this year, equivalent to 3.7% of GDP, to support the non-oil economy. Data from the Central Bank of the UAE shows consolidated government capital expenditure rose to AED18.6bn ($5.1bn) in Q1 2026 from
AED2bn in Q1 2025.Fitch expects UAE infrastructure and government-related entity capital spending to rise significantly in 2026 and 2027, both to strengthen resilience against future conflicts and stimulate the economy. Emirates have already accelerated tendering on several projects.
Transport remains a priority. Plans include further sections of the national passenger rail network, a high-speed rail link between Dubai and Abu Dhabi, a light rail system in Abu Dhabi and the Dubai Metro Gold Line. The $35bn expansion of Al-Maktoum International airport in Dubai is moving towards delivery with the award of the first major construction packages.
Economic headwinds
Both the IMF and Fitch expect a strong rebound once the strait reopens. The IMF forecasts 2027 growth of 7.7% in the UAE, 7.9% in Saudi Arabia, 18.8% in Qatar and 17.1% in Kuwait. Fitch forecasts UAE non-oil growth of 6.1% next year. Paul Gamble, senior director at Fitch, cautioned that prolonged insecurity “will call into question logistical advantages” that underpin the UAE’s growth model.
Beneath the headline award totals, there are warning signs. Regional contract awards performed well between March and June, but the value of work awarded in recent months has dropped sharply compared with the same months of 2025. According to MEED Projects, the main cause is a fall in the number of tenders being issued, particularly in real estate.
The timing is significant. The strong period included the April ceasefire, when clients appear to have pressed ahead expecting a short conflict. Tendering slowed as hostilities resumed. In July, Iranian attacks reached Bahrain, Kuwait, Qatar, Jordan and Oman, while Houthi escalation against Saudi Arabia began.
The pattern suggests conflict fatigue may be setting in, with clients deferring projects amid a war with no clear end date. As tendering is a leading indicator, the impact on awards is likely to become more visible in coming months.
In Saudi Arabia, monthly performance has been mixed as the market adjusts to revised spending priorities and the regional conflict. Most sectors are up on last year, with the exception of power and water, which has struggled in 2026, possibly as a result of overbuilding in the past three years. The kingdom’s gigaprojects have continued their retreat. Awards peaked at $31.7bn in 2023 and fell to $14.4bn in 2025. The total so far in 2026 is $9.4bn, most of it for work at Qiddiya, Diriyah and Rua Al-Madinah.
The GCC has more than $3.4tn of known, planned and unawarded projects over the next 10 to 15 years
Dubai slowdown
The clearest signal of the conflict’s impact on the projects market comes from Dubai. The emirate’s market performed strongly until May. Since then, activity has been subdued, and contract awards for the year to date are 0.6% lower than in the same period of 2025.
The main cause is a decline in residential contract awards. Data from Bayut and the Dubai Land Department shows a marked fall in the value of off-plan sales since late February, when the war began. Residential construction awards have fallen in step, with no sign of the time lag that would normally be expected.
Third-quarter figures from Savills confirm the trend. Residential transactions fell 38% year on year to 34,500, and transaction value dropped 46% to AED70.8bn ($19.3bn) from AED132.2bn. The decline was concentrated in the off-plan segment, where value fell to AED45.7bn in Q3 from AED61.3bn in Q2, while ready-market value rose to AED25.1bn from AED21.3bn.
Developers have sharply reduced new launches. Savills recorded about 5,000 units launched in Q3, taking the total for the year to date to about 50,000, roughly 64% below the same period of 2025. Fewer launches mean fewer construction contracts, which explains why residential awards have fallen so quickly. More than 525,000 units are scheduled for delivery between 2027 and 2030, which Fitch says could add pressure to a sector accounting for 8% of non-oil GDP if population growth weakens.
Escaping Hormuz
The conflict is also generating new project demand. Saudi Arabia is prioritising ports and transport infrastructure on the Red Sea coast, along with new pipelines to the Red Sea and to Oman. The UAE is developing ports and transport links to the east coast and Oman, and additional pipelines to Fujairah. Fitch anticipates new and expanded road, rail, pipeline and port infrastructure in Oman and Saudi Arabia as GCC states seek routes that bypass the strait.
The IMF’s forecasts underline the value of those routes. It describes Saudi Arabia as “somewhat less affected” than its neighbours because of its more diversified export routes, while Oman is the only GCC state forecast to grow this year. Houthi strikes on Aramco facilities in Yanbu in September show that Red Sea infrastructure is not beyond reach, however. Defence spending is rising in both Saudi Arabia and the UAE, and repair and rehabilitation work will add to the pipeline once hostilities end.
The long-term fundamentals remain strong: the GCC has more than $3.4tn of known, planned and unawarded projects over the next 10 to 15 years, about half of it in Saudi Arabia. Many of the kingdom’s priorities are tied to fixed dates, with Riyadh hosting the World Expo in 2030 and Saudi Arabia hosting the Fifa World Cup in 2034.
The capacity to fund this pipeline depends on oil revenues. MEED’s assessment is that crude prices must remain above $70-$80 a barrel for spending levels to be maintained. With exports through Hormuz disrupted, the volume of oil Gulf producers can move to market matters as much as the price.
The GCC projects market has absorbed almost eight months of conflict better than its economies. The question for the final quarter is whether the slowdown in tendering is a temporary pause or the start of a sustained retreat. If the IMF’s assumption of a March 2027 reopening of the strait holds, clients will be setting their 2027 budgets with a rebound in sight. If it slips, the resilience of contract awards will face a sterner test.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21078685/main.gif -
Ashghal tenders Mekeines-Umm Bab link road
30 October 2026
Qatar’s Public Works Authority (Ashghal) has tendered a contract for the design and construction of the Mekeines to Umm Bab Link Road and associated infrastructure.
The tender was issued on 29 October, with a bid submission deadline of 22 December.
The scope comprises:
- Highway works, including main carriageways, access roads, grade-separated ramps, junctions and tie-ins to existing networks
- Dedicated non-motorised user facilities, footpaths and shared-use cycle paths
- Structural installations, including camel underpasses, a QatarEnergy culvert and gateway monumentation
- Extensive dry and wet utilities, encompassing Kahramaa potable water and electrical transmission networks, surface water drainage, street lighting and dedicated communication networks for Ooredoo, the Qatar National Broadband Network and the Qatar Armed Forces
Under the scope of work, the appointed contractor will execute full design verification and turnkey construction under Ashghal’s standard Building and Engineering Design and Build General Conditions of Contract (2018 Edition) on a lump-sum basis. Engineering subconsultants must hold Grade 1 or International classification with the Ministry of Municipality across civil, architectural, mechanical and electrical engineering disciplines.
The contract stipulates an execution period of 1,260 calendar days (3.5 years) from the commencement date, followed by a 400-day maintenance liability period.
The project is open to local and international contractors classified as Grade A in roads specialisation by Qatar’s Ministry of Finance (MoF).
Foreign firms may participate independently or within a joint venture, provided the joint venture leader holds the requisite classification, by registering through the MoF e-procurement portal with attested equivalent certification from their home countries.
The planned corridor is located within Al-Rayyan Municipality across Zones 82 to 84 in the Al-Sheehaniya area.
At its eastern end, the link road begins about 40 kilometres southwest of central Doha, tying into the Salwa Road Interchange 42. At the western terminus, it connects to the roundabout adjacent to Umm Bab on the Abu Samra to Dukhan road (Route 39).
The link road serves as a critical logistics corridor connecting western settlements, residential districts and industrial installations, including concession areas operated by QatarEnergy.
The western 7.5km of the alignment passes directly through the QatarEnergy District, where the corridor runs parallel to active oil and gas pipelines and includes a designated gateway monument.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21041383/main.gif -
Contractors prepare bids for Petro Rabigh bottom-of-the-barrel project
30 October 2026
Contractors are preparing proposals for Saudi Arabia’s Rabigh Refining & Petrochemical Company (Petro Rabigh) for a major project to increase output and improve the efficiency of its integrated refining and petrochemicals complex in Rabigh, on the kingdom’s Red Sea coast.
Petro Rabigh’s downstream complex, which is majority-owned by Saudi Aramco, includes a topping refinery with a 340,000-barrel-a-day (b/d) crude-distillation unit, a 47,000 b/d hydrotreater, a 12 million-cubic-feet-a-day hydrogen plant, a 75,000 b/d naphtha Merox unit and a 60,000 b/d kerosene Merox unit. The complex also includes supporting utilities, product tankage and a marine terminal.
The main objective of the bottom-of-the-barrel project is to convert low-value, high-sulphur fuel oil and heavy-residue streams – which account for about 20% to 22% of refinery output – into higher-value, cleaner products, including diesel and lighter distillates.
Petro Rabigh aims to achieve residue-conversion capacity of about 64,000 to 75,000 b/d by adding integrated fuel-oil upgrading and diesel-treatment units.
The company issued the main tender for engineering, procurement and construction (EPC) works earlier this year. Contractors have until 19 November to submit proposals, sources told MEED.
The following companies are understood to be among those bidding for the project:
- CTCI Corporation (Taiwan)
- JGC Corporation (Japan)
- Larsen & Toubro (India) / Technip Energies (France)
- Tecnicas Reunidas (Spain)
The overall scope of work on the project covers the construction of the following units:
- A light-naphtha isomerisation unit
- A deasphalting and dewaxing unit
- An ebullated-bed processing unit
- A sulphur block, comprising sulphur-recovery, acid-gas-removal, sour-water-stripping and sulphur-forming units
- Sales-gas allocation facilities and associated pipeline works
- Utilities outside battery limits
- Auxiliary piping modifications
- Utility and hydrocarbon tie-ins
Petro Rabigh appointed Australia-headquartered Worley last year to carry out front-end engineering and design (feed) work for the bottom-of-the-barrel project.
MEED also reported that Petro Rabigh appointed Worley to provide engineering and project-management consultancy (PMC) services for the project in the first quarter of this year.
Under the contract, Worley will carry out engineering studies and PMC functions. It will also support the development of cost estimates, project-specific execution procedures and technical procedures in line with Saudi Aramco guidelines. The work covers both the design-basis scoping-paper stage and the subsequent feed stage.
Petro Rabigh will draw on Worley’s expertise in design, procurement and processing technologies, including light-naphtha isomerisation; vacuum-residue processing through deasphalting and dewaxing; an ebullated-bed configuration integrated with the diesel-hydrotreating section; and unconverted-oil hydrotreatment.
Worley recently confirmed its contract award from Petro Rabigh, saying it will deliver engineering, project management, procurement support and related consultancy services for projects across its client’s portfolio.
The scope includes developing design-basis documents, conducting technical evaluations, preparing cost estimates, supporting feed tender packages and providing detailed engineering and execution-phase support as projects advance through development and delivery.
The services will support the evaluation and development of potential new facilities and infrastructure across the complex, including process units, utilities, sulphur recovery facilities and associated infrastructure.
“The work will help Petro Rabigh advance future projects aimed at enhancing the long-term value and performance of its refining and petrochemicals operations,” Worley said in a statement on 28 October.
Separately, Petro Rabigh awarded US-based KBR a 10-year maintenance contract in February to support its polymer plants in Rabigh.
KBR’s Technology Led Industrial Solutions business line will execute the operations and maintenance contract, sources told MEED. The business operates within the Houston-headquartered company’s Technology Solutions portfolio.
In March 2024, Petro Rabigh also awarded KBR a similar five-year asset-condition-monitoring contract. Under that programme, KBR is providing predictive-maintenance services at Petro Rabigh’s main plant.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21032785/main.jpg -
Contractors submit Riyadh Expo KSA pavilion bids
30 October 2026
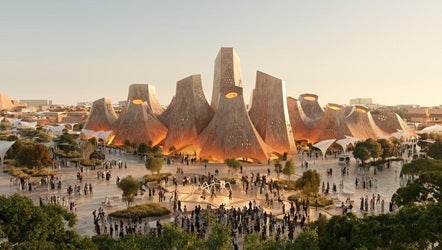
Contractors submitted bids on 25 October for a contract to design and build the Saudi Arabia pavilion at the Expo 2030 Riyadh site.
The facility will include exhibition halls, VIP and protocol areas, event and performance spaces, meeting rooms, food and retail outlets, and back-of-house facilities.
The pavilion will host exhibitions, cultural and commercial showcases and official events throughout the six-month expo.
External public realm works are also included.
Expo 2030 Riyadh Company (ERC), tasked with delivering the Expo 2030 Riyadh venue, issued the main tender on 19 May, as MEED exclusively reported.
Earlier this week, ERC appointed UK-based Mace as procurement advisory consultant for Expo 2030 Riyadh, supporting procurement activities across the programme.
Under the appointment, Mace will provide procurement services and advise on the management and delivery of procurement activities, with the aim of supporting the expo’s wider programme objectives.
Expo 2030 Riyadh will run from October 2030 to March 2031 with the theme Foresight for Tomorrow, with host authorities projecting approximately 42 million visits.
The masterplan covers 6 square kilometres, making it one of the largest sites ever designated for a World Expo event.
Situated north of the Saudi capital, the site is located near the future King Salman International airport and will provide direct access to Riyadh landmarks.
The Public Investment Fund, Saudi Arabia’s sovereign wealth vehicle, launched Expo 2030 Riyadh Company – a wholly owned subsidiary – in June 2025 to build and operate facilities for Expo 2030.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21031590/main.jpg -
Oman announces $790m industrial investment deals
30 October 2026
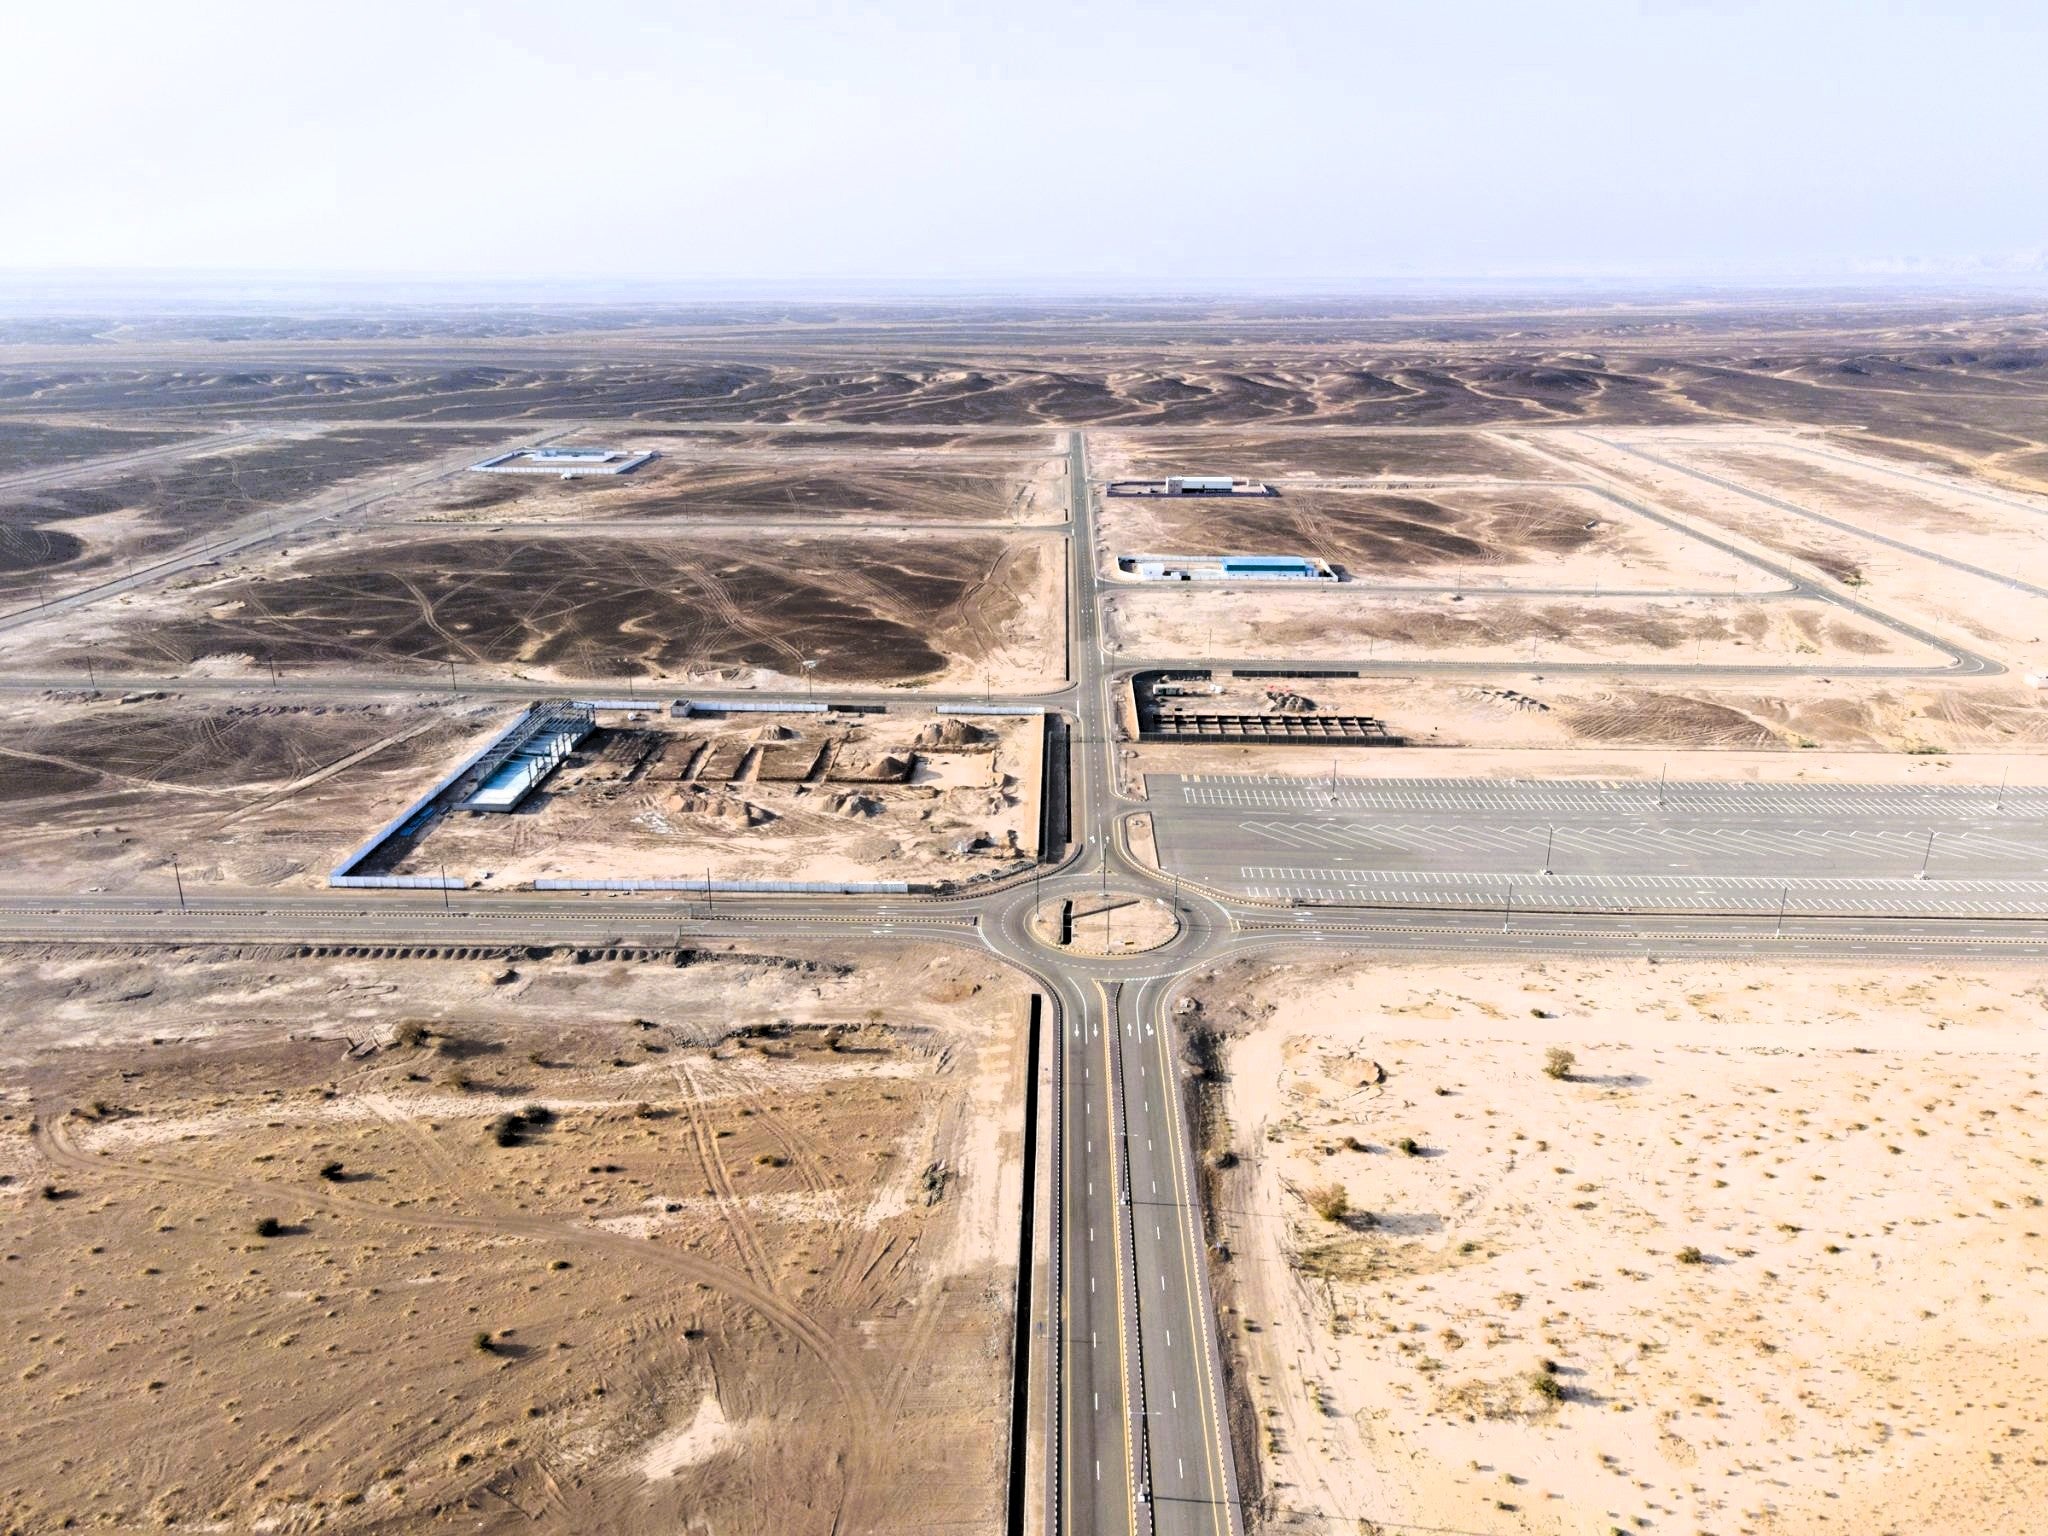
Oman’s Public Authority for Special Economic Zones and Free Zones has signed 28 investment agreements worth more than RO304m ($790m) for new projects and expansions across the country’s special economic zones, free zones and industrial cities.
The agreements cover more than 2 million square metres (sq m) of land and span industrial manufacturing, food production, logistics, recycling and commercial activities.
About $383.6m of the investment has been allocated to industrial cities operated by the Public Establishment for Industrial Estates (Madayn). Sohar Free Zone accounted for $152m, followed by the Special Economic Zone at Duqm (Sezad) with $143.1m, Salalah Free Zone with $85.6m and Khazaen Economic City with more than $27m.
The projects are expected to support Oman’s efforts to diversify its economy, expand industrial production and attract private investment in line with Oman Vision 2040.
Investment deals
In Sohar Industrial City, Atlas Steel will invest more than $291.1m in a plant producing iron and steel products on a site of about 440,000 sq m.
Fujian Mancheng Industries & Investment will invest $52m in a ceramics facility covering more than 241,000 sq m. Other investments in Madayn’s industrial cities include an $18.2m phosphate and nitrogen fertiliser plant planned by Gulf Company for Organic and Biological Fertilisers in Raysut, as well as projects involving structural metal products, paper and corrugated cardboard, and oil and gas equipment and services in Raysut, Ibri and Nizwa.
In Sohar Free Zone, Sohar Automotive & Advanced Industries Company will invest $98.8m in an automobile assembly complex covering 317,000 sq m. The complex aims to attract vehicle manufacturers, automotive supply-chain companies and advanced-manufacturing businesses.
Voltamp High Voltage Transformers has announced a $39m investment in a plant that will produce power and electrical-distribution transformers for regional and international markets.
Lalan Middle East will invest a further $3.9m to expand its medical-device manufacturing facility.
ALSO READ: Oman’s Madayn prepares $637m investment drive
In Sezad, Al-Jazir Feed Plant will invest $104m in a shrimp-feed facility to support an integrated shrimp-farming project.
In Salalah Free Zone, Al-Nawras Industries will invest $50m in a steel-structures manufacturing facility, while Integrated Gypsum Company will invest $20m in gypsum-products production. Marai Dhofar will invest $15.6m in the production of Italian cheeses and other dairy products.
Projects in Khazaen Economic City include a plant by Aleemit International Services to manufacture electric-vehicle chargers and components, with an investment of more than $8.8m, and a $6.5m facility by Joger Modular Building Technologies to produce precast-concrete building components.
Additional investments in Khazaen include construction materials, ready-mix concrete, industrial units, logistics facilities and warehouses.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21016368/main.jpg