Iraq hits the spend button
11 May 2023
 MEED's latest coverage on Iraq includes:
> GOVERNMENT: Sudani makes fitful progress as Iraq's premier
> POWER: Iraq power projects make headway
> UPSTREAM DEVELOPERS: No place like Iraq for international oil firms
> CHEMICALS: Iraq continues technical studies for $8bn chemical project
> SOLAR: Total continues 1GW Iraq solar talks
> TRANSPORT: Baghdad approves funds for metro and airport projects

After a year of turmoil, Iraq has found itself in a better place economically in 2023, with an improved fiscal and external position on the back of high oil prices and production and two years of budget surpluses.
That is the good news. Analysts fear that this relative strength may lead the government into dangerous territory. A 2023 budget submitted to the Council of Representatives amounts to ID199tn ($153bn) of spending – an unprecedented fiscal programme for Iraq, even if oil revenues look flush.
“Iraq remains vulnerable to swings in oil prices, especially given spending pressures, the difficulty of passing meaningful budget reforms and the shallowness of domestic financing options,” says Toby Iles, head of Middle East and Africa sovereign ratings at Fitch Ratings.
“The proposed budget for 2023 pencils in large spending increases, including for sticky items such as salaries. This would increase Iraq’s vulnerability to oil price volatility.”
Previous episodes of low oil prices, in 2015-16 and 2020, quickly led to financing challenges and recourse to central bank borrowing, notes Iles.
The last time Iraq attempted to push through reforms was after the 2020 collapse in oil prices. But the recovery of prices, together with other factors, removed the immediate pressure for change and snuffed out these attempts. “One could argue that it was a wasted crisis,” says Iles.
Most of the budget is current spending – about three-quarters of it, leaving investment spending at ID49.5tn ($38bn). The budget anticipates a sizeable deficit of ID117.3tn ($89bn).
The deficit would be financed by a mix of funding from the Ministry of Finance’s account at the Central Bank of Iraq and foreign financing of investment projects. This would necessitate domestic borrowing of ID31.5tn ($24bn), according to an analysis by Ahmed Tabaqchali, chief strategist of the AFC Iraq Fund.
Cleared path for spending
The Iraqi authorities’ thinking is that now the political logjams of recent years have, for the most part, been removed, the timing is ripe to open the purse strings.
“They are sitting on $115bn of sovereign reserves, which they haven’t been able to spend for a couple of years,” says Michael Knights, a fellow at the Washington Institute for Near East Policy.
“And now they’ve got a fully empowered government. Soon they’re going to have a fully empowered budget. So they see it as time to splurge all the oil income that’s been built up.”
There is a logic to this. Yet the sheer scale of the financing programme is the issue here. The $153bn budget is one and a half times the last authorised budget in 2021, says Knights.
And if the budget is approved as part of a three-year programme – which remains an option – it leaves the state finances particularly vulnerable should oil prices slip.
“If you play out the numbers, you can see that if they spend at these record high levels for three years, they’ll wipe out the majority of their sovereign reserves. And they’ll be down to very close to import cover levels,” says Knights.
One particular concern is that the government intends to increase the size of the public sector by bringing hundreds of thousands of civil servants on board and paying them more. Public sector salaries and pensions are projected to account for 41 per cent of operating expenditures, according to Tabaqchali’s analysis.
In Knights’ view, this approach falls under “out populist-ing the populists, keeping people happy while the government cements its control over the military, the judiciary and intelligence services”.
Risk-fraught gambit
It may still be risky, given that Iraq struggled with the last major oil price drop in 2020. Having to cope then with the degree of public sector fixed expenses, it could be much harder to carry this off now.
Iraq’s single commodity dependence is more acute than other Middle East and North Africa (Mena) oil exporters. Oil revenue accounts for almost all of the government’s revenue and export revenue.
“This high commodity dependence is the key vulnerability, while weak governance and political risk undermine prospects for a stronger non-oil economy,” says Iles.
The undeveloped banking sector is also an important weakness, hampering non-oil development and limiting government financing options during times of fiscal deficit.
“Buoyant oil prices have improved many of Iraq’s sovereign credit metrics, but the absence of structural, economic or fiscal reforms and persistence of political risk constrain the rating (B-),” says Iles.
There will be positives that will emerge from the substantive spending programme. For one thing, there will be a substantial liquidity boost that will drive economic growth. It will also help insulate the government against protests.
For a country that, in the words of the World Bank, has suffered from a combination of corruption, weak state institutions and patronage – leaving 9 million Iraqis living below the poverty line and unemployment as high as 14 per cent – this spending will come as a soothing balm.
Currency crisis averted
Another plus is that the country’s currency crisis of previous months, which led to a shortage of dollars, appears to have been contained.
“The dollar shortages that we have seen in Iraq since late 2022 reflect governance issues and political risk, rather than any fundamental economic imbalances. The central bank’s foreign reserves are at record high levels,” says Iles.
The constraints on FX supply came from long-standing concerns about the ultimate recipients and uses of FX sold via the central bank’s daily auctions. However, notes Iles, now there are higher volumes again in the central bank’s daily auctions and the premium of the unofficial exchange rate over the official rate has narrowed to some extent, reflecting gradual adaptation to the central bank’s new procedural requirements.
If more robust and transparent procedure bed in and normalise, this will have ultimately been positive.
And yet, if the 2023 budget gets passed and Iraq commits itself to a highly expansionary three-year fiscal cycle, fresh vulnerabilities will be baked into the Iraqi economic system that could store up troubles for later generations of Iraqis to deal with. The clock is ticking.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Borouge puts butene-1 expansion project on hold
16 November 2026
-
 Contractor wins Saudi Energy substation deal
16 November 2026
-
 WEBINAR: End-of-Year Mena Market Review
13 November 2026
-
 Saudi Arabia tenders World Cup stadiums upgrade works
13 November 2026
-
 Syntys breaks ground on 20MW Qatar data centre
13 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
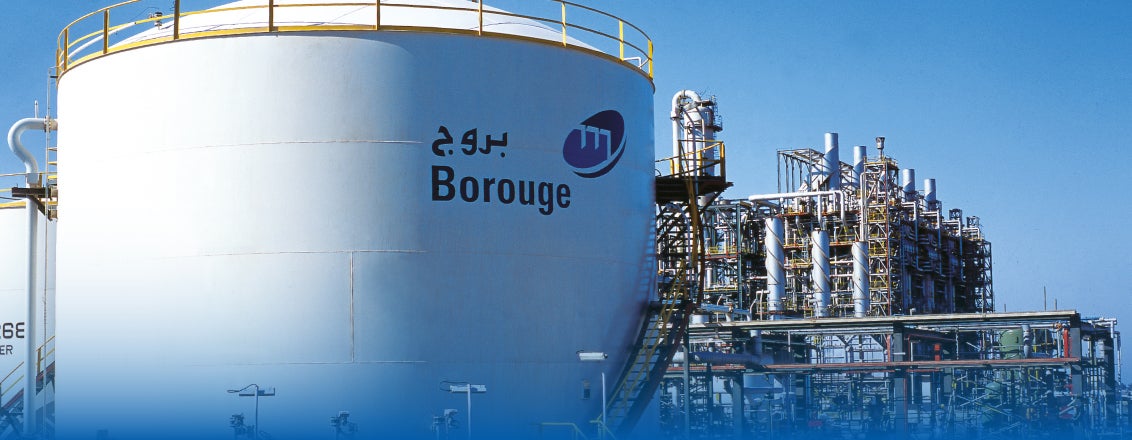
Borouge puts butene-1 expansion project on hold
16 November 2026
Abu Dhabi petrochemicals producer Borouge, now part of Austria-headquartered Borouge International, is said to have put on hold a project to increase butene-1 production from the olefins conversion unit (OCU) at its Borouge 2 facility in Ruwais Industrial City.
Under the proposed project, Borouge planned to produce 60,000 tonnes a year (t/y) of butene-1 from the existing fractionator column while limiting propylene production from the OCU to 500,000 t/y.
The company intended to achieve this by adding co-monomer production technology and selective hydrogenation units, while retaining the capability to run the unit at its original design capacity of 752,000 t/y of propylene and 39,000 t/y of butene-1. The scope also entailed expanding butene-1 storage capacity by converting existing N1 mixed-butane spheres into dedicated butene-1 units.
According to sources, Borouge informed contractors in the weeks after receiving bids that it had decided to shelve the tender.
Contractors submitted technical bids for the engineering, procurement and construction (EPC) package by 1 September 2025, following several extensions to the original 23 June deadline. Borouge had initially released an advanced tender notice in May last year, followed by the main EPC tender on 4 June, and hosted a site visit for bidders on 25 June.
Contractors understood to have submitted bids include:
- Galfar Emirates (UAE subsidiary of Oman’s Galfar Engineering & Construction)
- Target Engineering Construction (UAE)
US-based Lummus Technology was previously awarded the contract to provide the process design package for the new co-monomer production unit as the OCU licensor. Lummus sub-contracted the extended process design package and basic engineering works to South Korea’s Samsung E&A. Borouge had targeted an EPC contract award in the first quarter of 2026.
Butene-1 is a colourless gas primarily used as a co-monomer in the production of high-grade polyethylenes and poly(1-butene), serving end markets such as specialty films, bags and food packaging.
ALSO READ: Borouge prepares to tender construction works for ethane cracker expansion
Borouge International was formed through the combination of Adnoc Group and OMV’s shareholdings in Borouge and Austria-based Borealis, alongside the acquisition of Canada-based Nova Chemicals. In July, Adnoc announced it would transfer its holding in Borouge International to its global investment arm, XRG.
Borouge began operations in 2001 with 450,000 t/y of polyethylene capacity. The Borouge 2 and Borouge 3 expansions raised overall capacity to 2 million t/y in 2010 and 4.5 million t/y in 2014, respectively. Once the Borouge 4 expansion is commissioned, total production capacity will increase from 5 million t/y to 6.4 million t/y, creating the world’s largest single-site polyolefins facility.
Borouge 4 will add two polyethylene units with a combined capacity of 1.4 million t/y (700,000 t/y each) based on Borealis’s third-generation Borstar technology, supplied by a 1.5 million t/y ethane cracker and associated derivative units.
ALSO READ: Borouge restores Ruwais complex after Iranian attacks
https://image.digitalinsightresearch.in/uploads/NewsArticle/21443754/main.jpg -
Contractor wins Saudi Energy substation deal
16 November 2026
Local firm Alfanar Projects has signed a contract with Saudi Energy, formerly Saudi Electricity Company, to build a 115/13.8kV substation in Al-Aqiq, Al-Bahah province, a source confirmed to MEED.
The station will receive electricity at 115kV and step it down to 13.8kV for local distribution. The scope of work includes site preparation, civil works, substation buildings and foundations, and the supply and installation of power transformers and associated electrical equipment.
Seventeen firms submitted bids for the project in May. The bidders included:
- Al-Babtain Contracting
- Al-Gihaz Holding
- Al-Haider Company
- Alfanar Projects
- Cepco
- Energy & Infrastructure Company (Eico)
- Expertise Contracting
- Haif Company
- JAL International
- Maetel Saudi Arabia Construction Company
- Mohammed Al-Ojaimi Group
- Nesma Infrastructure & Technology
- Nour Energy Company
- PA Cost International
- Sama Energy
- Saudi Projects & Supplies Company
- Tareg Al-Jaafari Contracting Establishment
According to regional project tracker MEED Projects, AlFanar Projects had won up to eight awards for substation projects this year, prior to the Al-Aqiq award.
The largest is a contract worth more than SR122m ($32.5m) to construct a 132/13.8kV substation for the Expo 2030 Riyadh site.
The firm was one of four contractors selected by Saudi Energy to deliver electricity infrastructure for the site, MEED reported in August.
Recent contracts include the 380kV Tumair PV substation (#9127), the Busita-C 132/33kV substation, the 132/13.8kV substation north of Al-Kharj (#8721) and the Al-Sahafa 132/13.8kV new substation (#8316).
Saudi Energy has tendered several other 380kV substations and associated transmission lines this year, including projects serving planned solar and wind developments in the kingdom’s central, western and southern regions.
Earlier, in November, MEED exclusively reported that China’s TBEA Shandong Luneng Taishan Cable Company (TBEA) and Egypt’s Elsewedy had submitted the lowest bids for two substation projects in Riyadh Province, estimated to cost a combined $100m.
The tenders for the Thadeq PV and Qiddiya 2 bulk supply points were issued earlier this year, with bids submitted in August and November, respectively.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21443095/main.jpg -
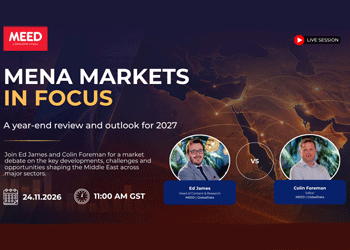
WEBINAR: End-of-Year Mena Market Review
13 November 2026
Webinar: The big questions shaping the Gulf market. You decide what gets debated.
Tuesday 24 November 2026 | 11:00 AM GST | Register now
What makes this session particularly interesting is that the audience gets to decide the agenda. Registrants can vote for the topics they’d like Ed and Colin to debate, with the most popular questions forming the final shortlist for the live session.
Topics in the ballot:
- Is the Gulf trying to build too much, too quickly?
- Saudi Arabia or the UAE: where would you place your next big bet?
- Are gigaprojects the best use of public money?
- Who is really responsible when projects go wrong?
- Should the lowest-price tender become a thing of the past?
- Can private capital take over from the government in financing infrastructure and diversification?
- Is the Gulf’s AI and data centre boom a smart bet or the next overbuilding risk?
- Should the Gulf double down on hydrocarbons to fund diversification?
- Is localisation strengthening the economy or making delivery harder?
- Are Gulf countries building complementary economies or competing for the same customers?
The session will also feature live audience polling and Q&A, giving attendees an opportunity to share their views.
Hosted by:
Edward James, head of content and analysis at MEED
 A well-known and respected thought leader in Mena affairs, Edward James has been with MEED for more than 19 years, working as a researcher, consultant and content director. Today, he heads up all content and research produced by the MEED group. His specific areas of expertise are construction, hydrocarbons, power and water, and the petrochemicals market. He is considered one of the world’s foremost experts on the Mena projects market. He is a regular guest commentator on Middle East issues for news channels such as the BBC, CNN and ABC News and is a regular speaker at events in the region.
Colin Foreman, editor of MEED
 Colin Foreman is editor and a specialist construction journalist for news and analysis on MEED.com and the MEED Business Review magazine. He has been reporting on the region since 2003, specialising in the construction sector and its impact on the broader economy. He has reported exclusively on a wide range of projects across the region including Dubai Metro, the Burj Khalifa, Jeddah Airport, Doha Metro, Hamad International airport and Yas Island. Before joining MEED, Colin reported on the construction sector in Hong Kong.https://image.digitalinsightresearch.in/uploads/NewsArticle/21380319/main.gif
-
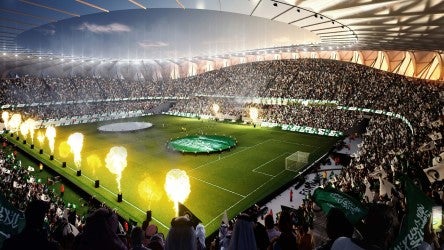
Saudi Arabia tenders World Cup stadiums upgrade works
13 November 2026
Saudi Arabia's Sport Ministry has tendered contracts for upgrade works on two stadiums that will host games for Fifa World Cup 2034.
The two tenders cover upgrade works on Prince Faisal bin Fahad (PFBF) Stadium, located in Riyadh, and King Khalid University Stadium in Abha.
The deadline for bid submissions is 22 November.
PFBF Stadium is located in the northern section of King Abdullah Park in the Al-Malaz area of Riyadh. It will have a seating capacity of about 47,000 spectators.
It will host the Round of 32 games for the Fifa World Cup in 2034.
The project was floated as a public-private partnership under a design, build, finance, operate and maintain model last year, but will proceed on a conventional engineering, procurement and construction basis.
King Khalid University Stadium is expected to be upgraded to have over 45,400 seats. It will host the tournament's Round of 16 games.
The stadium is located in the southeast of the city of Abha, in Asir Province.
Saudi stadium plans
In August 2024, MEED reported that Saudi Arabia planned to build 11 stadiums and refurbish four existing venues for the 2034 tournament. Eight venues will be located in Riyadh, four in Jeddah, and one each in Al-Khobar, Abha and Neom.
An additional 10 cities will host team base camps: Al-Baha, Jazan, Taif, Medina, AlUla, Umluj, Tabuk, Hail, Al-Ahsa and Buraidah. Across the kingdom, organisers plan to deploy 134 training sites, comprising 61 existing facilities and 73 new builds.
Saudi Arabia was officially selected to host the Fifa World Cup 2034 tournament during an online convention of member associations at the Fifa Congress on 11 December 2024.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21379026/main.jpg -
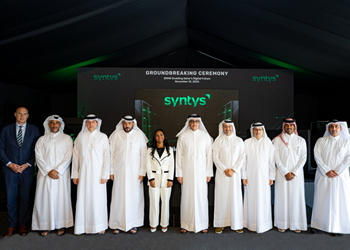
Syntys breaks ground on 20MW Qatar data centre
13 November 2026
Register for MEED’s 14-day trial access
Qatari data centre developer Syntys has broken ground on a 20MW facility to support hyperscale, cloud, artificial intelligence (AI) and advanced computing deployments.
The groundbreaking ceremony took place on 12 November. It was attended by Qatar’s Communications & Information Technology Minister, Mohammed bin Ali bin Mohammed Al-Mannai, along with representatives from Ooredoo Group, Microsoft, Google, Kahramaa, the National Cyber Security Agency, Qatar Free Zones Authority and local banks.
Syntys said the facility is being developed on an existing company campus, where power, fibre connectivity and an operational team are already in place. The company has yet to disclose the project value or planned completion date.
The facility is designed to meet Tier 3 requirements and accommodate a range of rack densities, including higher-density configurations for graphics processing unit (GPU)-based AI and high-performance computing workloads.
It will operate as a carrier-neutral facility, allowing customers to select connectivity providers and establish network resilience in line with their own technical and operational requirements.
The project forms part of Syntys’ strategy to expand its Qatar platform through acquisitions and new development. Earlier this year, the company acquired QData QFZ, adding two operational, Tier 3-compliant, carrier-neutral facilities to its portfolio.
Syntys now owns and operates four campuses in Qatar, allowing customers to establish primary and disaster-recovery environments at separate in-country locations.
The company also designs and operates the facilities supporting Ooredoo’s sovereign AI cloud, which uses Nvidia Hopper GPUs.
The development comes as Qatar implements its Digital Agenda 2030, which identifies digital infrastructure as one of six strategic pillars and targets about QR40bn ($11bn) in economic impact by 2030.
The data centre is expected to support the growth of in-country digital services and enable sensitive workloads to remain within Qatar’s national borders.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21378257/main1028.png