Iraq economic revival faces headwinds
10 May 2024

The ambitious new $17bn Iraq Development Road project, linking Basra to Turkiye’s Mersin port, puts the country’s economic trajectory on a long-term geopolitical setting that will aim to take full advantage of Iraq’s position as a key link in trade routes between Asia and the Mediterranean.
But before this vaunted plan takes root, Prime Minister Shia Al Sudani’s government faces a host of knotty economic challenges, not least a challenging fiscal position aggravated by the expansionary budget announced in 2023.
Lack of parliamentary consent has largely insulated the country from the negative impacts of that $153bn budget. That has meant large amounts of planned state spending have not been disbursed, leaving the state finances in better shape than they would have been otherwise.
Fitch Ratings expects that low execution of capital spending and limited transfers to the Kurdistan region will help limit the size of the deficit.
“We expect growth to rebound in 2024 (1.2%), driven by public spending under the expansionary three-year budget and continued recovery in non-oil GDP. We expect non-oil growth to benefit from stronger private consumption, as inflation edges down,” says Mohamed Afifi, Fitch Ratings’ primary analyst for Iraq.
Budget deficit
Even so, reduced oil revenues have impacted Iraq’s economy, turning a budget surplus of 10.8% of GDP in 2022 into a deficit of 1.9% of GDP in 2023. Fitch sees the fiscal deficit widening, reaching 3.7% in 2024 as declining oil prices and Opec-imposed production cuts drive oil revenue down, while a heavier wage bill pushes expenditure.
The government’s debt-to-GDP ratio is also likely to rise in 2024-25, from 43.4% in 2023 to 48.7%, with Fitch attributing this to larger budget deficits that will be funded from borrowing and deposit drawdowns. However, these figures include some $40bn of legacy debt that Iraq faces no pressure to service.
The big concern is that the 2023-25 budget programme will add hundreds of thousands of workers to an already bloated public sector payroll, crowding out the private sector.
“We estimate that the expansionary three-year budget will hinder the private sector’s development by providing a sharp increase in the public workforce,” says Afifi.
“We estimate that the budget will add 600,000 employees, most of which are currently working under temporary contracts, to the public sector payroll. This would bring the public sector wage bill (salaries and pensions) to 25.8% of GDP by 2025, from 15% in 2022.”
As the IMF warned in a March 2024 commentary, higher economic growth will be needed to absorb the rapidly expanding labour force, boost non-oil exports and broaden the tax base.
In this context, urged the Fund, the Iraqi authorities should seek to enable private sector development, including through labour market reforms, modernisation of the financial sector and restructuring of state-owned banks, pension and electricity sector reforms, and continued efforts to improve governance and reduce corruption.
That is a hefty checklist for a country that is still facing myriad security, political and developmental challenges.
Al Sudani can at least counter the gloomier prognoses with the revival in non-oil sector growth, and lower inflation. Real non-oil GDP is estimated to have grown by 6% in 2023. Headline inflation declined from a high of 7.5% in January 2023 to 4% by year-end, reflecting lower international food and energy prices, and the impact of the February 2023 currency revaluation, according to the IMF.
International reserves increased to $112bn in 2023. Fitch sees FX reserves providing payment coverage above 12 months and a substantial financial buffer until the end of 2025.
Other positives will come through increased foreign direct investment, notably from the Gulf states. Saudi Arabia’s Public Investment Fund allocated $3bn for Iraqi investments last year, while Qatar’s Estithmar signed a series of memorandums of understanding worth $7bn in June 2023, covering hotel, real estate and healthcare projects.
Banking reform
One area of focus for the government is its banking sector, which remains underdeveloped and largely unfit for purpose, dominated by state-owned banks with opaque finances.
As Aysegul Ozgur, head of research at Iraq-focused Rabee Securities, says, 93.7% of currency issued was outside banks in Iraq at the end of 2022.
But, says Ozgur, the Central Bank of Iraq (CBI) is looking to strengthen financial inclusion and increase the cash inside the financial system through a series of projects.
“The salary domiciliation project of 2017 is the most prominent one among them, aiming for public sector employees to transfer their salaries to bank accounts by enabling them to receive and withdraw salaries easily through available payment channels (bank branches, ATMs and POS) and providing the ability to obtain credit facilities and bank loans by showing their salaries as collateral,” she says.
A number of other developments underscore the CBI’s concerted efforts to modernise Iraq’s financial landscape and promote economic stability.
“As a measure to control the FX flow into the banking system, the CBI now allows a limited number of banks to participate in the CBI foreign currency window and engage in US dollar transactions,” says Ozgur. “Due to the restricted number of banks permitted to engage in such activities, they benefit from an expanded market share in US dollar transactions.”
The Central Bank has also moved towards tougher oversight of the country’s 61 commercial banking institutions, made up of 54 private banks and seven state banks.
Since the CBI revised the guidelines for foreign currency transactions across borders to curb illicit financial flows in February 2023, says Ozgur, the banks that have direct correspondent banking relationships have played an active role in international money transfers and increased their commission and FX income significantly.
“The outstanding growth in current account deposits with these transfers resulted in significant growth in assets. Bank of Baghdad, National Bank of Iraq and Al-Mansour Bank are among the banks benefiting the most from these developments due to having direct correspondent banking relationships,” says Ozgur.
In February 2024, eight local commercial banks were banned from engaging in US dollar transactions, in a move to reduce fraud, money laundering and other illegal uses of the greenback. This followed a visit to Baghdad by a senior US Treasury official to Baghdad.
Such moves should, over time, help restore confidence in the financial system and – crucially – help build local insinuations that are credible players in the local economy, able to facilitate Iraq’s private sector growth ambitions, whether domestically or as part of the Iraq Development Road projects.
 Al Sudani struggles to maintain Iraq’s political stability

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Contractors win $317m Qatar road contracts
15 October 2026
-
 Kuwait studies two oil export pipelines to bypass Hormuz
15 October 2026
-
 Gulf Spic submits lowest bid for Kuwait booster stations
15 October 2026
-
 Stability holds as project work continues
14 October 2026
-
 Gas-fired projects drive resilience in UAE power sector
14 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Contractors win $317m Qatar road contracts
15 October 2026
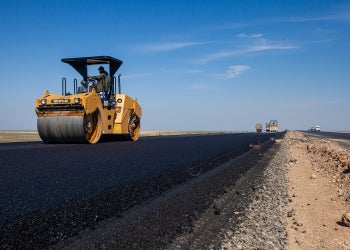
Qatar’s Public Works Authority (Ashghal) has awarded three road development contracts worth more than QR1.1bn ($317m) to local contractors for works across Qatar.
The contracts were formally awarded on 1 October, and each has a three-year construction period.
Qatar Building Engineering Company secured a QR479m ($132m) contract for roads and infrastructure works in the Wadi Al-Banat North Zone 70 area.
The contract covers constructing and upgrading local roads across several streets in the area. The scope also includes surface-water drainage, foul sewerage and treated sewage effluent networks, as well as connections to existing potable water, power and telecommunications infrastructure.
The works include an attenuation tank near the Al-Khor Expressway and Link Road 7 to collect surface water and prevent infiltration into the Northern Aquifer.
The contractor will also carry out groundwater mitigation works at the Al-Khor Expressway’s F1 interchange.
Surface works include paved medians, including sections along Umm Al-Zubar Road near Lusail Palace, as well as landscaping.
Qatar Trading & Contracting Group won the QR457m ($126m) contract to complete the remaining works on the C2021/44 roads and infrastructure scheme in Al-Sheehaniya (Package 1).
The scheme covers site preparation, earthworks, and the construction of roads, pavements, road markings, signage, traffic-calming measures and street lighting.
The scope also includes surface-water drainage and a complete pumping-station package encompassing civil, structural, mechanical, electrical, instrumentation, control and automation works.
The contractor will also install a foul sewerage network with house connections across stages one and two, alongside a treated sewage effluent system, irrigation infrastructure, landscaping and landscape lighting.
JAK Construction was awarded the QR217m ($60m) contract for the remaining works on the C/2021/038 roads and infrastructure project.
The scope covers completing the remaining civil works, road network works, and key public-utility works across Umm Slal Ali, Umm Ebariya Village, South Umm Al-Amad and North Bu Fessela (Package 1).
https://image.digitalinsightresearch.in/uploads/NewsArticle/20617022/main.jpg -
Kuwait studies two oil export pipelines to bypass Hormuz
15 October 2026
State-owned Kuwait Petroleum Corporation is considering developing two oil export pipelines that would bypass the Strait of Hormuz, according to a senior Kuwaiti oil official.
The pipelines would transport crude oil through Saudi Arabia and the UAE, aiming to diversify Kuwait’s export routes.
Mohammed Al-Abduljalil, the deputy chief executive for planning and innovation at the KPC subsidiary Kuwait Oil Company, told Asharq Bloomberg that KPC had agreed with its partners in Saudi Arabia and the UAE to conduct feasibility studies for two separate projects.
The first project extends from Kuwait’s Ahmadi region through Saudi Arabia to the Red Sea coast. The second extends from the Ahmadi region to Fujairah in the UAE.
The pipelines would build on existing infrastructure and, if the plans are approved, are expected to take around four or five years to complete, Al-Abduljalil said.
He said the first project, currently under study, would use the route of the existing East-West pipeline, which connects the kingdom’s eastern oil-producing regions to its western coast.
The second project would follow the UAE’s Habshan-Fujairah pipeline route, enabling oil exports from the Sea of Oman coast, outside the Strait of Hormuz.
Al-Abduljalil emphasised that both projects remain in a very early stage, noting that the agreement to conduct feasibility studies does not constitute a final investment decision to proceed with implementation.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20602978/main.jpg -
Gulf Spic submits lowest bid for Kuwait booster stations
15 October 2026
Kuwait-based Gulf Spic General Trading & Contracting Company has submitted the lowest bid for a contract to upgrade gas booster stations in the country.
Gulf Spic’s bid was worth KD41.2m ($132m) and was one of four bids submitted for the contract.
The project scope focuses on upgrading gas booster stations 140 and 150 (BS-140 and BS-150).
The full list of bidders was:
- Gulf Spic General Trading & Contracting Company, Kuwait – KD41.2m ($132m)
- Combined Group Contracting Company (CGC), Kuwait – KD45.5m ($146m)
- Heavy Engineering Industries & Shipbuilding Company (Heisco), Kuwait – KD50.7m ($163m)
- Alghanim International General Trading & Contracting Company, Kuwait – KD65.5m ($210m)
The project was first announced in 2014. The invitation to bid was issued in May this year, and bids were submitted ahead of the 11 October deadline.
The scope of work on the project covers:
- Upgrade of BS-140 and BS-150
- Replacement of dehydration facilities
- Laying of pipelines
- Installation of safety system
- Construction of associated facilities
Kuwait’s oil and gas sector is currently in the midst of a major crisis, as disruptions to shipping through the Strait of Hormuz have dramatically reduced exported crude oil volumes.
The disruption is also creating significant challenges for oil and gas construction projects, which normally import equipment and materials through the Strait of Hormuz.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20602827/main.jpg -
Stability holds as project work continues
14 October 2026
When Dean McGrail describes the performance of the region’s construction market, he keeps returning to a single word: “stable”.
After initial concerns that the market would experience a sharp downturn and project cancellations following the onset of conflict in the region, regional president McGrail says WSP has yet to see a single major contract cancelled across its regional portfolio.
“We have seen some projects re-evaluated – questions around whether the mix between residential and commercial is right, and whether it should be luxury residential,” he says. “But as of today, we have not seen any projects cancelled, which is a real sign of resilience in the market.”
Under the surface
That resilience does not mean nothing has changed. McGrail is careful to separate re-evaluation from cancellation. Projects already on site and selling into the market are pressing ahead. It is schemes that have not yet been released for off-plan sales that are being paused and reconsidered.
“None of the projects we are currently involved in have been put on hold or suspended,” he says. “It is more re-evaluation. Some of that is investor sentiment, but some of it is materials and logistics as well, which people do not necessarily consider.”
Logistics, in particular, is a pressure that rarely makes the headlines. According to McGrail, shipping disruption has complicated the delivery of heavy equipment on certain schemes. “If we have big pieces of kit coming in – chillers or turbines for a power station – that becomes challenging,” he says.
The bigger question is viability. And while rising material costs, set against softening sales prices, are forcing developers to reappraise the numbers, for now the balance sits firmly on the side of continuity. McGrail estimates that revalidation and feasibility work accounts for less than 3% of the firm’s current order book, with the remainder progressing as normal.
“Requests for proposals have not slowed down across any of our disciplines or business units,” he says. “We are definitely seeing an uptick in infrastructure.”
Infrastructure pivot
That focus points to where McGrail expects the next few years of growth to come from. Rail sits at the centre of the UAE story, alongside road upgrades and other major developments in Abu Dhabi. In Dubai, the clearest signal of intent is the expansion of Al-Maktoum International airport.
“Al-Maktoum is a really good indicator of the future direction of travel,” he says. “That is not a project that is slowing down. There has been a commitment to Emirates that it will move there, and it is still progressing.”
The scale of the airport – and the challenge of relocating an airline the size of Emirates in one move – raises the question of how it will be funded. Here, McGrail returns to the theme of stability and to the mechanism that underpins it.
“One of the beauties of this region is the ability of government to step in,” he says. “They can fund it. If the private sector does start to suffer, that is the backstop. They push money into infrastructure – roads, rail, airports – which keeps our industry moving.”
Saudi reset
In Saudi Arabia, the recalibration story predates the conflict, and McGrail says the change should be read as a strength rather than a retreat.
“I am positive,” he says. “When the reprioritisation started at the beginning of 2025, having lived through the global financial crisis here, I saw the decision to stop, re-evaluate and reprioritise expenditure as a positive. When Vision 2030 was set, Saudi Arabia had not won Expo or the World Cup, so the reprioritisation was the right thing to do. Saudi Arabia will come out of it stronger. Short-term pain, long-term gain.”
The nature of the work is shifting with the budget. McGrail sees the kingdom moving towards a model long familiar in the UAE, in which core infrastructure and a handful of landmark buildings are delivered first, before surrounding plots are carved up and sold on.
“You establish a few key iconic buildings, then the plots on the outside are carved up and they look for external investment to come in and develop them,” he says. “It is no different from Downtown Dubai, where Emaar built the Burj Khalifa and a few buildings, then started selling plots.”
That approach is increasingly tied to public-private partnerships (PPPs), although McGrail is measured on how far the model will stretch.
“PPP is definitely becoming more prevalent on some of the larger infrastructure projects, though still not as significant as it was made out to be when they first started talking about it,” he says. He sees industrials, mining, healthcare and schools as a natural fit, rather than PPP becoming a blanket procurement route.
Aviation is another priority. WSP was recently appointed to the rehabilitation of the existing terminal at Jeddah’s King Abdulaziz International airport, alongside a new terminal. It also recently secured a role on the expansion and upgrade of King Fahd International airport in Dammam.
“Aviation is definitely a key area of focus for us as we head into the next 12, 24, 36 months,” McGrail says.
Beyond the two dominant markets, McGrail sees pockets of activity but no challenge to the balance of the portfolio. In Qatar, he points to a recovery taking shape towards the end of last year, with WSP active on the Qatar Children’s Museum and continuing its long-running work with the Public Works Authority (Ashghal). Oman is generating masterplanning work, including reviving the Blue City scheme.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20545689/main.gif -
Gas-fired projects drive resilience in UAE power sector
14 October 2026
The $3bn Taweelah C combined-cycle gas turbine (CCGT) project has been the UAE power sector’s standout contract award this year, accounting for the majority of the $4.17bn in awards as of early September.
The total is well below the record $12.02bn awarded in 2025, when Abu Dhabi’s $6bn round-the-clock solar photovoltaic (PV) and battery energy storage system (bess) project lifted the market to record levels. However, 2026 remains broadly consistent with recent years, compared with $5.93bn in 2024 and $3.05bn in 2023.
According to MEED Projects, generation accounted for $3.06bn across three awards, while transmission contracts totalled $1.11bn.
Gas-fired focus
Emirates Water & Electricity Company (Ewec) signed the power-purchase agreement (PPA) for Taweelah C in June with a consortium comprising Abu Dhabi National Energy Company (Taqa), Saudi Arabia’s Al-Jomaih Energy & Water Company and Singapore’s Sembcorp Industries.
The scale of the 2.5GW independent power producer (IPP) provides a useful lens through which to view the wider market. Although the UAE continues to expand solar generation and battery storage, it is still investing heavily in flexible thermal capacity to support rising electricity demand and a grid with significant renewable generation.
Major gas-fired opportunities are also moving into the Northern Emirates, with state utility Etihad Water & Electricity (EtihadWE) preparing to receive offers from five contractor groups for the 2.6GW Al-Zawra CCGT project in Ajman.
The project follows the retirement of EtihadWE’s older 200MW Al-Zawra gas plant in 2023. With Ewec acting as offtaker, the scheme also points to a wider role for EtihadWE in developing large-scale generation.
It is understood that the Ajman project will be the first of at least three planned power plant projects procured by the utility under a new long-term roadmap for future projects across both power and water.
Abu Dhabi’s 3.3GW Al-Nouf IPP is another major gas-fired plant moving towards execution. Japan’s Sumitomo Corporation is expected to formally sign the PPA by the end of the year, while the joint venture of Spain’s Tecnicas Reunidas and Egypt’s Orascom Construction is also set to be confirmed as the engineering, procurement and construction (EPC) contractor.
To put this into context, the deal would make 2026 the second most valuable year for power sector investment on record, eclipsing both 2017 and 2018, when contract awards in the UAE reached $7.39bn and $7.27bn, respectively.
Solar and storage
The UAE’s renewable procurement is increasingly combining solar generation with storage to provide electricity beyond daylight hours.
Dubai Electricity & Water Authority (Dewa) is preparing to award the seventh phase of the Mohammed Bin Rashid Al-Maktoum Solar Park, with Abu Dhabi Future Energy Company (Masdar) submitting the lowest tariff for the project in July.
China’s BYD will act as a bess supplier for the project, which combines 2,000MW of PV capacity with a 1,400MW bess designed to discharge for six hours, equivalent to 8,400MWh of stored energy.
The storage component will allow Dewa to use more solar power after sunset, reducing the gap between daytime generation and the evening demand peak.
The 1,800MW sixth phase is also nearing completion, with Larsen & Toubro delivering the estimated $1.5bn project for Shuaa Energy 4, the project company formed by Dewa and Masdar.
Dewa has increased the planned capacity of the solar park to 7,260MW by 2030, from its earlier target of 5,000MW.
Furthermore, Ewec is advancing its 1.5GW Al-Zarraf solar PV plant, with EDF and Korea Western Power Company selected as the consortium to develop the project.
Grid expansion
Multibillion-dollar IPP schemes have driven annual award values in recent years, while transmission work continues to provide a steadier flow of opportunities for contractors and equipment suppliers.
Transmission awards fell to $1.11bn across 22 packages in 2026, from $2.98bn in 2025, reflecting the absence of a comparable large-scale package rather than a halt in network investment.
Ewec and Taqa are expanding 400kV and 132kV networks across Abu Dhabi and the Northern Emirates, while Dewa continues to reinforce its cable and substation systems in Dubai.
In September, EtihadWE received bids for a contract to carry out a techno-economic feasibility study for a proposed 2GW subsea electricity interconnector with India.
The proposed 1,400-kilometre link would be the UAE’s first direct subsea cross-border electricity interconnector, illustrating a potential longer-term ambition to connect the UAE to wider regional and international power markets.
Earlier this year, the GCC Interconnection Authority awarded Omexom, part of France’s Vinci Group, a contract to build a 400kV overhead transmission line between the UAE and Saudi Arabia.
In October, the UAE and Saudi Arabia signed a memorandum of understanding to advance cross-border electricity interconnection, paving the way for feasibility studies on power exchange, commercial electricity trading and the expansion of the wider GCC interconnection grid.
Waste-to-energy
Waste-to-energy continues to become an increasingly important part of the UAE’s infrastructure pipeline as the country seeks to reduce landfill dependence and diversify its power mix through alternative generation sources.
Dubai Municipality recently invited developers to submit expressions of interest for its planned Jebel Ali waste-to-energy public-private partnership, a greenfield facility designed to treat up to 6,000 tonnes of municipal solid waste a day.
According to a source, the municipality plans to prequalify developers later this year, then issue a request for proposals in the first quarter of 2027.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20582379/main.gif