Iberian power outage offers valuable lessons
2 May 2025
 Commentary
Jennifer Aguinaldo
Energy & technology editor
The root cause of the power outages that gripped parts of the Iberian Peninsula on 28 April has yet to be established, pending a detailed investigation into what triggered the loss of power in large swathes of Portugal and Spain.
Ongoing investigations aside, Spain’s national electricity grid operator, Red Electrica, has ruled out a cyber attack or sudden spike in renewables as the main cause of the outage, which affected transport, retail and healthcare services, among others.
Insurance claims arising from the outages could reach between $300m and $600m in Spain and significantly less in Portugal, according to some sources, while the Riyadh-based Digital Cooperation Organisation cites losses of up to €1.3bn ($1.47bn) for the Spanish economy, based on Spain’s self-employed workers’ association, ATA.
But the highest cost could come in a non-monetary form. It would require probing into Spain’s utility infrastructure, which Red Electrica describes as Europe’s “best and most resilient”, and that of every European country and everywhere else.
Red Electrica president Beatriz Corredor has been quick to defend her firm, saying there is no such thing as zero risk.
The speed at which Spain, which exports renewable power to Portugal, restored power in affected areas lends credence to Red’s best-in-Europe claim if one is willing to forego the question of how it could have happened or been avoided in the first place.
Pending the results of the investigation, analysts and experts have offered their insights on the subject.
Writing on Linkedin, Thierry Lepercq, founder and president at Hydeal, describes the Spanish blackout as “the most significant power event in decades”, adding it is likely the first of a series of crippling crashes that will result from the inherent conflict between decarbonisation, or aiming at 100% renewables; security of supply; and energy affordability.
Lepercq is confident that the lesson will soon be clear: the power outage was all about inertia.
He predicts that the lack of electricity system planning will necessitate radical action. This could involve the “near complete” stop of new variable – solar and wind – installations and the fast ramp-up of fully-dispatchable, inertia-providing capacity from combined-cycle gas turbines (CCGTs) initially powered by natural gas, and as soon as possible, from competitive green hydrogen.
Another senior consultant at an international engineering services firm with offices in Dubai tells MEED that, considering a lot of caveats, the blackout resulted from a mix of high solar reliance, low grid inertia, voltage oscillations and insufficient backup systems, with no single cause confirmed. Some tripping, which catalysed the inertia problem, has also been reported, he notes.
Prevention strategies could include enhancing firm power, expanding storage, improving monitoring and strengthening interconnections.
Morocco, for instance, played a key role in restoring power to Spain, highlighting the benefits of power pooling, where countries share an integrated generation capacity and grid stability across borders.
Reviewing energy policies is also key, such as looking at grid codes with clearer requirements on how much energy storage should be on the system in proportion to renewable energy development, according to the consultant.
This event offers valuable lessons for regional utility stakeholders, particularly their capacity planning divisions. Over 100GW of renewable energy capacity is planned to be built across the GCC states before 2030, excluding those catering to private clients, with certain developments and projects looking to be powered 100% by renewable energy by 2030.
The Iberian story shows there are as many potential solutions or measures, with none offering zero risk, to address potential points of failure in today’s electricity system, which has been undergoing major re-engineering works to fit the 2030 net-zero scenario.
It is also worth mentioning that certain jurisdictions in the Gulf and broader Middle East and North Africa region regularly suffer from power outages in the summer, mainly due to rising temperatures and underinvestment in electricity generation and distribution networks, and notwithstanding a very negligible amount of renewable power on their grids.
Credit: Crowd at Malaga Maria Zambrano train station entrance due to blackout in Spain and Europe, 28 April 2025. Shutterstock

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Read the October 2026 MEED Business Review
30 September 2026
-
 Aramco receives interest for major gas processing plant
30 September 2026
-
 Libya refinery expected to be worth more than $600m
30 September 2026
-
 Joint venture wins $230m Ras El-Hekma buildings
30 September 2026
-
 Neom tenders Oxagon freight rail design
30 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Read the October 2026 MEED Business Review
30 September 2026
Download / Subscribe / 14-day trial access For all the talk of cancellations and cutbacks, Neom is still building – and its biggest completed project to date offers a clue to where the $500bn gigaproject is heading. Our October Agenda feature examines how Oxagon is moving to the centre of Neom’s strategy, as investment shifts towards projects with the potential to generate tangible commercial returns, from green hydrogen and ports to AI data centres and logistics infrastructure.
 Read the full analysis in the October issue of MEED Business Review.
As Neom reshapes its priorities, Saudi Arabia’s wider project market continues to show resilience. Contract awards have reached $68bn in 2026, despite regional conflict and economic uncertainty, with activity spanning energy, infrastructure, power and the future economy.
But with $91.5bn of projects completed this year, new awards will be crucial to maintaining momentum into 2027.
This edition also includes MEED’s 2026 power developer ranking, revealing the companies driving the region’s rapidly expanding power market.
The issue also explores key trends shaping the region, from AI’s growing demands on grid capacity and the implications of ICE Futures Abu Dhabi’s wind-down for Gulf commodity markets, to how the Hormuz crisis is redirecting oil companies’ focus to North Africa. Our Leadership feature asks whether the future city really needs to hang above the ground.
We hope our valued subscribers enjoy the October 2026 issue of MEED Business Review.

Must-read sections in the October 2026 issue of MEED Business Review include:
 > AGENDA: Oxagon takes centre stage at Neom
INDUSTRY REPORT:
MEED’s 2026 power developer ranking
> Regional power market diversifies
> Battery storage broadens IPP market> POWER: AI is creating a grid capacity problem
> LEGAL: What IFAD’s wind-down means for Gulf commodity markets
> OIL: Oil companies focus on North Africa amid Hormuz crisis
> LEADERSHIP: The future city does not need to hang above the ground
> SAUDI ARABIA MARKET FOCUS:
> COMMENT: Saudi projects hold steady
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflict
> DATABANK: Saudi data indicates project spending shift> MEED COMMENTS:
> Dubai Inc steps in as developers turn cautious
> Saudi Arabia redirects towards AI
> Kuwait plans biggest oil and gas contract award in 10 years
> Saudi Arabia battery storage awards provide fresh lift> GULF PROJECTS INDEX: Saudi Arabia and UAE lead Gulf index gains
> AUGUST 2026 CONTRACTS: Middle East contract awards
> ECONOMIC DATA: Data drives regional projects
> OPINION: The boomers’ last act
> BUSINESS OUTLOOK: Finance, oil and gas, construction, power and water contracts
To see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20134595/main.gif -
Aramco receives interest for major gas processing plant
30 September 2026
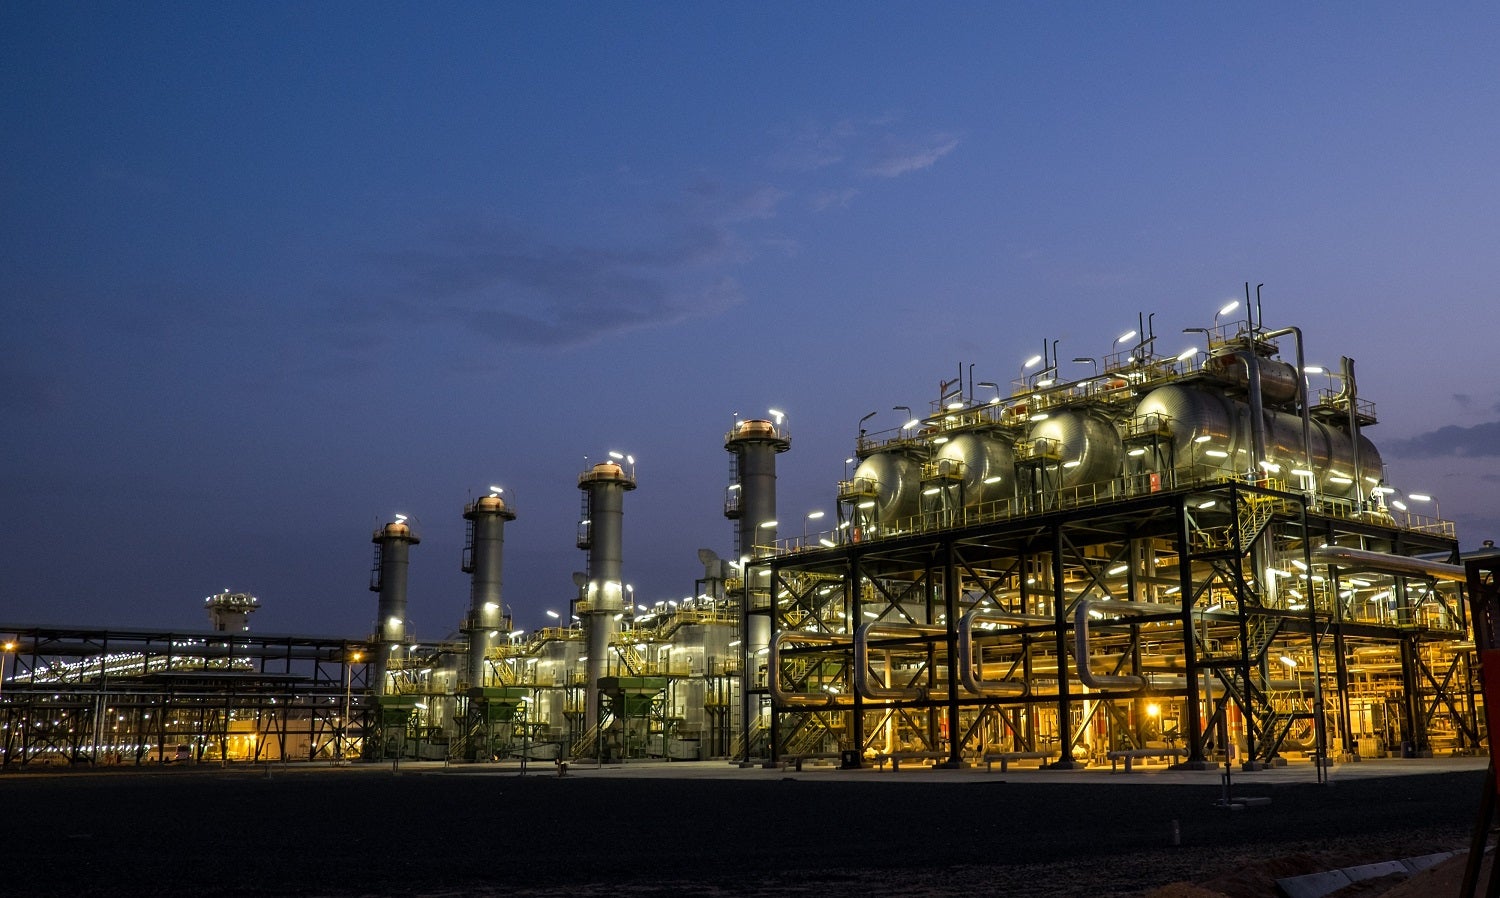
Saudi Aramco has received expressions of interest from contractors to participate in the main tendering exercise for a project to expand the Alhada gas processing plant, located about 85 kilometres northwest of Jubail in Saudi Arabia’s Eastern Province.
The Alhada gas processing plant expansion is critical to Aramco’s goal of increasing gas production capacity by 80% by 2030 from a 2021 baseline.
Aramco issued a solicitation of interest document for the main tendering exercise in early September, with contractors submitting responses by 17 September, sources told MEED.
The engineering, procurement and construction (EPC) scope of work has been divided into three main packages, sources said.
The first EPC package relates to the main gas treatment facilities, primarily three processing trains, along with:
- Three acid gas removal units
- Triethylene glycol (TEG) dehydration unit
- Two high-pressure and two low-pressure flares
- Two flare gas recovery units
- Two T&l flares
- Two burn pits
- A digital twin
The acid gas removal units will treat sour gas by removing hydrogen sulphide and carbon dioxide to produce sales gas, as well as acid-gas feed for the downstream acid gas enrichment unit and sulphur recovery unit.
The acid gas removal units will also process gas from the flare gas recovery units through a dedicated amine contactor to meet specifications for use as fuel gas. The TEG dehydration unit will then remove water from the treated gas to meet sales-gas specifications.
The project’s second EPC package covers the sulphur recovery units. The third package involves inlet channels for monoethylene glycol, as well as common utilities and supporting structures.
ALSO READ: Contractors express interest in sixth Jafurah expansion phase
https://image.digitalinsightresearch.in/uploads/NewsArticle/20127671/main4900.jpg -
Libya refinery expected to be worth more than $600m
30 September 2026
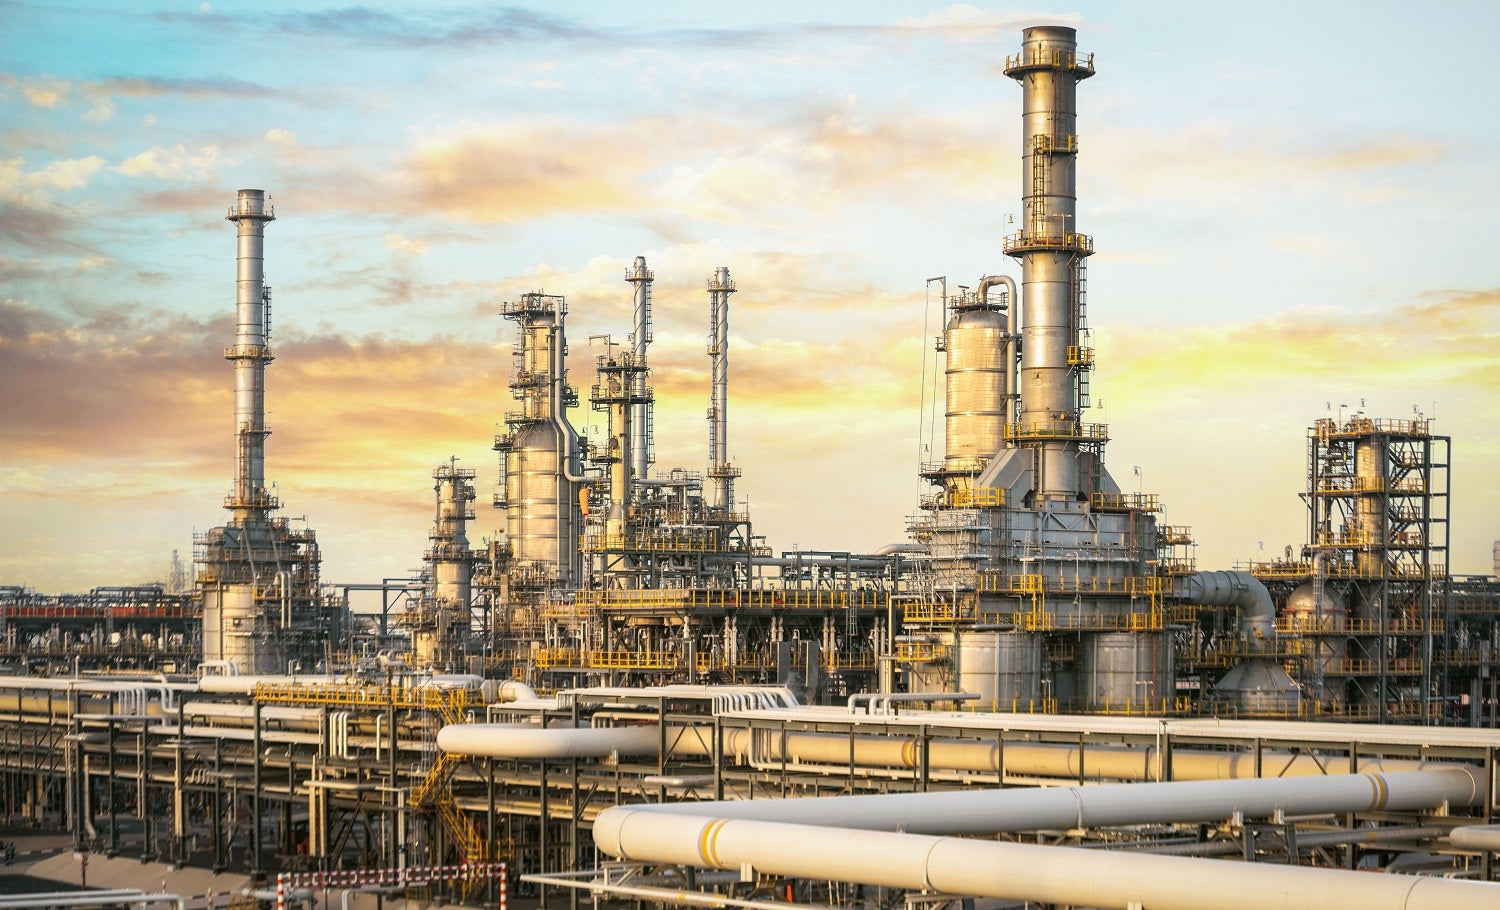
The main contract for Libya’s planned South Refinery project is expected to be worth more than $600m, according to industry sources.
The project, located in Ubari in southern Libya, has gained momentum over the past year. The main contract is expected to be procured under an engineering, procurement and construction (EPC) model.
In March, US-based engineering company KBR was awarded a contract by Zallaf Exploration, Production & Refining of Oil & Gas Company to provide project management and technical services for the project.
Under the terms of the contract, KBR will provide contract management, project management and supporting technical services throughout the project’s EPC phases.
The EPC work is expected to take 50 months, and the facility will be designed to process 30,000 barrels a day (b/d) of crude oil.
The refinery is expected to produce:
- Propane and butane for domestic and industrial uses
- Gasoline
- Kerosene
- Diesel
- Fuel oil
In March, KBR said that the project was aligned with its “long-standing commitment to advancing vital oil and gas infrastructure in Libya”.
Libya currently operates five main refineries with a combined nameplate capacity of 380,000 b/d, but actual throughput is closer to 180,000 b/d due to poor maintenance and damage from military clashes.
In addition to the South Refinery project, Libya also plans to upgrade the Zawiya refinery and carry out projects at the Serir, Brega, Tobruk and Ras Lanuf refineries.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20124329/main.jpg -
Joint venture wins $230m Ras El-Hekma buildings
30 September 2026
A joint venture of UK-based Innovo Build and Egypt’s Redcon Construction has won a contract worth about E£12bn ($230m) to carry out infrastructure and construction works for the DP03 East package of the Wadi Yemm development at Ras El-Hekma on Egypt’s North Coast.
Wadi Yemm is being developed by the UAE’s Modon Development as the first phase of its Ras El-Hekma masterplan, which will comprise 17 planned districts.
DP03 East has a built-up area of 323,000 square metres and is scheduled for completion within 21 months.
The scope of work includes more than 660 residential units – comprising standalone villas and townhouses – as well as public service areas, lakes, a commercial mall, landscaping and roadworks.
The delivery of units at Wadi Yemm is expected to begin in the third quarter of 2029.
Ras El-Hekma is located on a spur of land on Egypt’s northern Mediterranean coast, about 240 kilometres west of Alexandria.
Abu Dhabi-based holding company ADQ appointed Modon Holding as master developer for the Ras El-Hekma project in 2024. Modon will oversee the overall development, which covers more than 170 million square metres (sq m).
Modon will develop the first phase, covering 50 million sq m. The remaining 120 million sq m will be developed in partnership with private developers, under the supervision of the recently established ADQ subsidiary Ras El-Hekma Urban Development Project Company and Modon.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20123189/main.jpg -
Neom tenders Oxagon freight rail design
30 September 2026
Register for MEED’s 14-day trial access
Neom has tendered a contract to prepare a concept design, feasibility study and route-alignment studies for a freight rail network connecting to the Port of Neom at Oxagon.
Neom issued the tender last week, with a submission deadline of 29 October.
Consultants expressed interest in the contract on 16 September, as MEED previously reported.
The estimated 400-kilometre (km)-plus rail line is expected to connect the Port of Neom with Saudi Arabia Railways’ (SAR) North-South Railway at the Al-Baseeta junction.
SAR’s North-South Railway is a 2,750km network built primarily to move minerals from mines in the north of the kingdom to industrial and export hubs on the Gulf coast. Its core route links the Al-Jalamid and Baitha phosphate and bauxite mines to Ras Al-Khair, Jubail and Dammam, with branch lines to Riyadh and to the Jordanian border at Al-Haditha.Al-Baseeta junction, where Oxagon’s proposed line would connect, sits on this network in Al-Jawf province, in the northwest of the country. The railway also carries passengers between Riyadh and Qurayyat, and has transported commercial freight such as sulphur and phosphoric acid.
The Port of Neom currently has no rail link to the rest of Saudi Arabia, meaning cargo landing there depends on road transport or a further sea leg to reach Riyadh, the Gulf coast or export markets beyond.
Connecting to the North-South network at Al-Baseeta would give the port direct rail access to the kingdom’s interior and, via existing branch lines, to Jordan and the Gulf coast industrial cluster around Ras Al-Khair, Jubail and Dammam.
The proposed link would also give SAR’s network a new outlet to the Red Sea. To date, the North-South Railway has focused on Gulf coast export points, but a connection to Oxagon would provide a second maritime gateway on the opposite coast, allowing mineral and freight traffic from the north of the kingdom to reach either coastline.
The latest development follows Saudi Arabia’s Public Investment Fund (PIF) naming Neom as one of six strategic ecosystems in its 2026-30 strategy.
This backing comes as Neom’s operational focus appears to be evolving in response to shifting regional dynamics and global economic conditions. For example, on 15 April, Neom posted on its official X account about a new Europe-Egypt-Neom-GCC corridor, describing it as a faster route for time-sensitive goods.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20122376/main.jpg