Hydrocarbons exploration rebounds
1 March 2023
MEED's upstream oil & gas report also includes: Energy security facilitates upstream spending

The world, and particularly countries in the Middle East and North Africa (Mena) region, remains undeterred in its quest to find more oil and gas resources, despite headwinds from energy transition activity and falling long-term hydrocarbons demand forecasts.
Last year, the global oil and gas exploration sector had its strongest year in more than a decade. In its effort to improve portfolios by adding lower-carbon, lower-cost advantaged hydrocarbons, the sector created at least $33bn of value and achieved full-cycle returns of 22 per cent, at $60-a-barrel Brent prices, according to a recent report from Wood Mackenzie.
Julie Wilson, director of global exploration research at Wood Mackenzie, says 2022 was “a standout year for exploration”.
“Volumes were good, but not stellar. However, explorers were able to drive very high value through strategic selection and by focusing on the best and largest prospects.
“The discoveries bring higher-quality hydrocarbons into companies’ portfolios, allowing them to reduce carbon by displacing less advantaged oil and gas supplies while also meeting the world’s energy needs.
“The highest value came from world-class discoveries in a new deepwater play in Namibia, as well as resource additions in Algeria and several new deepwater discoveries in Guyana and Brazil, where the latest wave of pre-salt exploration finally met with success,” she says.
“The average discovery last year was over 150 million barrels of oil equivalent, more than double the average of the previous decade,” she adds.
The exploration sector continues to be dominated by national oil companies (NOCs) and majors, with QatarEnergy, France-headquartered TotalEnergies and Brazil’s Petrobras leading the way in net new discovered resources in 2022, according to Wood Mackenzie. In total, NOCs and majors accounted for almost three-quarters of new resources discovered, the research consultancy said.
Qatar’s overseas footprint
In addition to raising gas production capacity from the North Field gas reserve and carrying out a liquefied natural gas (LNG) output expansion programme, QatarEnergy has been pursuing an overseas offshore oil and gas exploration and production (E&P) campaign in recent years.
The state enterprise has been investing in expanding its international upstream footprint, particularly in the gas space. In the past five years, QatarEnergy has acquired interests in gas-rich offshore blocks in Angola, Guyana, Kenya, Egypt, South Africa, Argentina, Mozambique, Morocco, Cyprus, Mexico, Brazil, Oman, Suriname and Canada.
In December, QatarEnergy won an offshore exploration block in Brazil in a consortium with TotalEnergies and Malaysia’s Petronas. QatarEnergy will hold a 20 per cent working interest in the Agua-Marinha production sharing contract, with TotalEnergies holding 30 per cent and Petronas Petroleo Brasil holding 20 per cent. Brazil’s state energy producer ANP will be the operator of the block, with a 30 per cent interest.
QatarEnergy also recently acquired a 30 per cent interest in exploration blocks four and nine off the coast of Lebanon. TotalEnergies is the operator of the blocks, holding a 35 per cent interest, with Italy’s Eni owning the remaining 35 per cent.
Oman E&P arena
Oman hosts the most foreign hydrocarbons E&P companies in the GCC. Majors such as BP, Shell and TotalEnergies have been present in the sultanate since the early 20th century, while smaller international upstream players have also been looking for – and producing – oil and gas for the past three decades.
The majority state-owned Petroleum Development Oman (PDO) operates the sultanate’s biggest and most prolific hydrocarbons concession, block six. The smaller oil and gas concession areas are operated by firms headquartered overseas such as Eni, Occidental Petroleum, Tethys Oil and Maha Energy, as well as by local firms such as ARA Petroleum, Majan Energy & Petroleum and Musandam Oil & Gas Company.
Oman’s Energy & Minerals Ministry signed a concession agreement in December 2021 with a consortium led by Shell’s Oman subsidiary, Shell Integrated Gas Oman, to develop and produce natural gas from block 10 of the Saih Rawl gas field.
The consortium comprises Omani state energy enterprise OQ and Marsa LNG, a joint venture of France’s TotalEnergies and OQ. The concession agreement established Shell as the operator of block 10.
By late January, Shell had started producing gas from the Mabrouk North East field located in block 10.
In September last year, the Omani energy ministry signed another E&P agreement with Shell and France’s TotalEnergies to develop block 11, which is located adjacent to block 10 and is understood to be rich in natural gas reserves.
Shell and TotalEnergies will own 67.5 per cent and 22.5 per cent stakes in block 11, respectively, with OQ holding the other 10 per cent. Shell is the operator with the majority stake in the concession.
UAE makes strides
Abu Dhabi National Oil Company (Adnoc) has completed two upstream concession licensing rounds in the past
four years, attracting oil and gas producing companies from the US, Italy, Pakistan, India, Thailand and Japan to explore for resources.
Offshore block two, which is operated by Italian energy major Eni with Thailand’s state-owned PTT Exploration & Production Public Company (PTTEP), has so far yielded two discoveries with combined estimated reserves of up to 3 trillion cubic feet (tcf) of gas.
In addition, in May last year, Adnoc announced the discovery of 650 million barrels of onshore crude oil reserves in Abu Dhabi, which increased the UAE’s hydrocarbons reserves base to 111 billion stock tank barrels of oil and 289 tcf of gas.
Adnoc also awarded Malaysia’s Petronas a six-year concession agreement in December to explore and appraise oil in unconventional onshore block one, deemed to be the Middle East’s first unconventional oil concession.
In Sharjah, Eni won stakes in all three upstream concession areas offered by Sharjah National Oil Company (SNOC) to international investors in the emirate’s first competitive hydrocarbons block bidding round, launched in June 2018.
In January 2019, Eni successfully secured 75 per cent, 50 per cent and 75 per cent stakes in SNOC’s concession areas A, B and C, respectively.
Then, in October last year, PTTEP acquired a 25 per cent stake from Eni in area A, as a result of which Eni’s share in all three concession zones is now at 50 per cent.
Sharjah’s oil and gas fortunes reversed in January 2021, when SNOC, together with its partner Eni, announced the start-up of the Mahani 1 gas well. This marked the commencement of gas production from the Mahani field, located in area B, the first such onshore hydrocarbons discovery made in Sharjah in 37 years.
 Energy security facilitates upstream spending
Bahrain labours on
Bahrain announced the discovery of the large Khalij al-Bahrain offshore hydrocarbons basin – estimated to contain 80 billion barrels of oil and 10-20 trillion cubic feet of gas – in April 2018.
Nearly five years later, Manama has been unable to make significant progress on the commercial appraisal of the oil and gas resources base. However, the lack of success with Khalij al-Bahrain has not deterred the country from continuing its exploration elsewhere.
In November, state energy conglomerate Nogaholding announced the discovery of natural gas in the two reservoirs of Al-Jawf and Al-Juba. The gas deposits are unconventional and situated in the Khuff and Unayzah geological formations.
Mena players make progress
Iraq, Opec’s second-largest oil producer, continues to seek more hydrocarbons resources in its territory. As recently as in February, the Oil Ministry awarded six oil concessions as part of the country’s fifth licensing round.
Three E&P concessions – one in Basra and two in Diyala governorates – were awarded to UAE-based Crescent Petroleum. Three others, also in Basra and Diyala, were awarded to China’s Geo-Jade Petroleum.
Eni’s discovery of the large Zohr gas field in the Mediterranean waters in 2015 elevated Egypt’s status as a significant upstream market globally, and the country’s government intends to continue to attract more E&P players on the back of this success.
Egypt’s hydrocarbons reserves spiked in 2022 with 53 new oil and gas discoveries: 42 oil wells and 11 gas wells, according to the Petroleum & Mineral Resources Ministry. The discoveries were made in Egypt’s Western Desert region, the Suez Gulf, the Mediterranean Sea and the Nile Delta.
So far in 2023, US-based Chevron, which operates the Nargis offshore concession in the East Mediterranean, together with its partners Eni and Egypt’s Tharwa Petroleum, has announced a discovery of Miocene and Oligocene gas-bearing sandstones.
At the start of this year, Egypt also launched an international licensing round for exploration rights in the Nile Delta and the Mediterranean, comprising 12 onshore and offshore blocks.
“There is a lot of uncertainty in future long-term demand scenarios for oil,” says Wilson.
“Explorers are accelerating oil exploration to meet near- and mid-term demand, while gas exploration was focused in geographies that can supply the gas-hungry European market. In some cases, major leases are approaching the expiration of the exploration term and companies are pushing to optimise their value.”
She concludes: “By 2030, fast-tracked development of these new discoveries could deliver 1 million barrels a day in oil and half a million barrels a day of equivalent gas production, generating $15bn in free cash flow.”

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 WEBINAR: End-of-Year Mena Market Review
13 November 2026
-
 PDO awards contract for Al-Ghubar oil field project
12 November 2026
-
 Laing O’Rourke joins the international exit list
12 November 2026
-
 Poland’s Orlen terminates QatarEnergy LNG supply deal
11 November 2026
-
 Riyadh shifts bid deadline for King Salman Stadium works
11 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
WEBINAR: End-of-Year Mena Market Review
13 November 2026
Webinar: The big questions shaping the Gulf market. You decide what gets debated.
Tuesday 24 November 2026 | 11:00 AM GST | Register now
What makes this session particularly interesting is that the audience gets to decide the agenda. Registrants can vote for the topics they’d like Ed and Colin to debate, with the most popular questions forming the final shortlist for the live session.
Topics in the ballot:
- Is the Gulf trying to build too much, too quickly?
- Saudi Arabia or the UAE: where would you place your next big bet?
- Are gigaprojects the best use of public money?
- Who is really responsible when projects go wrong?
- Should the lowest-price tender become a thing of the past?
- Can private capital take over from the government in financing infrastructure and diversification?
- Is the Gulf’s AI and data centre boom a smart bet or the next overbuilding risk?
- Should the Gulf double down on hydrocarbons to fund diversification?
- Is localisation strengthening the economy or making delivery harder?
- Are Gulf countries building complementary economies or competing for the same customers?
The session will also feature live audience polling and Q&A, giving attendees an opportunity to share their views.
Hosted by:
Edward James, head of content and analysis at MEED
 A well-known and respected thought leader in Mena affairs, Edward James has been with MEED for more than 19 years, working as a researcher, consultant and content director. Today, he heads up all content and research produced by the MEED group. His specific areas of expertise are construction, hydrocarbons, power and water, and the petrochemicals market. He is considered one of the world’s foremost experts on the Mena projects market. He is a regular guest commentator on Middle East issues for news channels such as the BBC, CNN and ABC News and is a regular speaker at events in the region.
Colin Foreman, editor of MEED
 Colin Foreman is editor and a specialist construction journalist for news and analysis on MEED.com and the MEED Business Review magazine. He has been reporting on the region since 2003, specialising in the construction sector and its impact on the broader economy. He has reported exclusively on a wide range of projects across the region including Dubai Metro, the Burj Khalifa, Jeddah Airport, Doha Metro, Hamad International airport and Yas Island. Before joining MEED, Colin reported on the construction sector in Hong Kong.https://image.digitalinsightresearch.in/uploads/NewsArticle/21380319/main.gif
-
PDO awards contract for Al-Ghubar oil field project
12 November 2026
Register for MEED’s 14-day trial access
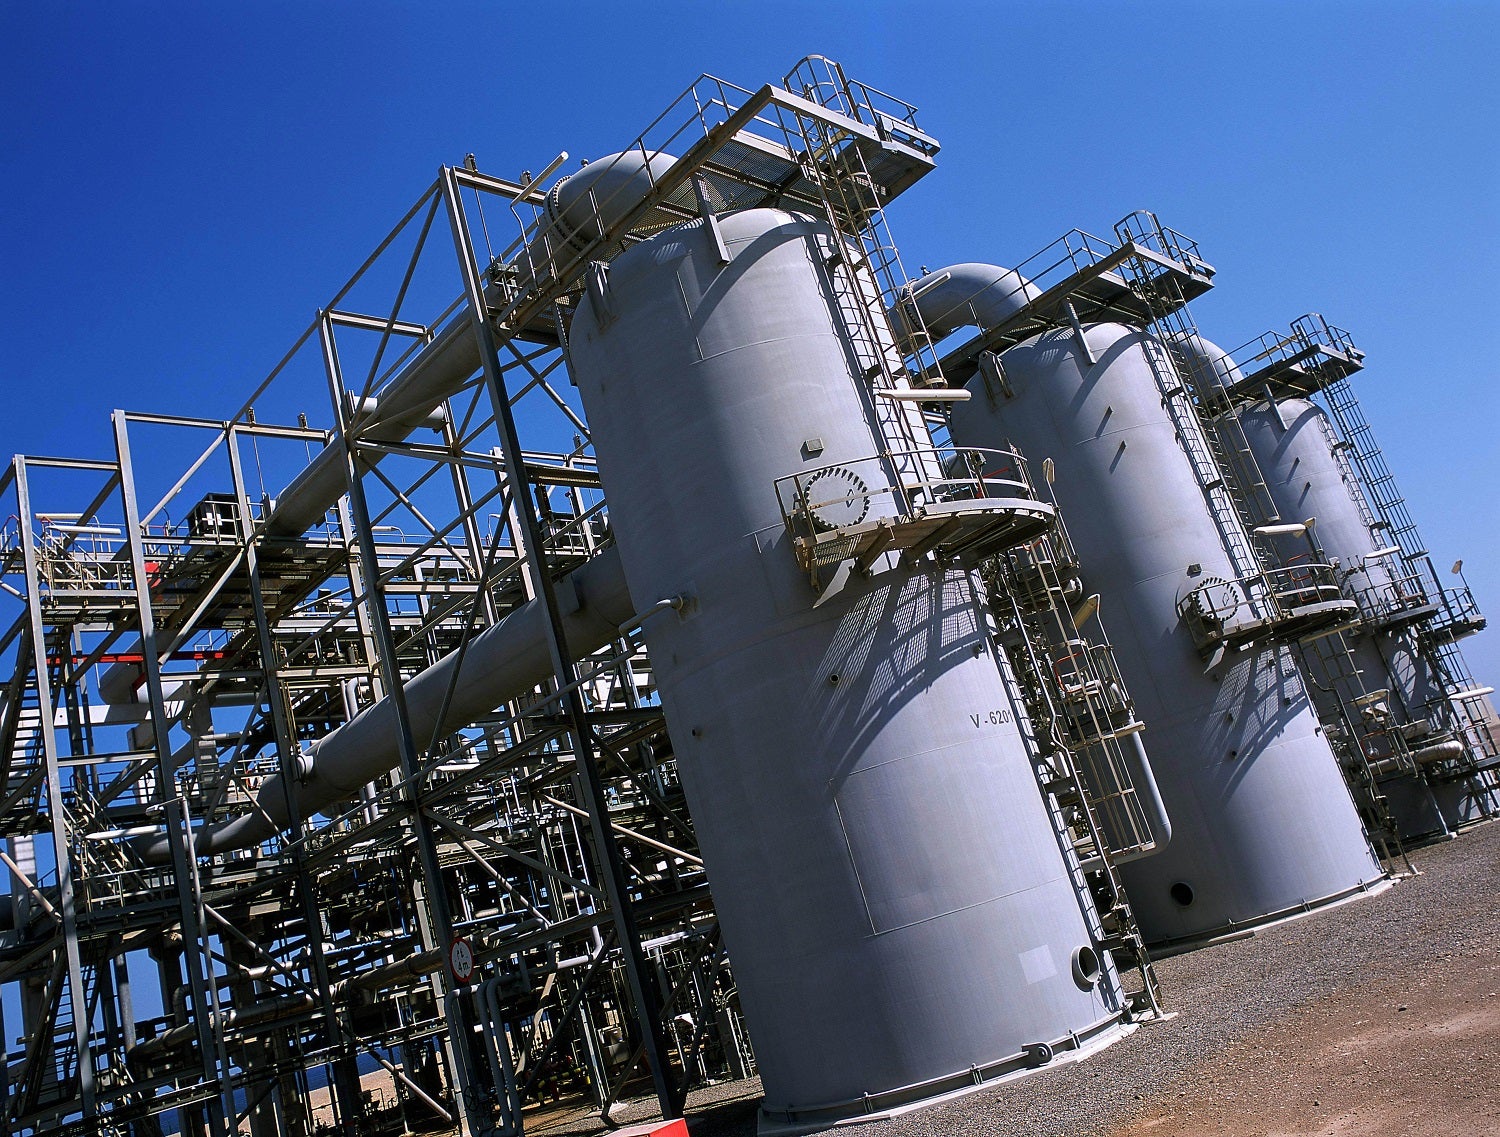
Petroleum Development Oman (PDO) has awarded the main contract for a project to build a facility to handle additional oil production from the Al-Ghubar field in the sultanate.
The Al-Ghubar field is located in the Ghaba Salt Basin at Qarn Alam, within majority state-owned PDO’s Block 6 concession area.
The Al-Ghubar gas-oil gravity drainage (GOGD) facility will be designed as a sour (hydrogen sulphide) facility and is expected to handle a maximum oil production rate of 1,800 standard cubic metres a day (cm/d), a total water flow rate of up to 10,421 standard cm/d and gas lift of up to 256,934 standard cm/d. Production from the planned Al-Ghubar GOGD facility will be exported to PDO’s main oil line.
China-based Jereh Group has won the contract for the Al-Ghubar GOGD facility project, sources told MEED.
A project kick-off meeting between PDO and Jereh has also recently taken place, the sources said.
MEED previously reported that Jereh had emerged as the lowest bidder for the project.
The following contractors, among others, are understood to have been bidding for the Al-Ghubar GOGD facility project:
- Engineering for the Petroleum & Process Industries (Egypt) / Petrojet (Egypt)
- GS Engineering & Construction (South Korea)
- Jereh (China)
- Larsen & Toubro Energy Hydrocarbon (India)
PDO floated the tender for the Al-Ghubar GOGD facility project in March, setting an initial bid submission deadline of 4 May, MEED previously reported.
PDO later extended the deadlines for the submission of technical and commercial bids to 26 July and 7 August, respectively. Contractors submitted technical proposals by the revised deadline, according to sources.
After receiving the technical bids for the project in July, PDO granted contractors until 16 August to submit commercial bids. It eventually extended the deadline to 1 September, with contractors submitting commercial proposals by that date, as MEED reported.
The scope of work on the Al-Ghubar GOGD project covers the engineering, procurement and construction (EPC) of the following:
- On-plot scope, consisting of:
- Production separator
- Test separator
- Concentric wash tank
- Wet oil pump
- Water bath heater
- Surge tank
- Gas injection/gas lift compressor (centrifugal)
- Utilities (instrument air compressors, chemical injection skids, drain system, vent system)
- Suction scrubber
- Air coolers
- Discharge scrubbers
- Condensate flash drum
- Atmospheric pressure knock-out drum
- Flare system
- Gas heater
- Water disposal pump
- Oil shipping pump
- 132kV substation and plant substation (housing 6.6kV and 415-Volt switchboard)
- Control room
- Off-plot scope consisting of:
- Off-plot pipeline network (bulk header, test header, gathering infrastructure/ gathering line header, instrument air header, water disposal header)
- Two remote manifold stations
- Tie-in connection to main oil line
- Tie-in to gas network pipeline
PDO previously intended to tender the Al-Ghubar GOGD project under its framework structure with selected EPC contractors, but ultimately tendered it separately.
PDO is the operator of Oman’s Block 6 hydrocarbons concession, the sultanate’s largest and most prolific concession. Situated onshore and covering an area of 75,119 square kilometres, Block 6 contains 202 oil fields and 43 gas fields. PDO produces approximately 680,000 barrels a day of oil and condensates from the fields.
The Omani government holds a 60% stake in PDO through Energy Development Oman. The other shareholders are UK-based Shell (34%), France’s TotalEnergies (4%) and Thailand’s state-owned PTTEP (2%).
https://image.digitalinsightresearch.in/uploads/NewsArticle/21345337/main2647.jpg -
Laing O’Rourke joins the international exit list
12 November 2026
Commentary
Colin Foreman
EditorRegister for MEED’s 14-day trial access
Laing O’Rourke’s decision to seek a buyer for its Middle East business marks the end of an era for UAE construction.
In the early 2000s, the contractor was among the leading names in the market. Its work at Dubai International airport, the Atlantis hotel on the Palm Jumeirah and the ski slope at Mall of the Emirates made it arguably the UAE’s most prominent contractor during the pre-global financial crisis construction boom.
Its activities were not limited to Dubai. A partnering agreement with Aldar for Al-Raha Beach then made it the most active contractor in Abu Dhabi almost overnight.
The global financial crisis changed its fortunes. The Aldar Laing O’Rourke joint venture ended. Unsettled by payment problems and wider stress in the industry, the company took a more cautious approach to clients and projects in the region. One executive at the time told MEED: “You might see lots of tower cranes, but none of them are doing work that we would want to do.”
The contractor’s appetite partially returned in the late 2010s, when it won Al-Wasl Plaza at the Expo 2020 site in Dubai. It also became a leading player in the growing data centre market, delivering facilities for repeat clients, including Khazna and Equinix.
Data centres have since been its focus. These are significant projects, but they lack the public profile of the airport, Atlantis and Al-Wasl Plaza. As its profile faded, the company sold its UAE joinery arm to Dubai-based Arco Turnkey Solutions in 2025.
Laing O’Rourke now looks set to follow other international contractors that have, for various reasons, left the region, including Murray & Roberts, Balfour Beatty, Multiplex, Carillion and Bam. With a record £17.2bn order book anchored by UK and Australian infrastructure, the group’s priorities clearly lie elsewhere.
Whoever buys the business will inherit strong data centre credentials. For much of the market, however, Laing O’Rourke will be remembered for the landmark projects that defined the UAE’s boom years.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21344577/main.jpg -
Poland’s Orlen terminates QatarEnergy LNG supply deal
11 November 2026
Register for MEED’s 14-day trial access
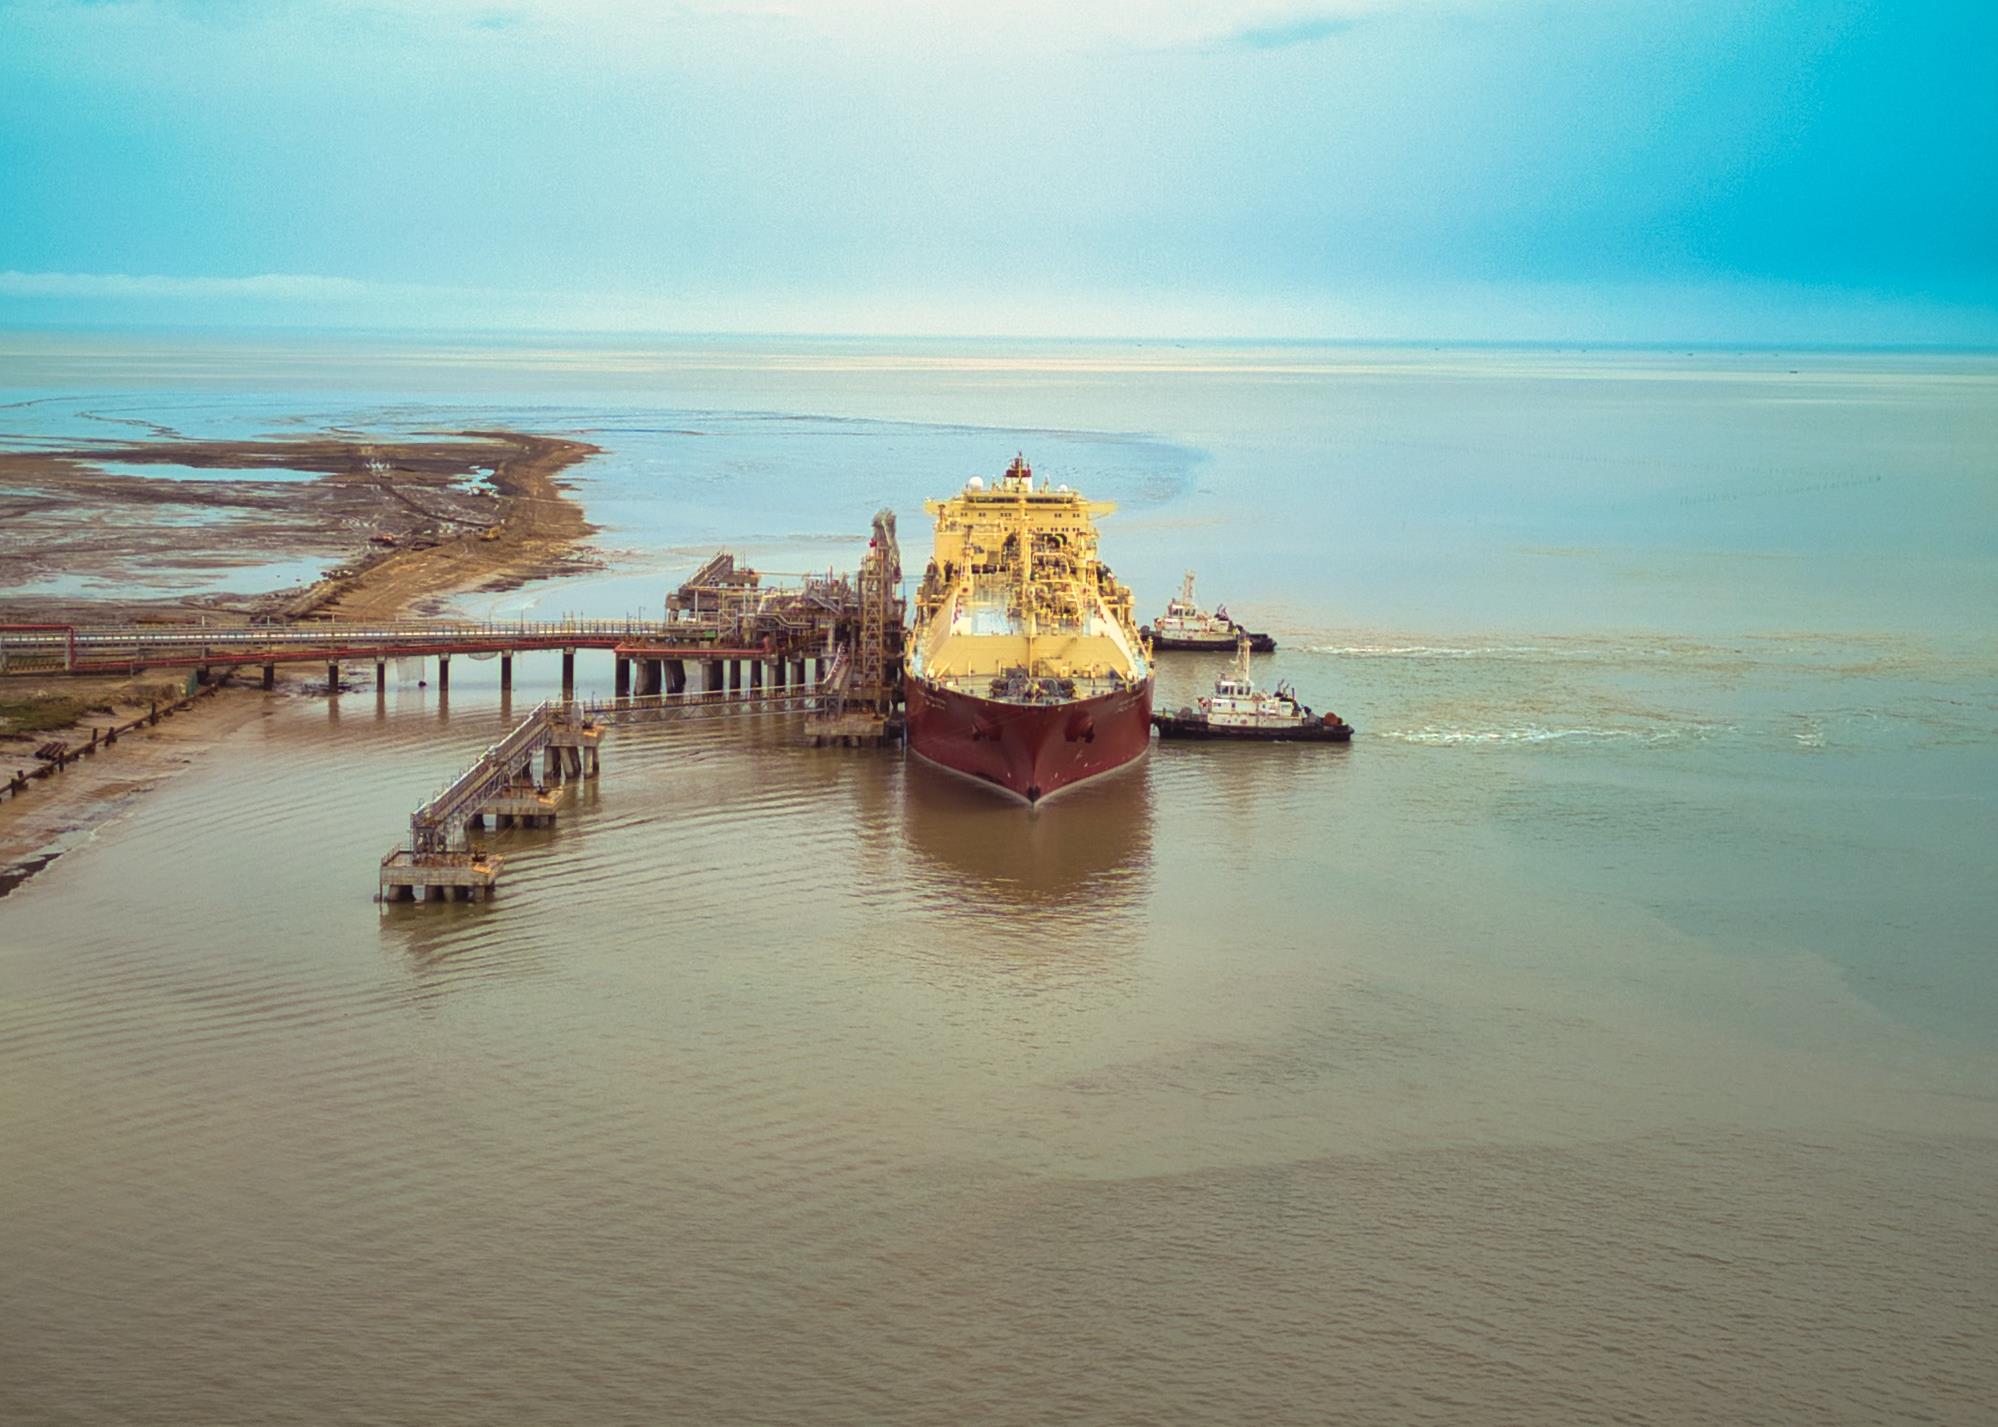
Poland’s Orlen has announced it has terminated one of two long-term contracts for the supply of liquefied natural gas (LNG) by QatarEnergy LNG, a subsidiary of state enterprise QatarEnergy. The termination follows an ongoing force majeure event “resulting in an inability to meet contractual delivery obligations”.
The agreement covered the supply of 1 million tonnes a year (t/y) of LNG, equivalent to approximately 15.3 terawatt-hours, with pricing linked to crude oil quotations. The estimated value of the agreement for 2026 is approximately €570m ($634.9m), Orlen said in a statement on 10 November.
The terminated agreement was originally signed by Polskie Gornictwo Naftowe i Gazownictwo and QatarEnergy on 29 June 2009. Deliveries under the agreement commenced in 2016 and were due to remain in force until 2034, the Polish energy company said.
The agreement will remain in force for a further 60 days following the notice of termination, Orlen said in its statement.
Orlen continues to honour its second agreement with QatarEnergy, which covers deliveries of up to 1 million t/y of LNG until 2034, under a pricing formula linked to gas price quotations.
“The decision to terminate the agreement does not affect the security of gas supplies. Gas production from the company’s own fields, together with its long-term gas supply agreements, ensures full coverage of Orlen Group’s gas requirements,” the company concluded.
It is not clear whether Orlen’s termination of one of its long-term LNG supply agreements with QatarEnergy is related to the Qatari energy giant declaring force majeure on two instances in March this year, when its energy infrastructure was hit in Iranian drone and missile attacks.
Force majeure episodes
On 4 March, QatarEnergy issued force majeure to customers that were affected by its decision to stop production and shipments of LNG and associated products after military attacks on the company’s operating facilities in Ras Laffan Industrial City and Mesaieed Industrial City in Qatar on 2 March.
Later that month, Qatar said Iranian missiles had caused extensive damage at Ras Laffan Industrial City on 18 March, with Saad Sherida Al-Kaabi, QatarEnergy’s CEO and Minister of State for Energy Affairs, saying that the Iranian strikes had knocked out about 17% of its LNG export capacity, causing an estimated $20bn in lost annual revenue.
At least two of Qatar’s 14 LNG trains and one of its two gas-to-liquids facilities were damaged in the Iranian strikes, Al-Kaabi told news agency Reuters at the time.
Repairing damaged assets will sideline 12.8 million t/y of LNG for three to five years, threatening supplies to European and Asian nations, including China and India, according to Al-Kaabi.
As a result, QatarEnergy said it would have to declare force majeure on long-term contracts for up to five years for LNG supplies bound for Italy, Belgium, South Korea and China. Poland was not specifically mentioned at the time.
“These are long-term contracts that we have to declare force majeure. We already declared, but that was a shorter term. Now it is whatever the period is,” Al-Kaabi said in March.
QatarEnergy currently has a nameplate LNG production capacity of 77.5 million t/y, with all its processing trains and export infrastructure located in Ras Laffan Industrial City, which lies about 90 kilometres to the north of Doha and is home to the largest LNG production and export facility in the world.
QatarEnergy’s LNG production capacity is on course to rise to 142 million t/y when the three phases of its $40bn North Field LNG expansion programme are commissioned by the end of the decade. Engineering, procurement and construction works on its North Field East, North Field South and North Field West projects are progressing, with the first phase expected to be operational by the end of this year.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21333808/main2615.jpg -
Riyadh shifts bid deadline for King Salman Stadium works
11 November 2026
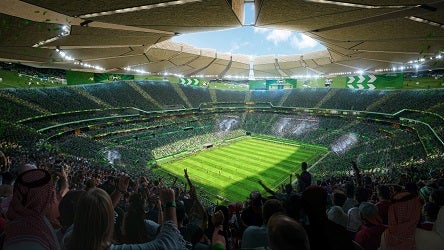
Saudi Arabia’s Sports Ministry has set a deadline of 1 December for a contract covering early works at the King Salman International Stadium in Riyadh.
The tender scope encompasses enabling works, site preparation and initial construction activities. The tender was issued on 11 October, carrying an initial submission deadline of 19 November. Contractors previously submitted prequalification statements for the main design-and-build contract in February.
Designed by US-based architectural firm Populous, the stadium will cover approximately 660,000 square metres (sq m), seat 92,000 spectators and stand adjacent to King Abdulaziz Park. Facilities will feature a 150-seat royal suite, 120 hospitality suites, 300 VIP seats and 2,200 dignitary seats.
The broader masterplan encompasses more than 360,000 sq m of ancillary facilities, featuring two training fields, fan zones, a closed sports hall, an Olympic-sized swimming pool, an athletics track, and outdoor courts for volleyball, basketball and padel.
Scheduled for completion by 2029, the venue will serve as the home base for the Saudi national football team and host the opening match and final of the 2034 Fifa World Cup.
Saudi stadium plans
In August 2024, MEED reported that Saudi Arabia plans to build 11 new stadiums and refurbish four existing venues for the 2034 tournament. Eight venues will be located in Riyadh, four in Jeddah, and one each in Al-Khobar, Abha and Neom.
An additional 10 cities will host team base camps: Al-Baha, Jazan, Taif, Medina, AlUla, Umluj, Tabuk, Hail, Al-Ahsa and Buraidah. Across the kingdom, organisers plan to deploy 134 training sites, comprising 61 existing facilities and 73 new builds.
Saudi Arabia was officially selected to host the 2034 Fifa World Cup during an online convention of member associations at the Fifa Congress on 11 December 2024.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21325461/main.jpg