GCC strives to reach real estate potential
27 June 2024

The real estate sector across the six states that make up the GCC has not yet achieved its full potential when it comes to attracting foreign investment.
This is best illustrated by the region’s largest economy, Saudi Arabia. The kingdom’s Vision 2030 economic diversification strategy includes ambitious targets to increase homeownership among citizens and attract international investors with its recently introduced Premium Residency Visa. The new visa is designed to open up the market to global investors, and while some gains are starting to be made, the market is still at the start of this journey.
Throughout the GCC, real estate markets have demonstrated a degree of resilience and stability following the Covid-19 pandemic, but challenges remain.
Rising borrowing costs and slow-paced reforms have affected the residential sector in the region, although the impact has not been universal. In Kuwait and Saudi Arabia, real estate sales have declined significantly, whereas in Dubai, sales continue apace.
For commercial real estate, the demand for high-quality, sustainable office spaces is a common trend. Businesses are increasingly favouring high-quality Grade A properties, leading to higher rental rates compared to mid- and low-end offices.
The retail sector has benefited from increased consumer activity, particularly during festive seasons. Malls and mixed-use developments have maintained stable rental rates, although some areas, like strip retail rentals, have seen slight declines. This reflects a broader trend of consumer preferences shifting towards more integrated and experiential shopping environments with a keen focus on entertainment.
Meanwhile, the industrial sector has shown robust demand, driven by manufacturing and logistics. High occupancy rates for large and medium-sized warehouses underline the sector’s resilience.
Bahrain
Bahrain’s property market is performing steadily, driven by strategic homebuyers focusing on mid-range properties, as well as a growing demand for luxury waterfront homes.
The market’s attractiveness has been enhanced by masterplanned developments such as Bahrain Bay and Diyar Al-Muharraq, which have achieved a critical mass that means they are now perceived as thriving communities rather than ongoing construction projects.
While project completions are important for confidence, in its Q1 2024 market report, property consultant Savills warns that key project completions such as Onyx Residences, Al-Nasseem Phase 2 Villas and Wadi Al-Riffa could lead to a short-term dip in capital values due to oversupply.
Any possible fall could reverse recent gains. According to Savills, high-end apartment units registered modest 0.3% quarterly growth, averaging BD832 ($2,207.6) a square metre (sq m), while high-end villas have experienced a 4.5% year-on-year decline, averaging BD583/sq m.
Savills reports that the office sector has remained stable, with businesses favouring high-quality Grade A properties, leading to higher rental rates compared to mid- and low-end offices. Demand for Leed-certified spaces and co-working environments is increasing, reflecting environmental, social and governance (ESG) commitments. Grade A properties face mild value corrections due to new developments.
Retail benefited from festive mall footfalls, keeping rental rates stable for malls and mixed-use developments, while strip retail rentals dropped slightly.
Kuwait
The Kuwait real estate sector continued its dismal performance in 2023 due to rising borrowing costs and the slow pace of ongoing reforms. The volume of transactions saw a significant downturn, according to a report by Marmore, a fully owned research subsidiary of Kuwait Financial Centre, Markaz.
Real estate sales dropped to KD2.1bn ($6.7bn) in the first nine months of 2023, reflecting a 26% year-on-year decline from KD2.8bn ($9.1bn). This downturn has affected all segments of the market.
In the residential sector, sales fell by 26% in Q3 2023, totalling KD1.1bn ($3.6bn), down from KD1.4bn ($4.7bn) in the same period of the previous year. The number of transactions also declined by 34% year-on-year. High house prices and borrowing costs have kept demand muted.
The residential rental segment also decreased by 20% year-on-year, reaching KD666m ($2.2bn) in Q3 2023, down from KD831m ($2.7bn) in Q3 2022.
The commercial sector experienced a 37% year-on-year drop in sales, to KD321m ($1bn) in 2023, compared to KD511m ($1.6bn) in 2022. The number of transactions in this sector declined by 35% year-on-year.
In July last year, Kuwait’s National Assembly approved the Housing Development Law and amendments to the Housing and Real Estate Affairs Law that enables private sector involvement – including foreign investment – in developing cities and residential areas, and aims to prevent land monopolies. These measures could positively influence the country’s real estate market this year.
Oman
After a couple of tough years during and immediately following the Covid-19 pandemic, Oman is again capitalising on its real estate potential, with new projects attracting interest from residents and investors.
The sultanate’s real estate market in 2024 is buoyed by a combination of increasing expatriate populations, attractive pricing and favourable government policies.
A recent report by property consultancy Cavendish Maxwell highlights the contribution of the government’s strategic reforms and investments in infrastructure as critical drivers for the growth of the real estate sector in the country. These have included the easing of foreign ownership restrictions, the introduction of new real estate laws and enhanced regulatory frameworks that have created a more transparent and attractive market for investors.
Longer term, Muscat has set targets for the economy that will support the real estate sector. Under Oman’s Vision 2040 plan, the government aims to attract 11 million visitors annually by 2040, which will boost the tourism industry. Investments in economic zones, renewable energy, manufacturing and tourism projects will contribute to the growth of the construction industry, including the real estate sector.
Oman is developing new projects in response to the long-term opportunities that this growth will create. These include the Sultan Haitham City project to the west of Muscat and a masterplanned mountain development on Jebel Akhdar, launched earlier this year.
Qatar
Following a period of fluctuation around the 2022 Fifa World Cup, Qatar’s real estate market is showing signs of stability, according to Cushman & Wakefield. The number of real estate sales transactions surged by 17.3% in January and February this year compared to the same period in 2023, with an overall value increase of 4.1%.
The declining trend in residential sales transactions seen in 2023, when a drop of 16.2% was recorded compared to 2022, has been reversed in the first two months of this year. Residential sales transactions have increased by 30% compared to the same period last year, reflecting a significant 46% rise in transaction value.
In the rental segment, the early months of 2024 have highlighted a growing disparity between newly constructed residential projects and those built over a decade ago. Tenants are increasingly drawn to modern, well-managed serviced appartments.
Office leasing activity declined in the first quarter of 2024, following a good run at the end of 2023. Over the past six months, more than 70,000 sq m of Grade A office space has been reserved, leading to a decrease in availability in areas including Lusail and Msheireb.
In the first quarter of 2024, hotel room supply in Qatar reached 38,000, which marks a 45% increase in supply over the past five years.
Despite initial concerns of oversupply, Qatar’s hotel industry has experienced a significant boost due to a rise in tourist arrivals since January. Hotel occupancy rates also soared to 84% in January and 85% in February, reaching their highest levels since 2015.
Saudi Arabia
Saudi Arabia’s real estate sector is moving into a new phase as it aims to build on its recent successes and targets foreign investment more proactively.
Real estate forms a key part of the kingdom’s Vision 2030, which aims to increase homeownership by Saudi nationals to 70% by 2030, from 63.7% in 2023.
The residential real estate market in Saudi Arabia is experiencing robust demand, especially in the major cities of Riyadh, Jeddah and Dammam. In Q1 2024, Riyadh recorded a 77% year-on-year increase in sales transactions, while Jeddah saw a 92.9% rise. This surge in activity underscores the strong appetite for residential properties in these urban centres.
Despite this growth, the market faces challenges such as affordability and a shortage of appropriately priced homes.
Historically, foreign ownership restrictions have limited international investment in Saudi real estate. However, the new visa scheme signifies a pivotal shift, encouraging a diverse pool of global talents and investors to contribute to the local economy. This move is expected to drive up property values in premium segments and spur the development of luxury real estate projects.
“The real estate market in Saudi Arabia has long anticipated a change in the foreign ownership rules. A significant milestone was reached at the start of the year when a raft of new Premium Residency Visa options were unveiled, including a real estate ownership-linked visa, which is likely to pave the way for international buyers and investors,” says real estate consultancy Knight Frank in its recent Destination Saudi Report.
This move is expected to create supplemental demand from foreign investors that have been waiting for changes in the kingdom’s ownership laws.
Saudi Arabia’s new Premium Residency Visas include a real estate ownership-linked option that is designed to attract foreign investment by allowing non-Saudis to own property worth at least SR4m ($1.1m).
This policy shift marks a strategic opening up of the market to international investors and affluent expatriates and could potentially boost high-value transactions and increase the demand for luxury residential properties in the kingdom.
One of the early focus areas for new investment inflows could be the holy cities of Mecca and Medina.
The demand for real estate in Saudi Arabia is also being driven by high-net-worth individuals (HNWI), particularly those from Muslim-majority countries. Surveys indicate that 82% of international HNWI buyers are keen to own real estate in the kingdom, with significant interest in the two holy cities.
These buyers view Saudi Arabia as a good investment opportunity, with cultural and religious reasons also playing a crucial role in their decision-making, Knight Frank says in its Destination Saudi report.
UAE
The UAE’s real estate market started 2024 on a robust note, showing increased activity levels across all sectors during the first quarter, according to the latest report by property consultant CBRE.
The report shows that the total transaction volumes in Dubai’s residential market reached 35,310 in Q1 2024. This is the highest total ever recorded in the first quarter of the year, marking an increase of 20.5% from the previous year.
Off-plan transactions in Dubai also increased by 23.9%, whereas secondary market transactions rose by 15.2% during the same period.
The CBRE report also outlined that in the first quarter of 2024, Dubai’s residential market witnessed an increase in average prices of 20.7% by March 2024 compared to the previous year.
In Abu Dhabi, average apartment prices rose by 4.3% and villa prices saw an increase of 2.3% during the same period.
In the commercial sector, the total number of rental registrations in the office sector increased to 46,850, a hike of 35.8% compared to the previous year, according to data from Dubai Land Department.
In Abu Dhabi, an increased activity level in the commercial space sector has taken the occupancy rate to 94% in the first quarter of 2024, up from the 92.5% registered in the same period last year. The increased occupancy levels have led to a growth in rentals, where Prime, Grade A and Grade B rents posted average growth rates of 6.6%, 3.4% and 9.7%, respectively.
The hospitality sector also noted improvement. The number of international visitors to Dubai totalled 5.2 million in the period from January to March 2024, up by 10.2% from a year earlier. The total number of hotel guests in Abu Dhabi stood at 1.3 million, a growth of 22% compared to Q1 2023.
In the retail sector, leasing activity lagged in Abu Dhabi as 7,779 rental contracts were registered in the first quarter of 2024, marking a decline of 8.1% compared to Q1 2023. Dubai witnessed a marginal increase of 0.2% in retail registrations compared to same period last year, recording a total of 23,139.
Finally, the UAE’s industrial and logistics sector also recorded positive leasing activity, with the total number of rental registrations in Abu Dhabi and Dubai increasing by 4.7% and 3.2%, respectively, compared to the same period last year.
Additional reporting by Yasir Iqbal

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Contractors compete for Riyadh airport Terminal 6 work
2 November 2026
-
 Contractors prepare bids for Morocco power line
2 November 2026
-
 Adnoc Onshore allows more time for Bab gas cap well tie-in bids
2 November 2026
-
 Gulf ministers insist Hormuz is still essential
2 November 2026
-
 Bahrain’s Gateway Gulf brings $20bn of deals
2 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
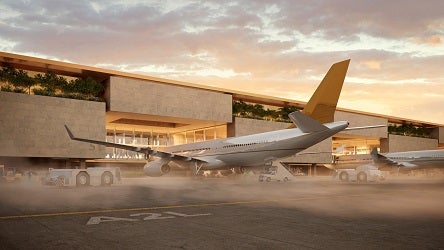
Contractors compete for Riyadh airport Terminal 6 work
2 November 2026
Contractors are preparing bids for the main construction contract for Terminal 6 at King Salman International airport (KSIA) in Riyadh.
MEED understands that the consortiums have been given until January to submit their proposals.
The participating consortiums are:
- Al-Gihaz Holding / TAV Construction / Webuild (local/Turkiye/Italy)
- Modern Building Leaders / Powerchina / Metallurgical Corporation of China (loca/China/China)
- UCC Holding / Consolidated Contractors Company (Qatar/Greece)
Last month, MEED exclusively reported that contractor teams have completed the early contractor involvement phase of the project.
Under the completed phase, the shortlisted teams submitted detailed construction methodologies and technical design proposals.
King Salman International Airport Development Company (KSIADC) is a subsidiary of Saudi sovereign wealth vehicle the Public Investment Fund.
Terminal 6 is planned to boost the airport’s annual capacity by 40 million passengers. KSIADC aims to complete the terminal ahead of Expo 2030 Riyadh.
In May 2025, MEED reported that US-based Bechtel had been appointed as delivery partner for the passenger terminals at KSIA.
UK-based Foster + Partners designed the masterplan, including the terminals, six parallel runways and a multi-asset real estate district.
US-based engineering firm Jacobs is providing specialist consultancy services for the masterplan and runway design, while UK-headquartered Mace is acting as delivery partner for the broader development. Local firm Nera secured the airspace design consultancy contract.
The KSIA project covers about 57 square kilometres (sq km) and incorporates the existing terminals at King Khalid International airport. The scheme will feature 12 sq km of airport support facilities, residential and recreational zones, retail assets and logistics parks.
The development is targeted to handle up to 120 million passengers a year by 2030 and 185 million passengers by 2050, in addition to an annual cargo throughput of 3.5 million tonnes by 2050.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21087339/main.jpg -
Contractors prepare bids for Morocco power line
2 November 2026
Contractors are preparing bids for a 160-kilometre (km), 400kV transmission line linking Guercif and Fes East in Morocco, following a site visit on 1 October.
The project is being developed by the Office National de l'Electricite et de l'Eau Potable (Onee) to connect the Saka solar photovoltaic power plant to the national electricity grid.
According to sources, at least eight contractors attended the site visit last month, including:
- Butec (Lebanon)
- CEEC Northeast Electric No.2 (China)
- Cegelec (France)
- EPME Electric (Morocco)
- Hideleco (Egypt)
- Kec International (India)
- PowerChina (China)
- Transrail (India)
The project comprises two lots. The first involves a 90km transmission line between Guercif and Taza, while the second covers a 70km section between Taza and Fes East.
The scope of work includes the construction of tower foundations, installation of transmission supports and conductors, and associated high-voltage equipment. It also includes optical fibre cables for communications and monitoring, access roads and other supporting infrastructure.
The tender was issued in September with bids originally due by 21 October. The deadline has now been extended to 25 November.
The project is part of a wider programme by Onee to expand Morocco's electricity transmission network and accommodate additional renewable energy capacity.
In June, the utility commissioned a 274km, 400kV transmission line linking Chemaia and Mediouna, near Casablanca.
Onee plans to expand its high- and extra-high-voltage transmission network from more than 30,700km to 37,000km by 2030.
In August, it approved a $26.4bn investment programme for the 2026-30 period, covering electricity and drinking water infrastructure.
The programme has allocated about $21.9bn to electricity projects and $4.5bn to drinking water infrastructure, with about 72% of the investment to be financed by the private sector, according to Onee.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21083507/main1257.jpg -
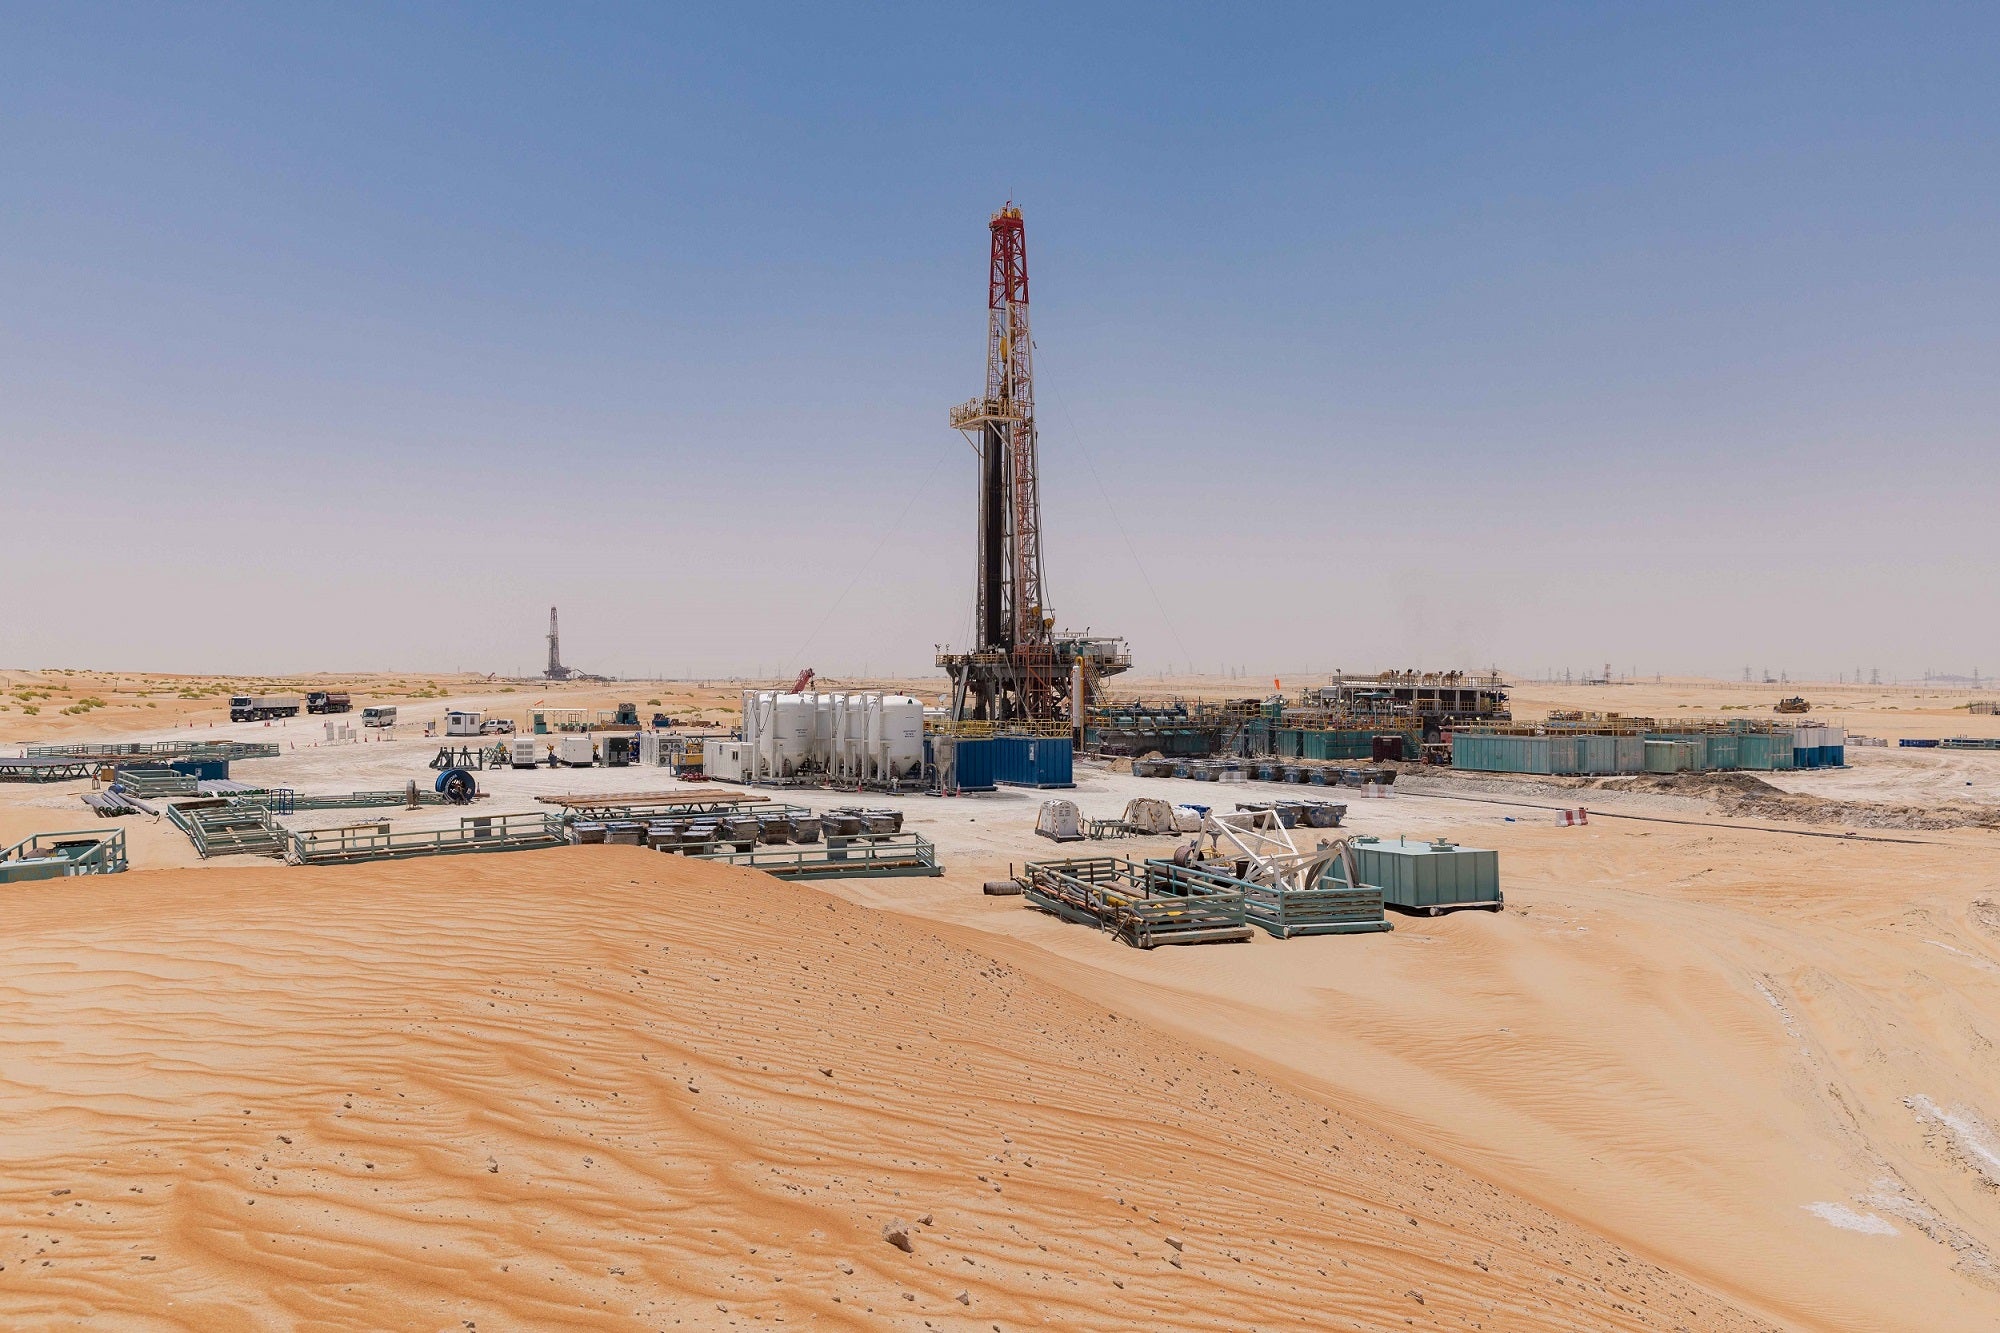
Adnoc Onshore allows more time for Bab gas cap well tie-in bids
2 November 2026
The onshore business of Abu Dhabi National Oil Company (Adnoc Onshore) has allowed contractors more time to prepare proposals for a project to tie in gas-producing and injection wells at the gas cap reservoirs of Abu Dhabi’s onshore Bab field.
The well tie-in scope, estimated to be worth more than $800m, forms part of Adnoc Group’s wider integrated Bab gas cap development programme.
The overall programme is being led and overseen by Adnoc Gas, another Adnoc Group subsidiary. Its central element is the construction of gas-processing infrastructure to handle incremental gas output expected from developing the Bab gas caps.
Adnoc Onshore issued the main tender for engineering, procurement and construction (EPC) works on the project in late September, MEED previously reported.
Contractors have been given until 16 November to submit technical bids for the project, according to sources. The previous deadline was 29 October.
MEED previously reported that Adnoc Onshore issued an expressions of interest (EoI) notice for the Bab gas production and injector well tie-in project on 13 May, with contractors submitting responses by 20 May.
The scope of work on the project covers the following:
- Tie-in of 99 new wells from Bab gas cap reservoirs KH-2, SH-1 and LK-1 (60 gas producers and 39 gas injectors);
- Installation of well gathering structures: 10 gas pads, six well bays and three virtual pads;
- Installation of a gas gathering network and a gas injection network;
- Rerouting of the LK-3 production from the existing trunkline in Remote Manifold Station 3 (RMS-3) to the project’s production trunkline, Bab Gas TL-2;
- Demolition of the existing 10-inch trunkline from RMS-3 to onshore gas development phase one.
In the EoI document, Adnoc Onshore said it intends to award the EPC contract in the last quarter of the year, with a 45-month duration of works.
Bab gas cap project infrastructure
As part of its 2030 upstream production increase goals, Adnoc Group is working to extract gas from four underdeveloped gas cap reservoirs at the Bab onshore field development – Thammama A, Thammama B, Thammama F and Thammama H.
While the Thammama A, B and H reservoirs are estimated to collectively produce 1.45 billion cubic feet a day (cf/d) of gas, output from the Thammama F gas cap is expected to be at a rate of 396 million cf/d.
Existing trains at the Habshan processing complex in Abu Dhabi will be unable to handle the new gas volumes. Therefore, Adnoc Gas is required to build new facilities to process an additional volume of up to 1.85 billion cf/d of raw gas.
Adnoc Gas is planning to build a gas processing plant in the Bab area, about 170 kilometres from Abu Dhabi, along with associated pipeline networks and other ancillary units, as part of the broader Bab gas cap development project. It has divided the EPC scope of work on the project into four packages:
- EPC package 1 – Main Bab gas cap plant
- EPC package 2 – Early civil works
- EPC package 3 – Pipelines
- EPC package 4 – Non-process area works
Abu Dhabi Securities Exchange-listed Adnoc Gas issued the tender for the main Bab gas cap plant on 25 June and set an initial deadline of 17 July for contractors to submit technical bids. The company then extended the technical bid submission deadline by four months, until 16 November, MEED previously reported.
Following a reshuffle of the consortiums gearing up to bid for the main Bab gas plant EPC package, estimated to be worth more than $6bn, the following teams have formed to compete in the main contract tendering round:
- Larsen & Toubro Energy Hydrocarbon (India) + Petrofac Emirates (UAE)
- Technip Energies (France) + JGC Corporation (Japan) + Sinopec (China)
- Tecnimont (Italy) + China Petroleum Engineering and Construction Corporation (CPECC)
The other three packages of the Bab gas cap project are also in the main contract tendering stages.
Prior to issuing the EoIs for the project packages, Adnoc Gas completed an early engagement process with contractors in September and October last year, as MEED previously reported.
In December last year, Adnoc Gas awarded the front-end engineering and design (feed) works for the development project to Australia-based consultancy Worley. The feed contract has a duration of more than 1.2 million man-hours, making it the largest-ever engineering job awarded by Adnoc Gas.
Bab Gas Cap concession
In addition to Adnoc Gas overseeing the main EPC tendering exercise for the gas processing plant, Abu Dhabi’s Supreme Council for Financial and Economic Affairs (SCFEA) awarded concession agreements in June for the development and production of the Bab gas cap reserve.
Adnoc will hold the majority 60% participating interest in the concession. The remaining stakes will be held by France’s TotalEnergies (10%), the UK’s BP (10%), China National Petroleum Corporation International (8%), Japan Oil Development Company Onshore (5%), China ZhenHua Oil (4%) and Korea GS E&P (3%).
According to the SCFEA, the Bab gas cap development and production concession represents the largest gas cap development project of its kind globally, the Abu Dhabi Media Office said in a report.
A gas cap refers to the free natural gas that sits above an underlying oil reservoir – in this case, the Bab onshore oil field in Abu Dhabi.
The project, operated by Adnoc Onshore, is expected to have a production capacity of approximately 1.5 billion cf/d of natural gas, equivalent to about 15% of Adnoc Gas’ total operational gas processing capacity.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21083343/main.jpg -
Gulf ministers insist Hormuz is still essential
2 November 2026
Register for MEED’s 14-day trial access
Senior Gulf officials have rejected suggestions that new pipelines and rail links will allow the region to do without the Strait of Hormuz, arguing that the waterway will remain essential to the GCC and the global economy.
Speaking at the Gateway Gulf investment forum in Manama on 1 November, GCC secretary-general Jasem Mohamed Albudaiwi said keeping the strait open is the responsibility of the international community, not of any one country or group of partners. "We hear some voices that maybe we should seek alternatives to Hormuz," he said. "Fine, we will get the pipelines. We will get the GCC railway. But that doesn't mean Hormuz is nobody's business."
Albudaiwi called for the strait to remain open in line with international law, including the 1982 UN Convention on the Law of the Sea.
Shipping through the strait has been severely restricted since the US and Israel launched strikes on Iran on 28 February and Iran retaliated with attacks on GCC states and commercial vessels.
Bahrain's Finance & National Economy Minister, Sheikh Salman Bin Khalifa Al-Khalifa, said building redundancy makes sense, but treating the strait as dispensable does not. He said the waterway carries 30% of global liquefied natural gas (LNG) exports, 20% of aluminium exports and 30% of fertiliser exports. "Any thinking about the alternative of Hormuz, as in we won't need it, is illogical, because we will need it for the world economy," he said.
UAE Economy & Tourism Minister Abdulla Bin Touq Al-Marri said that "Hormuz matters, and Hormuz will keep mattering", adding that an economy dependent on a single trade route is exposed if that route closes.
Sheikh Salman said the crisis has compressed years of GCC customs negotiations into weeks. During the conflict, containers cleared at Jeddah with final destinations in Bahrain or Kuwait moved on without further checks, and the same applied to cargo routed through Salalah and Fujairah, he said. GCC ministers have since agreed to make these emergency measures permanent.
He also cited Gulf Air operating out of Saudi airports for more than 40 days without a written agreement, and a $5bn swap between the UAE and Bahraini central banks to stabilise currencies.
Bin Touq said the bloc should use 2027 and 2028 to push through reforms, including removing remaining customs barriers between member states.
Albudaiwi said GCC leaders meeting in Jeddah on 28 April had tasked the secretariat with advancing water connectivity, expanding the GCC electricity grid, planning new logistics infrastructure including ports, accelerating the GCC railway and enhancing oil and gas pipeline links.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21080732/main4958.jpg -
Bahrain’s Gateway Gulf brings $20bn of deals
2 November 2026
More than 110 announcements worth over $20bn will be made at the Gateway Gulf Investment Forum in Bahrain, according to the country's finance minister.
"Over the next two days at Gateway Gulf, more than 110 announcements worth over $20bn will be made," Sheikh Salman Bin Khalifa Al-Khalifa, Finance & National Economy Minister, said at the opening of the forum's fourth edition on 1 November in Bahrain.
He said the announcements will cover new partnerships, investments, projects and jobs. Sheikh Salman addressed an audience that included Bahrain's Crown Prince and Prime Minister, Prince Salman Bin Hamad Al-Khalifa.
The minister said the region's economies have been "tested as never before" since the previous edition of the forum a year earlier.
"In the face of unprecedented attacks, we did not waver," he said. He added that Bahrain has chosen to work more closely with its allies and partners to defend what it has built.
Sheikh Salman said the Gulf economy has grown to $2.4tn in GDP. Non-oil sectors account for more than 86% of Bahrain's GDP and more than 77% across the Gulf, he said.
He said Gulf banks hold more than $4tn in assets, while the region's sovereign wealth funds manage more than $5tn of investments. "These numbers describe a region that has chosen to build a more stable, a more prosperous future for its people," he said. "Bahrain is the gateway to that region."
The minister said Bahrain is focusing on regulation, infrastructure and people to attract investment.
He said the country has developed a regulatory framework over several decades that is "clear, modern and fast", allowing investors to commit with confidence.
On infrastructure, he highlighted logistics, connectivity, digital networks and industrial land as areas where Bahrain is building the foundations for businesses to expand. He also named finance, logistics, tourism, manufacturing, technology and telecommunications, and oil and gas as the sectors into which he expects domestic, regional and international capital to flow.
He said the investments will create jobs for young graduates and support the growth of family businesses.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21080593/main2015.jpg