GCC battery storage pipeline hits over 55GWh
28 February 2025
 Analysis
Jennifer Aguinaldo
Energy & technology editor

The battery energy storage system (bess) plant project pipeline in the GCC region – mainly in Saudi Arabia and the UAE – has reached 55.4 gigawatt-hours (GWh) of estimated rated capacity.
Data from MEED and regional projects tracker MEED Projects indicates that schemes with a total capacity of about 21.7GWh are under construction, primarily in Saudi Arabia, while bess plants in the pre-execution phase have an estimated cumulative rated capacity of 33.8GWh.
This substantial pipeline has been built over the past two to three years, when a total of 3.9GWh of capacity was built in Saudi Arabia through the 1.3GWh Red Sea multi-utility project and the recently completed 2.6GWh battery energy storage plant by Saudi Arabia's National Grid.
"The main energy storage driver across the GCC region is the rapid deployment of low-cost solar power to meet growing demand," notes Marek Kubik, a Saudi Arabia-based industry expert.
"As photovoltaic (PV) produces power only in the day and is a non-synchronous form of power, this brings with it certain balancing, ramping and stability challenges.
"Bess is needed for storing and shifting solar power from day to night, to reduce congestion and improve utilisation on the transmission system, as well as providing stability services to support stable grid operations," says Kubik.
Capacity ramp-up
With an estimated 775MW/3.9GWh of deployed capacity at the end of 2024, the GCC region accounts for a small proportion of the global deployment of about 160GW or 363GWh, according to the Volta Foundation.
The global not-for-profit group said global bess installations last year accounted for more than 45% of the total cumulative global capacity.
The region is poised to catch up with the rest of the world, however. Saudi Arabia's Bisha bess plant is one of 17 projects globally with a capacity of over 1GWh that entered operations in 2024.
A total of 21.7GWh of capacity is under construction in Saudi Arabia and is expected to be completed by the end of the year, with more under way.
Such growth will likely overtake the 55% year-on-year growth observed by the Volta Foundation.
The GCC region’s first major bess independent power producer (IPP) scheme was integrated into Red Sea Global’s multi-utility package in Saudi Arabia.
Developed by Saudi utility developer Acwa Power and built by China’s Huawei Digital, the 1,300 megawatt-hour (MWh) facility caters to the 28,000 square-kilometre “regenerative” tourism project on the west coast of the kingdom, which is being powered 100% by clean energy.
A bess facility with a capacity of 760MWh is also included in a similar multi-utility package for Red Sea Global’s sister development, Amaala.
The 2.6GWh Bisha represents an important milestone, ushering the kingdom onto the list of the world's top locations for lithium iron phosphate (LFP)-based bess.
So far, every utility or grid operator in the GCC, Morocco and Jordan plans to procure or has started to procure bess capacity independently, to balance their grid as electricity demand and renewable energy capacity increase, or as part of a solar power plant scheme.
In the absence of viable hydropower capacity, which is the main energy storage capacity in non-water-scarce regions, or thermal energy storage systems like molten salt, bess is emerging as the best alternative to enhance the flexibility of existing energy or electricity systems as sources increasingly diversify.
Abu Dhabi state utility Emirates Water & Electricity Company (Ewec) received 93 expressions of interest and prequalified more than two dozen companies to bid individually or as members of consortiums for its first pair of bess plants, which will have a capacity of up to 800MWh.
In January, Ewec and Abu Dhabi Future Energy Company (Masdar) announced a project that aims to convert solar power into base load capacity by coupling a 5GW solar PV plant with a 19GWh battery energy storage facility in Abu Dhabi.
Falling lithium prices and oversupply
The need for grid flexibility and a steep fall in the price of lithium – the main raw material for the dominant battery technology – has helped utilities to move forward with their plans to procure bess, which was considered cost-prohibitive until a year ago.
According to a BloombergNEF (BNEF) report in December, lithium-ion battery pack prices dropped 20% from 2023, to a record-low of $115 a kilowatt-hour.
Factors driving the decline include cell manufacturing overcapacity, economies of scale, low metal and component prices, the adoption of lower-cost LFP batteries and a slowdown in electric vehicle (EV) sales growth.
In the past two years, battery manufacturers have expanded production capacity in anticipation of surging demand for batteries in the EV and stationary storage sectors.
According to BNEF, overcapacity is rife, with 3.1 terawatt-hours of fully commissioned battery-cell manufacturing capacity globally, which is more than 2.5 times the annual demand for lithium-ion batteries in 2024.
It added that while demand in all sectors saw year-on-year growth, the EV market – the biggest demand driver for batteries – grew more slowly than in recent years.
In contrast, stationary storage markets have taken off, with strong competition in cell and system providers, especially in China.
Completed and under-construction bess plants in the GCC are all supplied by Chinese battery cell and system providers. BYD and Sungow account for 59% and 36% of completed and under-construction battery energy storage plants in Saudi Arabia, respectively, while Huawei accounts for the rest.
Contemporary Amperex Technology Company (CATL) will be supplying the battery cell and systems for Abu Dhabi's round-the-clock 1GW solar project.
Prices are expected to fall further, which will likely accelerate GCC deployments.
Some experts predict the prices could drop to as low as $50/kWh-$25/kWh and, at best, to as low as $10/kWh by the end of the decade, subject to extrapolating current battery learning rates of about 25% for every doubling of capacity.
Longer-duration battery cells
Despite their expected widespread deployment, there are concerns that batteries providing up to six hours of storage may not be sufficient to address the peak electricity demand in most GCC states.
Demand in the GCC states peaks between 6pm and 6am, when air-conditioning systems, street lighting and other home appliances are turned on, and where there is little wind capacity to supply renewable power.
Nevertheless, a staged approach to bess deployment is necessary to get to a fully net-renewable electricity system, says Kubik.
"Around the world, this is approached in a staged manner and bess of increasing duration is added over time, as the depth of renewable penetration increases," he says.
"The GCC has, to an extent, leapfrogged other markets by starting with four-hour to six-hour bess, but over time this need will grow to about eight- to 10-hours, which is enough to move to more or less a ‘baseload’ around-the-clock solar profile. As LFP costs continue to fall, longer-duration systems are rapidly becoming more economic."
 READ MEED’s YEARBOOK 2025
MEED’s 16th highly prized flagship Yearbook publication is available to read, offering subscribers analysis on the outlook for the Mena region’s major markets.
Published on 31 December 2024 and distributed to senior decision-makers in the region and around the world, the MEED Yearbook 2025 includes:
|
> PROJECTS: Another bumper year for Mena projects
> GIGAPROJECTS INDEX: Gigaproject spending finds a level
> INFRASTRUCTURE: Dubai focuses on infrastructure
> US POLITICS: Donald Trump’s win presages shake-up of global politics
> REGIONAL ALLIANCES: Middle East’s evolving alliances continue to shift
> DOWNSTREAM: Regional downstream sector prepares for consolidation
> CONSTRUCTION: Bigger is better for construction
> TRANSPORT: Transport projects driven by key trends
> PROJECTS: Gulf projects index continues ascension
> CONTRACTS: Mena projects market set to break records in 2024
|

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Houthi escalation targets Saudi airports
12 October 2026
-
 Egypt and Saudi Arabia sign oil and gas deal
12 October 2026
-
 JGC yet to return evacuated workers to Basra refinery
12 October 2026
-
 Contractors prepare Jordan stadium prequalification
12 October 2026
-
 Abu Dhabi plans Mussafah road upgrades
12 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Houthi escalation targets Saudi airports
12 October 2026
Yemen’s Houthis have placed Saudi Arabia’s civil aviation infrastructure at the centre of their campaign against the kingdom. Two strikes on King Khalid International airport in Riyadh over the weekend killed 13 people and injured 320.
The deadlier attack hit a passenger terminal on the afternoon of 10 October. The General Authority of Civil Aviation (Gaca) said it killed 12 people, including four Saudi citizens, and injured 309. Airport operations were suspended pending a damage assessment.
A second strike hit Terminal 4 on the afternoon of 11 October, sparking a fire that killed a Pakistani resident and injured 11 others, according to Gaca. The Saudi-led coalition reported intercepting a cruise missile near the airport that afternoon. Gaca also reported an attack on King Fahd International airport in Dammam that evening, following a coalition report of a projectile falling near the facility the previous night.
The weekend strikes followed attacks on Abha International airport on 6 October and on King Khalid International airport on 7 and 8 October, the last of which included a strike on a Saudia aircraft. Gaca figures put the toll from the week’s attacks on Saudi airports at 19 dead and more than 350 injured.
The Houthis said they would continue operations inside the kingdom and that all Saudi airports were potential targets, with the exception of those serving the holy cities. The group says it is acting in response to Riyadh’s support for Yemeni government forces and a Saudi air strike on Sanaa airport. It has also claimed attacks on Saudi oil facilities, which Saudi authorities have not confirmed.
Aviation exposure
The attacks strike a sector central to the kingdom’s diversification plans. King Khalid International airport’s existing terminals are to be absorbed into King Salman International airport (KSIA), a 57-square-kilometre development with six parallel runways targeting a capacity of 120 million passengers by 2030 and 185 million by 2050.
Procurement on KSIA has gathered pace this year. In July, a joint venture of China Civil Engineering Construction Corporation and Dammam-based Mofarreh AlHarbi & Partners won an estimated SR800m ($213m) contract for enabling and substructure works on Terminal 6, which will add capacity for 40 million passengers. Turkish contractor IC Ictas and Saudi Arabia’s Al-Rashid Trading & Contracting recently secured a SR800m ($213m) contract for the airport’s Private Aviation Terminal.
Government-owned Saudi Royal Aviation set 8 October as the bid deadline for an estimated SR3bn ($800m) contract to build an aviation complex within the KSIA masterplan, the same day the Houthis struck King Khalid International airport and a Saudia aircraft.
Airlines have already adjusted. Flydubai cancelled flights to Riyadh and Yanbu up to 10 October and to Abha up to 11 October, and Etihad Airways reported extended delays on its Abu Dhabi to Riyadh service after the airport closed on 8 October. The UK Foreign Office has advised against all travel to areas within 10km of the Yemeni border.
Market reaction
The Saudi stock market’s response has been muted so far. The Tadawul main index fell 15.54 points to close at 10,360.74 on 11 October, the first trading session after the Saturday attack, with turnover of SR2.6bn ($693m). The session closed before the second strike on King Khalid International airport and the attack on Dammam, and Monday’s trading will be the first to reflect the full weekend.
The weekend also brought a separate maritime incident. UK Maritime Trade Operations said an oil tanker was struck by an unidentified projectile in the Strait of Hormuz on 11 October, with its crew reported safe.
Diplomatic response
The coalition described the 10 October attack as a war crime and said it would respond decisively. It said on 10 October that it had destroyed 136 military targets in Houthi-controlled areas and was working to dismantle the group’s ballistic missile network.
Egypt, Pakistan and Turkiye joined Saudi Arabia in an R4 group statement condemning the attacks and supporting measures taken by the kingdom in response. The Arab League also voiced its support for Saudi Arabia. On 11 October, Iran’s foreign minister spoke by telephone with his Saudi counterpart, Prince Faisal Bin Farhan, to discuss the escalation. The US and UK have also signalled the possibility of further support for the kingdom.
The escalation comes against the backdrop of the regional conflict, which has drawn Saudi Arabia into a renewed Yemen front after several years of relative calm following the 2022 ceasefire. The extent of the damage at King Khalid International airport, which Gaca is still assessing, and the speed at which international carriers resume full schedules will determine how far the attacks disrupt the kingdom’s aviation programme.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20505600/main.gif -
Egypt and Saudi Arabia sign oil and gas deal
12 October 2026
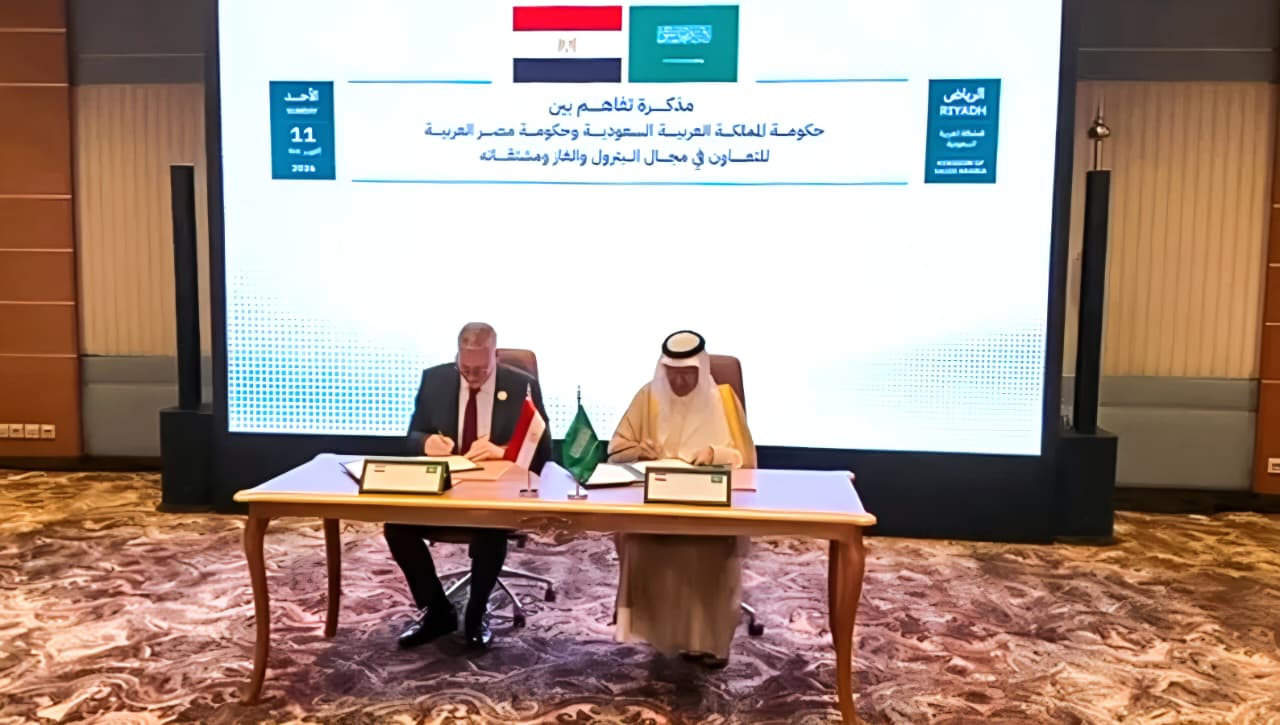
Egypt and Saudi Arabia have signed an agreement to strengthen cooperation in the oil, natural gas and petrochemicals sectors, according to a statement from Egypt’s Ministry of Petroleum & Mineral Resources.
The memorandum of understanding (MoU) was signed in Riyadh by Karim Badawi, Egypt’s minister of petroleum and mineral resources, and Abdulaziz Bin Salman, Saudi Arabia’s minister of energy.
Under the agreement, both sides will enhance cooperation in trading, transporting, storing and distributing crude oil, petroleum products and natural gas.
They will also expand cooperation on developing the infrastructure and logistics services that support these activities.
In its statement, Egypt’s Ministry of Petroleum & Mineral Resources said: “These efforts will contribute to improving energy market efficiency, enhancing the resilience and reliability of supply chains, and strengthening energy security.”
The MoU also provides for expanded cooperation in exchanging expertise and best practices in operating and developing fuel stations, as well as in transporting and tracking petroleum products and liquefied petroleum gas cylinders.
Additionally, the agreement seeks to explore investment opportunities in joint projects and promote exports.
The latest agreement comes as Egypt becomes an increasingly important export route for Saudi Arabia.
Due to disruptions and security risks affecting shipments through the Strait of Hormuz, Saudi Arabia has been redirecting crude exports via its East-West Pipeline to Yanbu on the Red Sea.
Meanwhile, the Bab El-Mandeb Strait, at the southern end of the Red Sea, has also become a security concern due to military activity in Yemen. Egypt offers an alternative route through the Sumed pipeline, which runs from Ain Sokhna on the Red Sea to Sidi Kerir on the Mediterranean.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20503239/main.jpeg -
JGC yet to return evacuated workers to Basra refinery
12 October 2026
Japan’s JGC has yet to bring evacuated workers back to the Basra refinery project in Iraq, according to industry sources.
JGC evacuated its personnel from the site in the southern oil hub of Basra following the start of the regional conflict on 28 February, when the US and Israel attacked Iran.
The evacuation halted work on the project, which was in its final construction stage.
On 14 August 2026, Iraq’s Ministry of Oil announced that it had signed an agreement with JGC to resume work on the fluid catalytic cracking (FCC) project at Basra refinery.
One source said: “Even though the agreement to bring the evacuated workers back was signed about two months ago, there is still no sign of the evacuated workers on the project site.
“It is possible that they will return soon, but it is hard to tell what will happen next in the current security environment.”
Earlier this month, Iraq’s Ministry of Oil said it met with Japanese officials to discuss plans to commission the FCC unit under the Basra refinery upgrade project.
The statement did not say when the evacuated JGC workers would return to the project site.
Strategic project
Iraq’s state-owned South Refineries Company (SRC) sent JGC notice of the main contract award for the FCC package of the Basra refinery upgrade project in August 2020.
JGC was awarded the contract in consortium with South Korea’s Hyundai E&C.
The official contract signing ceremony was held in Baghdad on 1 October 2020.
The contract awarded to JGC, which uses the engineering, procurement, construction and commissioning model, was worth $3.78bn.
The FCC package is part of a broader project to upgrade the Basra refinery.
The project site is located about 12 kilometres east of Iraq’s southern city of Basra.
The wider upgrade project involves installing new facilities on land adjacent to the existing Basra refinery, including a vacuum distillation unit and a diesel desulphurisation unit.
In April 2021, France’s Axens won a contract in Iraq to provide four process technologies to SRC for the Basra refinery upgrade project.
The technologies that SRC selected are:
- Diesel hydrotreatment unit (Prime-D)
- Vacuum gasoil (VGO) hydrotreating unit
- VGO fluid catalytic cracker unit
- Oligomerisation unit (polynaphtha)
In addition, Axens is providing catalysts and adsorbents, proprietary equipment, training and technical services.
MEED’s latest report on Iraq includes:
> COMMENT: Iraq’s reform window narrows
> GOVERNMENT: Al-Zaidi takes Iraq’s premiership under US shadow
> BANKING: Financial challenge tests Iraq’s resolve
> ECONOMY: Iraq enters era of resilience, reform and rising risks
> OIL & GAS: Iraqi oil and gas sector in crisis
> POWER & WATER: Focus shifts to delivery of Iraq utilities expansion
> CONSTRUCTION: Momentum builds in Iraq’s post-war construction sectorTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20503212/main.png -
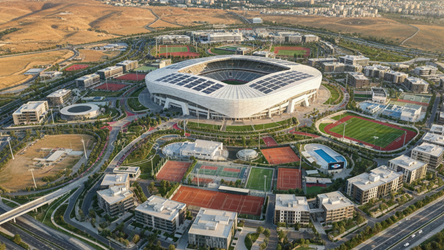
Contractors prepare Jordan stadium prequalification
12 October 2026
Contractors are preparing to submit prequalification statements on 14 October for a contract to build Jordan’s Al-Hussein Bin Abdullah II International Stadium, located east of the capital, Amman.
The project is part of the first phase of the Amra City development masterplan and is being implemented by Jordan Cities & Facilities Development Company, a Jordan Investment Fund-owned company.
Main works are expected to begin early next year, with the stadium slated for completion in 2029.
The project will cover about 1 million square metres, and the stadium will seat 50,000 spectators.
The stadium is being built within the Amra City development, which is located about 40 kilometres (km) from downtown Amman and 35km from Zarqa and Queen Alia International airport.
MEED reported that preliminary excavation and site preparation began in June.
The project forms part of Jordan’s Economic Modernisation Vision (EMV) 2023-25.
The EMV – Amman’s flagship reform programme – aims to increase real income per capita by an average of 3% annually, create 1 million jobs and more than double the country’s GDP over the next decade.
The strategy envisages a leading role for the private sector, which is expected to account for 73% of the estimated $58.8bn investment required.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20501232/main.png -
Abu Dhabi plans Mussafah road upgrades
12 October 2026
Abu Dhabi’s Department of Municipalities and Transport (DMT) has announced plans to upgrade roads in Mussafah, improving links between the industrial area, Mohamed Bin Zayed City and Zayed City.
The scheme covers about 13 kilometres of roads on the E30 and 8th Street. It aims to reduce congestion, improve road safety and cut journey times.
The works include a new three-lane highway in each direction along 8th Street, with parallel three-lane service roads on both sides providing access to local businesses and facilities.
The upgraded corridor is expected to accommodate up to 4,000 vehicles an hour.
Other works include upgrades to four E30 interchanges, improved links to 8th Street and the E20, and modifications to nine junctions.
The DMT also plans to build two bridges connecting Mussafah and Mohamed Bin Zayed City, along with a pedestrian bridge.
Abu Dhabi is planning major investments to upgrade its road network across the emirate.
Last week, it disclosed plans for a major new transport corridor in the capital, comprising a 37km coastal route linking Al-Hudayriyat Island with the E11 at Al-Nouf.
It is planned to have three lanes in each direction and will include a tunnel, about 7km of marine bridges and about 4km of causeways.
The scheme will provide a direct connection between Al-Dhafra, Al-Hudayriyat Island and Abu Dhabi Island via Halat Al-Bahrani, Al-Futaisi and Al-Aryam islands.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20501218/main.jpg