GCC banks eye a brighter future
28 July 2023

Against a backdrop of booming profits, robust liquidity and healthy loan books, GCC banks remain in generally strong fettle in 2023.
Even if performance levels this year are unlikely to match the surging metrics witnessed last year, when the post-pandemic revival drove exceptional growth stats, most regional lenders have little to fear and much to gain from regional and global conditions.
The global interest rate climate remains a source of valuable support for Gulf banks. Even if this year does not see the fat net interest margins (NIMs) that led to much of the profit generated in 2022, the first-quarter 2023 results for listed Gulf banks still show healthy earnings.
Banks in the largest markets, such as Saudi Arabia, the UAE and Kuwait, have been riding the yield curve and, while the cost of funds has increased, asset yields have widened further. Analysts say the growth in loan portfolios and asset volumes has continued this year.
“We are seeing profitability metrics improving, and that’s due to the higher rates following the dollar,” says Redmond Ramsdale, head of Middle East Bank Ratings at Fitch Ratings.
“And we’ve seen loan impairment charges coming down as banks have been building up their provisions and dealing with the pandemic. Certainly on profitability, we’re back to pre-pandemic levels, if not slightly above them.”
Broad-based growth
Bank performances reflect a confluence of factors. In the UAE, according to analysis from CI Ratings, profit growth is largely due to higher margins and net interest income, but also because provisioning expenses have come down significantly as banks see lower levels of new non-performing loan (NPL) classification and good recoveries. This is also related to the improving real estate environment.
Kamco Invest research shows net profit for listed banks in the GCC in the first quarter of this year benefitted from a steep quarterly increase in non-interest income that more than offset a sequential decline in interest income in Qatar and Kuwait.
In addition, lower provisions booked by banks in the region also supported bottom-line performance. As a result, aggregate net profits saw the biggest quarterly growth since the pandemic at 17 per cent to reach $13.4bn. The sequential increase in net profit was broad-based across the GCC.
There are some causes for concern. For one thing, GCC banks now have to grapple with an increased cost of funds. According to the Kamco figures, these have gone from 1.9 per cent in the previous quarter to a multi-quarter high of 2.5 per cent during the first three months of 2023.
But overall, GCC banks have enjoyed success in containing costs, as reflected in total operating expenses registering a decline of 3.1 per cent to $11.2bn during the first quarter of 2023, after consistent growth during the three previous quarters, according to Kamco figures.
The downturn in loan loss provisions – which increased in the 2020-22 period, driven by the pandemic impact – has proved a boon. Figures show these provisions stood at $3.1bn in the first quarter of this year, down from $3.3bn in the previous quarter.
Macro conditions
Analysts see the macroeconomic environment as playing a decisive role in supporting GCC bank performances.
“Reasonable oil prices are supporting liquidity in the system and the level of government and government-related deposits,” says Ramsdale.
“Government and government-related entity (GRE) deposits make up about 25 to 30 per cent of sector deposits, and with the increase in oil prices, we’ve seen a slight increase in these levels.”
According to CI Ratings, the largest banks in the region have distinct competitive advantages in terms of franchise, margins, cost efficiency, generally well-performing loan books and diversified earnings.
GCC banks were well placed for rising interest rates because they have quite a high base of current account and savings accounts (CASA) and a high proportion of short-term loans, says Ramsdale.
“The asset side has been repricing quickly. We have seen some migration from these low-cost CASA to term, but there is still a big proportion that’s very low cost, and that supports profitability metrics,” he says.
There has been no sign of significant deterioration in asset quality. “The end of forbearance didn’t really impact ratios too much, but interest rates have gone up a lot, and we expect some pressure on affordability. We, therefore, do expect stage three loans to start ticking up,” says Ramsdale.
Loan outlook
Lending has risen overall, although not as strongly as customer deposits, which resulted in a loan-to-deposit ratio for the GCC banking sector of 78.5 per cent in the first quarter of 2023.
Saudi Arabia stands out here, with more sector liquidity tightening reflecting stronger loan growth. Last year it was 15 per cent, significantly outpacing deposit growth of 9 per cent, says Fitch.
“The Saudi loan-to-deposit ratio of around 100 per cent is the highest it’s been in about 15 years, and it’s the opposite of what we’ve seen in other GCC markets,” says Ramsdale. “The UAE loan-to-deposit ratio hasn’t been this low for 10 years, reflecting the ample liquidity going into the UAE.”
In the kingdom, the government has been supplying additional liquidity from oil revenues that has gone into government agencies, such as the Public Investment Fund. That represented a change from the past, when that liquidity was largely channelled through the banking system.
Fitch is expecting the kingdom’s explosive recent loan growth to come down to about 12 per cent this year with a tightening of state subsidies putting pressure on housing affordability.
External funding
In Qatar, the big story is the composition of the funding base. Although there has been an improving trend in 2022 and the first quarter of 2023, CI Ratings notes that there is still a heavy dependence on wholesale funding, particularly offshore wholesale funding.
Ratings agency S&P says Qatari banks have the highest recourse to external funding among the GCC, with the system’s loan-to-deposit ratio reaching 124 per cent at the end of March 2023.
This resulted in an overall funding gap (total domestic loans minus total resident deposits) of $112bn, equivalent to almost two times the public sector deposits.
The high reliance on external funding is still a credit weakness for Qatari banks, says Amin Sakhr, director of financial institutions at Fitch Ratings.
“There’s some positivity that’s been observed since last year on the back of higher hydrocarbon revenues, which means domestic liquidity is improving, so banks are becoming less and less reliant on external funding. In the UAE and Saudi Arabia, this has traditionally been about 5-10 per cent of system deposits.”
The GCC will experience solid operating environment conditions, given that healthy oil prices will underwrite government spending
Performance prospects
In the UAE, credit demand will drive loan growth, but margins will moderate in line with interest rates. For some banks, their continuing strong NPL recovery will boost earnings performance.
The UAE’s largest banks, such as Fab and Emirates NBD, also entertain growth ambitions beyond the country's borders that will help them grow their balance sheets.
According to S&P, UAE banks are in a comfortable net external asset position and their loan-to-deposit ratios are among the strongest in the region. Banks have accumulated local deposits over the past 15 months amid muted lending growth. The ratings agency does not expect an acceleration of lending, so UAE banks’ funding profiles should continue to strengthen.
In Oman, customer deposits grew to $67bn in the first quarter of 2023, compared to $63.4bn in the same quarter of 2022.
While Omani banks are benefitting from rising interest rates, higher competition for deposits could translate into a higher cost of funds, which could impact margins. Analysts say that the benefits to banks of a rise in interest rates may be lower in Oman than in the other markets.
In Bahrain, banks will likely continue benefiting from the prevailing high-interest rate environment for the remainder of 2023.
The country’s retail banks’ loan-to-deposit ratios have been consistently below 80 per cent for the past five years, suggesting that local deposits and a significant portion of external liabilities are being recycled into government and local central bank exposures.
In contrast, Kuwait has a funding profile dominated by customer deposits, which have proved stable. Only 20 per cent of Kuwait’s deposits are from the government or GREs.
Like their Saudi counterparts, Kuwaiti banks have room to attract foreign funding. Moreover, notes S&P, the Saudi riyal’s peg to the dollar and the relative stability of the Kuwaiti dinar exchange rate – thanks to its peg to a basket of currencies – mean that even if this flow is recycled locally, foreign currency risks are likely to remain in check.
Looking ahead, the GCC will experience solid operating environment conditions, given that healthy oil prices will underwrite government spending. This should underpin lending growth and maintain the region’s top lenders’ buoyant state into 2024.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 SAR tenders design review consultancy for GCC rail link
18 September 2026
-
 Tender issued for Libyan gas project
17 September 2026
-
 Nakheel awards $218m Dubai Islands buildings deal
17 September 2026
-
 Aldar and Mubadala acquire Masdar City Square
17 September 2026
-
 Neom tenders Oxagon highway contract
17 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
SAR tenders design review consultancy for GCC rail link
18 September 2026
Register for MEED’s 14-day trial access
Saudi Arabia Railways (SAR) has issued a request for proposals (RFP) for a design management and review consultant to oversee engineering works on the GCC railway network, the latest step in advancing the long-delayed regional rail link.
The RFP was issued on 9 September, with a submission deadline of 18 October.
The tender seeks a consultant to manage, audit and verify deliverables produced by SAR's separately appointed design services consultant, rather than carry out the design itself. The tendering for the design services consultancy is currently in progress.
Construction will be tendered separately through competitive bidding once designs are approved.
The GCC railway will run for about 672 kilometres (km) inside Saudi Arabia, linking the kingdom's existing network to Kuwait, Qatar, the UAE and Bahrain, with four sections of about 141km, 200km, 151km and 21km, respectively.
The line is planned as a single-track, non-electrified corridor for mixed freight and passenger traffic, with a maximum axle load of 32.4 tonnes and passing loops for bidirectional working.
The appointed consultant will develop a design management and review plan covering governance, interdisciplinary coordination and stage-gate approvals, and will issue formal review and audit reports against SAR's requirements and international standards.
The scope also covers stakeholder engagement, interface management and oversight of land acquisition activity tied to the design consultant's land acquisition plan.
Key design stages are expected to take about 16 months: four months for concept design, six for preliminary design and six for issued-for-construction design, each with four weeks of contingency.
SAR has asked bidders to mobilise a core team from day one. These must include a project director, engineering and design manager, stakeholder manager and lead document controller, all based at SAR's offices, with minimum experience thresholds ranging from three years for junior operators up to 25 years, including 15 in rail, for the project director role.
GCC railway line
Under the overall plan, the railway will run from Kuwait, pass through Dammam in Saudi Arabia, reach Bahrain via a planned causeway, and continue from Dammam to Qatar, the UAE and, ultimately, Muscat via Sohar in Oman. The railway is reported to cover about 2,186km in total.
The route length within each member state is as follows:
- UAE – 684km
- Saudi Arabia – 672km
- Oman – 306km
- Qatar – 283km
- Kuwait – 145km
- Bahrain – 36km
The railway is designed for passenger trains travelling at 220 kilometres an hour (km/h) and freight trains operating at 80km/h–120km/h.
With high levels of project activity, governments in spending mode and renewed cooperation under the Al-Ula Declaration, the latest efforts to restart the GCC railway project may make more progress than previous attempts. If completed, the railway could prove transformational for a region that is globally connected but still divided by national borders.
 READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Nuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19783331/main.gif -
Tender issued for Libyan gas project
17 September 2026
An invitation to bid has been issued for a contract to conduct environmental assessments for the project to expand the Mellitah oil and gas complex in Libya.
The bid submission deadline is 2pm today (17 September) Libyan time.
The scope of the project includes provision of:
- An environmental baseline study (EBS)
- An environmental impact assessment (EIA)
- An environmental management plan (EMP)
The client is Mellitah Oil & Gas (MOG), which is a joint venture of Italy’s Eni and Libya’s National Oil Corporation (NOC).
MOG is based in Tripoli and operates both onshore and offshore oil and gas facilities.
The joint venture owns and operates six major oil and gas fields across the North African country.
According to the tender documents, the company that is awarded the contract will need to prepare environmental management measures in compliance with:
- Libyan environmental legislation
- Ministry of Environment requirements
- NOC environmental guidelines
- Applicable international environmental standards and best practices
The expansion of the Mellitah oil and gas complex is part of a project estimated to be worth $8bn.
The wider project is known as the Mellitah Complex Expansion & CO2 Management Integrated Development Project.
It has six main packages:
- Onshore package
- Offshore Structure A
- Offshore Structure E
- Subsea pipeline package
- Site preparation work
- Carbon capture and storage facility
Security issues and political instability have been a major problem for Libya’s oil and gas sector since the country’s civil war started in 2011.
Earlier this month, the Mellitah oil and gas complex was forced to shut down temporarily due to a protest over deteriorating public services.
The existing onshore complex includes housing, processing units, storage facilities and export facilities.
It also serves as the launch point for the Greenstream pipeline, which delivers Libyan gas directly to Italy.
The planned expansion of the complex will involve:
- Construction of a new fourth gas processing train
- Construction of a third condensate train
- Construction of a third natural gas liquids fractionation train
- Construction of a fourth sulphur recovery unit train
- Installation of a hydrogen sulphide enrichment unit
- Installation of a sulphur recovery unit
- Construction of other associated facilities
The Mellitah complex is located about 100 kilometres west of Tripoli and is a key energy facility in the west of the country.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19748920/main.png -
Nakheel awards $218m Dubai Islands buildings deal
17 September 2026
Register for MEED’s 14-day trial access
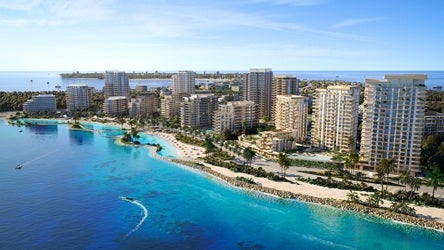
Dubai-based developer Nakheel, now part of Dubai Holding, has awarded a main construction contract worth more than AED800m ($218m) for phases one and three of Bay Grove Residences at Dubai Islands.
The contract was awarded to the local firm Metac General Contracting Company.
It covers the construction of 537 apartments, comprising one- to four-bedroom units, across seven residential buildings.
Phase one includes 296 units in four buildings, while phase three comprises 241 units across three buildings.
The works are scheduled for completion in late 2028.
Bay Grove Residences will ultimately comprise 1,154 homes across 15 buildings. Planning is under way for the remaining 617 homes in phases two and four, with further contract awards expected.
In August last year, Nakheel awarded a AED2.6bn ($708m) contract to Abu Dhabi-based Fibrex Contracting to build the Bay Villas project at Dubai Islands. The contract includes constructing 636 villas.
In April this year, another AED527m ($143m) contract was awarded to local firm Al-Nasr Contracting Company to construct the primary infrastructure and utilities works on Island B at the development.
The Dubai Islands development consists of five islands spanning 18.6 square kilometres. It features more than 59 kilometres (km) of waterfront and 20km of beaches, as well as parks, golf courses, promenades and cycling paths.
The offshore island project gained renewed momentum in 2022, when Nakheel unveiled a new masterplan and rebranded it as Dubai Islands.
The reclaimed islands were originally part of the Palm Deira project, which was partially completed before being put on hold in 2008.
READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFNuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19748850/main.jpg -
Aldar and Mubadala acquire Masdar City Square
17 September 2026
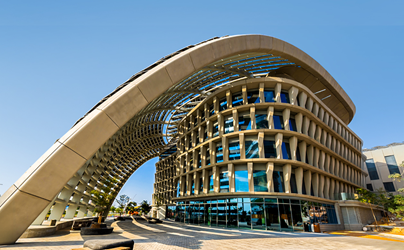
Abu Dhabi-based sovereign wealth fund Mubadala Investment Company and local developer Aldar have completed the acquisition of Masdar City Square at Masdar City, in a transaction valued at AED918m ($250m).
The deal was executed through their joint venture established in 2024.
Masdar City Square comprises more than 47,000 square metres (sq m) of net leasable area across seven office buildings.
Completed in Q1 2026, the development is 99% occupied. Tenants include Taqa, the Department of Energy, Emirates College and the Mohamed Bin Zayed University of Artificial Intelligence.
The transaction expands the joint venture’s real estate portfolio in Masdar City, which is now valued at AED4.7bn ($1.3bn).
Masdar City is one of the region’s leading hubs for clean energy, artificial intelligence, advanced research and sustainable urban development.
The joint venture acquired The Link project at Masdar City for AED654m ($178m) in April.
Comprising about 32,000 sq m of net leasable area across five buildings, The Link is fully leased to a portfolio of major tenants, including Abu Dhabi Future Energy Company (Masdar) and the Mohamed Bin Zayed University of Artificial Intelligence.
The asset includes Grade A, Leed Platinum office space, a net-zero-energy headquarters building, a multi-use hall and residential accommodation, supporting its position as a high-performing, integrated component of Masdar City.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19748241/main5814.png -
Neom tenders Oxagon highway contract
17 September 2026
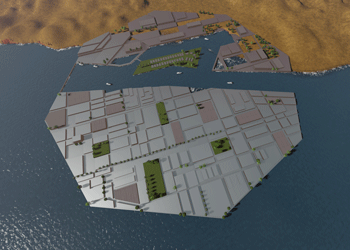
Saudi Arabia’s Neom has tendered a design-and-build contract covering permanent upgrade works on Highway 55 in the kingdom’s Oxagon region.
The first phase of the project includes constructing 14 kilometres of road, with two lanes in each direction. It also covers one bridge and three interchanges.
The project duration is 22 months.
Contractors have been given until 21 September to submit their proposals.
Highway 55 connects the Red Sea coast with the mainland in northwestern Saudi Arabia. It is currently the only road providing north-south connectivity between Duba and the Neom region.
MEED exclusively reported in August 2025 that contractors had submitted responses to the expressions of interest notice that Neom had issued earlier that month.
The project is expected to support the movement of cargo vehicles from Duba Port to other parts of the country and the wider region.
Neom tested a pilot initiative last year by handling a shipment that travelled from Cairo via the Port of Safaga, across the Red Sea to the Port of Neom, and then inland to Erbil, Iraq.
In a statement, Neom said: “The shipment travelled through an intermodal corridor spanning over 900 kilometres, marking a significant milestone in the kingdom’s transformation into a regional and global logistics hub.”
The Port of Neom is located on the Red Sea near the Arar border, a key entry point into Iraq.
READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFNuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19746896/main.gif