Gaza conflict reignites violence in Syria
4 June 2024

Since fighting began in the Gaza war in October, Syria’s civil war has been pushed even further down the regional agenda, threatening to turn a largely frozen conflict into a forgotten one.
The intensity of the fighting, which entered its 14th year in March, has atrophied into a near stalemate in recent years, with the regime of President Bashar Al Assad controlling around 70% of the country, while a medley of rebel groups, Turkish forces and Kurdish and Arab militias hold a patchwork of territories across the north and east.
However, the battle between Israel and Hamas has threatened to reignite the Syrian war in new ways.
Assad has been doing his best to avoid getting involved in any regional escalation, but that has not always been easy, with the Israeli attack on the Iranian embassy in Damascus on 1 April, in particular, raising the risk of Syria becoming a battleground.
Over the past decade, there have been numerous Israeli attacks in Syria against the Iranian Islamic Revolutionary Guards Corp’s Al Quds force as well as Tehran-backed militias, but the rate of attacks has increased since the Gaza war broke out.
Expanding violence
In March, the UN’s Independent International Commission of Inquiry on Syria issued a report which said the country has been suffering the worst wave of violence since 2020. “Since October, Syria has seen the largest escalation in fighting in four years,” said commission chairman Paulo Pinheiro at the time. “Syria … desperately needs a ceasefire.”
That analysis has been backed up by the US-based Armed Conflict Location and Event Data (ACLED) project, which recorded 201 incidents linked to Israeli attacks in Syria involving 236 deaths between October 2023 and March 2024, the highest number since it began tracking the civil war in 2017.
Assad has several reasons to want to avoid being drawn further into conflict with Israel, not least that his own forces are stretched and weakened after years of fighting.
Damascus has also not forgotten that Hamas broke ties with Assad during the Arab Spring, with the Palestinian group’s leader, Khaled Mashal, leaving Damascus in early 2012. Relations were only restored a decade later, when a Hamas delegation travelled to the Syrian capital, but they remain strained.
In contrast to the threat of escalation as a result of Gaza, the Syrian civil war itself has been largely stagnant since 2020, when Damascus abandoned its attempt to recapture the Idlib governorate in the northwest. Since then, the frontlines have stayed largely the same, but the country is far from being at peace and there is the constant threat of fresh fighting breaking out.
In October last year, a drone strike on a military graduation ceremony in the government-controlled city of Homs killed 80 people and wounded 240. In response, government forces launched an offensive against groups in the northwestern Idlib province, where Tahrir Al Sham (a militant group that emerged in 2017 out of several others) and the Turkish-backed National Liberation Front have their strongholds.
In April this year, suspected members of the Islamic State group killed 22 pro-government fighters of the Quds Brigade near the town of Sukhna in central Syria. There were similar attacks the following month.
Diplomatic overtures
Regional powers, including some in the Gulf, have urged Syria to resist being drawn into the Gaza conflict. Relations between Damascus and several Gulf capitals have been improving over the past few years, although the momentum behind that process appears to be slowing down.
Assad was in Bahrain in mid-May to attend the Arab Summit – the second such gathering he has been at since Syria was re-admitted to the organisation in 2023 following a diplomatic push by Jordan, Saudi Arabia and the UAE.
Among the other signs of diplomatic re-engagement, the UAE’s ambassador to Syria, Hassan Ahmed Al Shehi, took up his post in February, and in late May, Saudi Arabia named Faisal Al Mujfel its ambassador to Damascus – its first senior envoy there for 12 years.
The diplomatic outreach by the Gulf countries is motivated in large part by a desire to put pressure on Damascus to restrict the flow of the illegal drug Captagon into their markets, but there has been little sign to date that the Assad regime is willing to end that trade – which, by some measures, is now the largest part of the Syrian economy.
There are problems with other regional powers too, not least Turkey, which maintains control over two areas of northern Syria along their common border, from where it is trying to neutralise the threat of the People’s Defence Units (YPG), the Kurdish group at the core of the Syrian Democratic Forces now in control of some 20-25% of Syrian territory in the northeast of the country. Ankara views the YPG as a terrorist group due to its association with the Kurdistan Workers’ Party (PKK), which is banned in Turkey.
“What Damascus wants of Turkey is a full withdrawal; Turkey leaving and moving all its troops from Syria,” said Dareen Khalifa, senior adviser for dialogue promotion at the International Crisis Group, at the same Chatham House event.
“What Turkey wants of Damascus is preventing a new wave of refugees, crushing the Kurdish-led YPG forces and so on. It wants things from Damascus that Damascus can’t really deliver on. So, I think that deadlock is going to continue.”
That looks to be true of the wider civil war, too, with little sign that the Assad regime or the various rebel groups have the ability to force significant changes on the ground.
Less clear is how the situation in Gaza, and the associated Israeli attacks and provocation against Iranian groups on Syrian soil, could yet affect the ongoing conflict in Syria in less predictable ways.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Saudi projects hold steady
24 September 2026
-
 Petrokemya selects turbine supplier for cogeneration plant
24 September 2026
-
 What IFAD’s wind-down means for Gulf commodity markets
24 September 2026
-
 US DFC approves $1.8bn financing for Jordan National Water Carrier
24 September 2026
-
 Tecnimont breaks ground on Ruwais NGL train 5 project
24 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Saudi projects hold steady
24 September 2026
 Commentary
Colin Foreman
EditorSaudi Arabia’s project market is holding steady in 2026, with contract awards reaching $68bn in the year so far. The resilience is notable given the regional conflict that began in February and ongoing security threats that have disrupted shipping through key maritime chokepoints.
The kingdom’s investment strategy has also shifted. After years of aggressive project spending through sovereign wealth vehicle the Public Investment Fund, Riyadh has moved towards event-driven procurement with fixed deadlines: the 2034 Fifa World Cup, Expo 2030 Riyadh and non-negotiable housing and healthcare commitments, together with a focus on the future economy with major investments earmarked for data centres.
The approach is leaner than the sprawling gigaproject model that characterised early Vision 2030 years, and more focused on achieving tangible milestones.
Construction contract awards hit $20bn in the first half of this year, maintaining momentum against the backdrop of geopolitical uncertainty and a GDP contraction in the second quarter.
Saudi Aramco’s upstream investment programme remains substantial, with $50bn-$55bn committed for 2026, split about 65%-70% towards oil and gas. Major projects including the Dorra gas field development and the Jafurah unconventional gas expansion are progressing, underpinned by the company’s strategy of maintaining oil production at 12 million barrels a day while expanding gas capacity.
Downstream activity is also contributing. Chemicals giant Saudi Basic Industries Corporation (Sabic) approved $3.6bn in projects this year, led by the San VII ammonia and urea complex, which was awarded to South Korea’s Samsung E&A for $3.47bn. The company is returning to significant capital investment after several years of constrained spending.
Power sector activity is shifting towards transmission and battery storage infrastructure to support renewable energy targets. The kingdom’s infrastructure pipeline encompasses $175bn of projects in the transport, rail, aviation and roads segments.
Private sector participation is expanding through public-private partnership (PPP) structures, with the National Centre for Privatisation & PPP managing about 200 projects in 17 sectors, worth approximately $190bn.
The market needs more awards. Project completions have reached $91.5bn in 2026, outpacing awards by 35%. While this reflects successful execution of work awarded in prior years, it also indicates that new deals are required in the coming months to maintain activity levels into 2027.
MEED’s September 2026 report on Saudi Arabia includes:
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflictTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19794535/main.gif -
Petrokemya selects turbine supplier for cogeneration plant
24 September 2026
Saudi petrochemical company Petrokemya has selected Germany’s Siemens Energy as the turbine supplier for its planned 730MW electricity and steam cogeneration project at its complex in Jubail, according to sources.
Under a pre-defined schedule, the supply agreement will be transferred to the winning engineering, procurement and construction (EPC) contractor on 15 June 2027.
This will be followed by the execution of a long-term service agreement with Siemens Energy on 15 July 2027.
As exclusively reported by MEED, developers are preparing to submit proposals for the brownfield project, which will produce up to 1,125 tonnes an hour of steam. It will supply electricity and steam to Petrokemya under a 20-year energy conversion agreement (ECA).
Bids for the project are due by 30 November.
Petrokemya issued the request for proposals (RFP) on 30 June, and provided the technical specifications to bidders on 7 July.
Both Abu Dhabi National Energy Company (Taqa) and Saudi Arabia’s Acwa are understood to be among the developers participating in the project.
As MEED understands, a site visit took place in early August, shortly before prospective developers submitted letters of intent.
Petrokemya is expected to award the contract by 29 April 2027.
The winning bidder will establish a special-purpose vehicle in Saudi Arabia to develop, finance, construct, own and operate the project. Ownership of the project company or plant will transfer to Petrokemya at the end of the ECA term.
Petrokemya is a wholly owned subsidiary of Sabic, which is a majority-owned affiliate of Saudi Aramco. It is understood that Sabic will provide credit support for Petrokemya’s obligations under the ECA.
According to tender documents, the plant will use gas supplied by Petrokemya to generate electricity. Exhaust heat from the gas turbines will be recovered through heat recovery steam generators to produce steam, with a steam turbine generator also potentially producing electricity.
The scope includes the plant and associated infrastructure required to receive gas and feedwater and deliver electricity and steam to Petrokemya. This includes pipelines, substations, cables and other interconnection facilities.
The winning bidder will be responsible for arranging the project’s full financing on a non-recourse basis to Petrokemya and its affiliates.
The final RFP question-and-answer submission deadline is set for 5 November.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19953460/main.jpg -
What IFAD’s wind-down means for Gulf commodity markets
24 September 2026
The wind-down of ICE Futures Abu Dhabi (IFAD) – the Abu Dhabi-based futures exchange operated by US-based global exchange and clearing house operator Intercontinental Exchange (ICE) – on 31 July 2026 was the end of an era. It was also the opening move in a transformation whose legal consequences will keep the Abu Dhabi Global Market (ADGM) Courts, Dubai International Financial Centre (DIFC) Courts and London arbitral tribunals occupied for years.
One strategy
On 31 July, Abu Dhabi National Oil Company (Adnoc) announced that all four of its crude grades would move from IFAD pricing to a Platts Dubai prompt-month mechanism in November. ICE published its wind-down circular the same day.
The Iran war was the catalyst: the official selling price of Murban, Adnoc’s flagship crude grade, surged from $63 a barrel in February to $110.75 in May, and Asian refiners – managing their margins against a crude price set two months ahead of loading – demanded a more straightforward mechanism.
But the IFAD wind-down must be read alongside three other key decisions. On 1 May, the UAE withdrew from oil producers’ group Opec, freeing Adnoc from quota constraints that had capped production at 3.4 million barrels a day against a capacity of 4.85 million. On 6 July, Adnoc launched a global liquefied natural gas marketing and trading platform in the ADGM, targeting 47 million tonnes a year by 2035. Then, on 22 July, DP World signed a 50-year concession with the Fujairah Ports Authority to develop the Al-Rugaylat and Dibba terminals on the Gulf of Oman coast.
Together, these decisions constitute a coherent strategic architecture: a Hormuz-independent, Fujairah-centred, Indian Ocean-facing trade infrastructure designed to serve the markets where commodity demand will be most durable over the next 30 years.
Force majeure battleground
The legal consequences of the Iran war are immediate and novel. The most contested issue is force majeure.
IFAD was established within ADGM, which applies English common law, and was regulated by the ADGM Financial Services Regulatory Authority (FSRA). Under English law, there is no freestanding right to invoke force majeure, and the threshold is demanding. General disruption or increased costs do not suffice. The question is whether performance has become legally or physically impossible.
When Iranian strikes damaged the Fujairah Oil Industry Zone, the sole IFAD delivery point, and vessel traffic through Hormuz fell from over 100 ships a day to fewer than 14, the impossibility argument strengthened materially. But a critical distinction separates parties whose non-delivery was attributable to the physical closure of Hormuz from those whose non-delivery reflected elevated war risk premiums and unavailable insurance: the latter falls short of legal impossibility under English law.
The governing law of each contract is therefore significant. Under UAE civil law, statutory provisions address both impossibility and the court’s discretion to reduce obligations. A party whose contract is governed by English law faces a harder test, even on identical facts.
This asymmetry is generating an uptick in advisory work as trading houses assess their positions across portfolios of contracts with different governing law provisions.
The sanctions picture adds further complexity: the successive reimposition of US sanctions following ceasefire collapses has affected the legality of positions that were fully compliant when established, raising questions for which English law provides no settled answer.
The legal consequences of the Iran war are immediate and novel
Legal infrastructure
The FSRA’s regulatory framework has demonstrated resilience during the crisis. Its Recognised Investment Exchange licensing regime, under which IFAD operated, and its Environmental Instrument classification, making ADGM the first jurisdiction in the world to regulate voluntary carbon credits as financial instruments, remain available to new market entrants.
ADGM Courts, applying English common law, has developed a strong body of legal precedent over 11 years. And London-based ICE Clear Europe’s relationship with IFAD provides a model for how future exchange infrastructure in ADGM might access London clearing capability while remaining regulated in Abu Dhabi.
With the 31st UN Climate Change Conference Cop31 opening in Antalya on 9 November 2026 and Cop32 scheduled for Addis Ababa in 2027, the Article 6 Paris Agreement carbon market framework is developing rapidly. The FSRA’s Environmental Instrument classification positions ADGM as a natural regulatory home for the Gulf-Africa carbon market infrastructure that neither London nor Singapore is positioned to provide. The DP World concession, with its East African port network providing the physical verification layer that carbon credit integrity requires, reinforces that positioning.
Legal practitioners who develop expertise in this intersection of English common law, FSRA regulation, DIFC financial services law and international commodity trading before the IFAD delivery disputes are resolved and before the replacement infrastructure is announced, will be well placed in a jurisdiction growing at 57% annually by assets under management. The story of what follows IFAD has barely begun.
 https://image.digitalinsightresearch.in/uploads/NewsArticle/19954346/main.gif
-
US DFC approves $1.8bn financing for Jordan National Water Carrier
24 September 2026
The US International Development Finance Corporation (DFC) has approved a loan of up to $1bn and political-risk insurance of up to $800m for Jordan’s National Water Carrier Project.
The $1bn loan will be provided to National Carrier Project Company (NCPC) to finance the design, development, construction, operation and maintenance of the project’s seawater desalination plant, water conveyance system and dedicated solar generation plant.
The $800m of political-risk insurance will be provided to Paris-based investment and utility firms Meridiam and Suez, which are developing the project.
The National Water Carrier, also known as the Aqaba-Amman Water Desalination and Conveyance Project, is being developed under a public-private partnership between Jordan’s Ministry of Water & Irrigation and NCPC, a special-purpose vehicle owned by Meridiam (90%) and Suez (10%).
The project involves the design, development, construction, operation and maintenance of a seawater desalination plant, a water transmission system and dedicated renewable power generation facilities under a build-operate-transfer model.
Jordan signed the project’s final technical and legal agreement with Meridiam in April, following months of negotiations.
The project’s capital cost was put at about $4.3bn, with total costs including financing estimated at $5.8bn.
Financial close has not yet been completed. The project’s technical director said in July that the final agreements required for financial close were still being prepared, with construction expected to start in the fourth quarter of 2026. Water pumping is scheduled to begin in the fourth quarter of 2030.
Jordan’s cabinet approved a $97m financing agreement with the French Development Agency in July as the government continued to complete the project’s financing arrangements.
The cabinet also approved a package of facilities and exemptions for the National Water Carrier Project on 17 September to help finalise start-up procedures for the project in the Aqaba Special Economic Zone.
Jordan’s water needs
The Aqaba-Amman water desalination and conveyance project will desalinate 300 million cubic metres of seawater annually. It will also include a 450-kilometre pipeline and pumping systems reaching elevations of up to 1,100 metres.
The project is intended to help address Jordan’s severe water scarcity. As one of the world’s most water-stressed countries, Jordan consumes nearly 1 billion cubic metres of water a year.
The domestic sector consumes approximately 50% of this, with only 61 cubic metres of water available per person a year, far below the global absolute water scarcity level of 500 cubic metres of water per capita.
According to the government, the scheme will increase overall water supply by 40%, with per capita availability expected to rise to 110 cubic metres annually.
Annual output from the Water Carrier Project will be nearly equivalent to the total storage capacity of all dams in the kingdom and almost three times the output of the Disi Water Project.
The project is expected to supply about 40% of Jordan’s drinking water needs, with operations scheduled to begin in 2030. It will also include a 280MW solar photovoltaic plant in Al-Quweira covering roughly 30% of the project’s energy needs.
Financing
The government previously said the project had secured about $663m in grants from international partners, including the US, the European Union, Germany, the Netherlands, the UK, France, Italy, Japan and the Green Climate Fund.
The Jordanian government is contributing $722m.
Meridiam is arranging about $2.9bn in private sector financing from international financial institutions. The financing package includes support from institutions including the World Bank Group, European Investment Bank, European Bank for Reconstruction & Development, Islamic Development Bank, Proparco, Japan International Cooperation Agency and the Opec Fund for International Development.
A consortium of Jordanian banks led by Housing Bank is providing up to $1.1bn in local financing, with the Social Security Investment Fund also taking an equity stake alongside Meridiam.
Local manufacturing
The project is also beginning to generate associated industrial investment.
On 30 August, Jordan’s cabinet approved the establishment of a steel pipe manufacturing and coating plant in Aqaba with investment of up to JD120m ($169m). The plant is expected to allocate 50% of its production to the National Water Carrier and create about 420 jobs. Its output will also be available for future water, gas transmission and pumping projects.
The Aqaba Special Economic Zone Authority and the Ministry of Water & Irrigation also launched a dedicated single-window platform in August to streamline licensing and permitting for the National Water Carrier project.
Once operational, the project is expected to remain under the PPP structure for 26 years before ownership transfers to the Jordanian government.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19943001/main.jpg -
Tecnimont breaks ground on Ruwais NGL train 5 project
24 September 2026
Register for MEED’s 14-day trial access
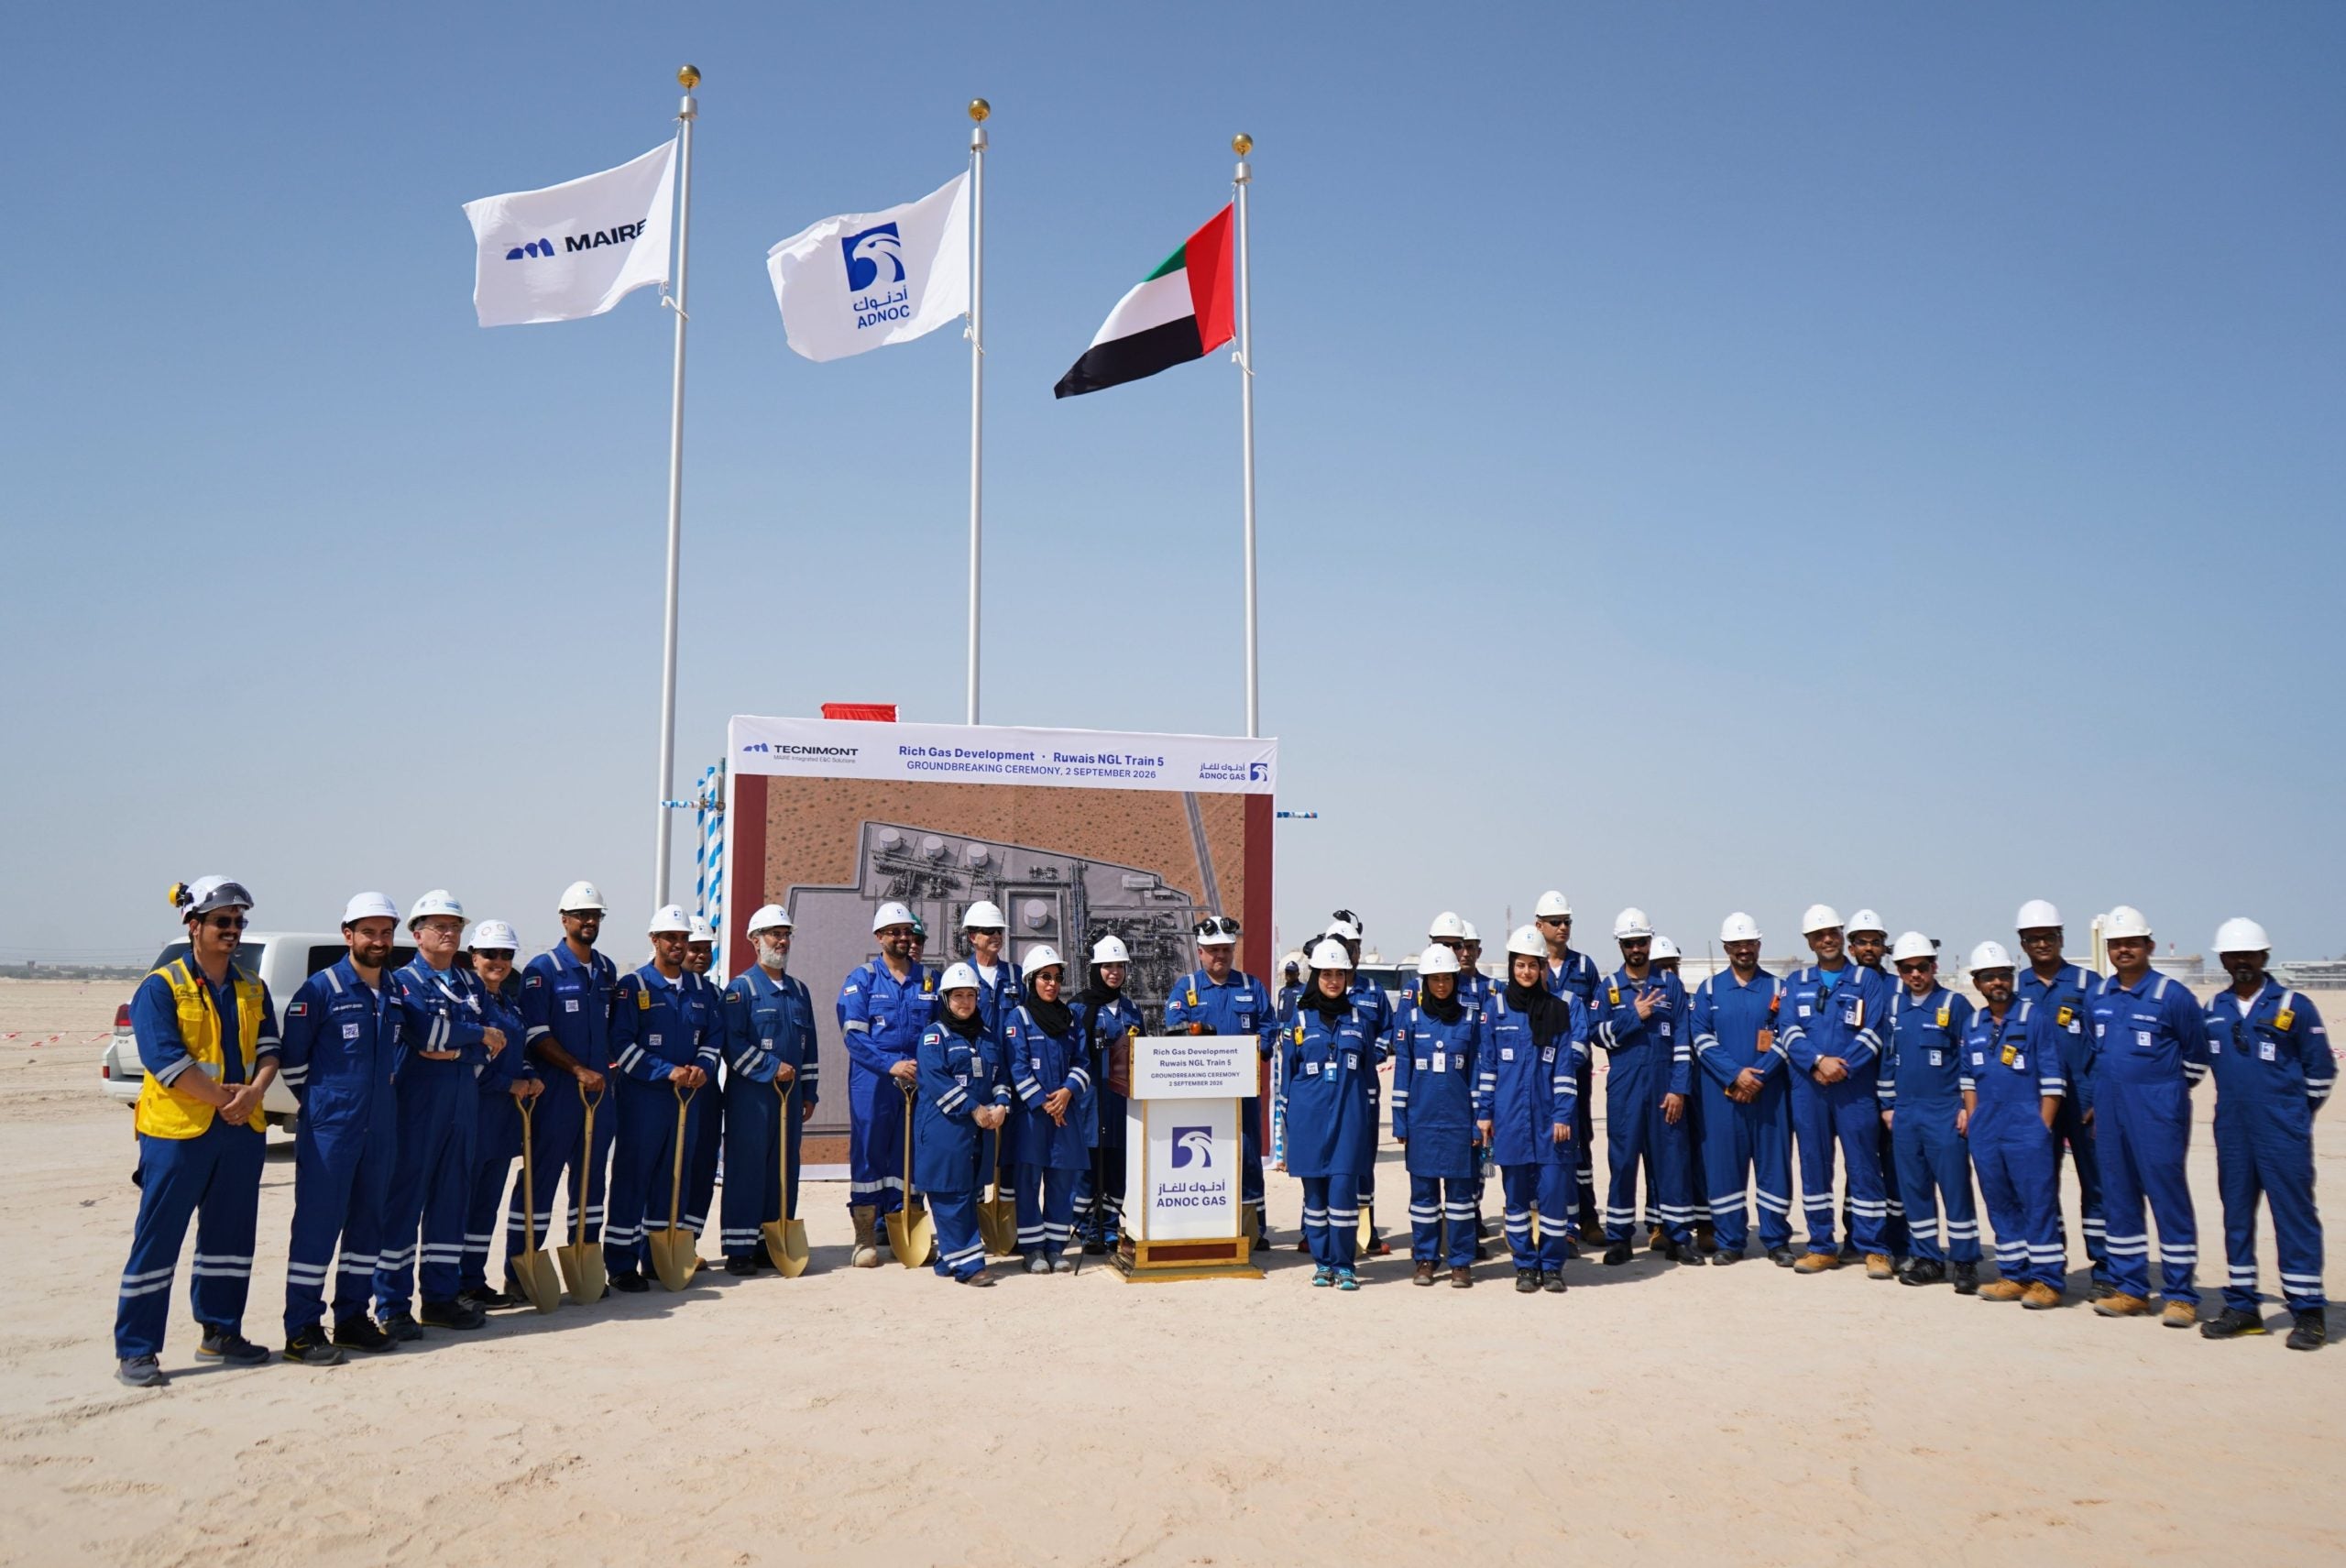
Italian contractor Tecnimont has broken ground on the third phase of Adnoc Gas’ Rich Gas Development (RGD) programme, which involves building a fifth natural gas liquids (NGL) fractionation train at the Ruwais gas processing facility in Abu Dhabi.
Adnoc Gas, the gas processing subsidiary of Abu Dhabi National Oil Company (Adnoc Group), awarded Tecnimont a contract valued at $4.3bn in August to carry out engineering, procurement and construction (EPC) works on the Ruwais NGL-5 project.
Tecnimont’s parent company, Maire, previously said its scope of work under RGD phase 3 includes EPC activities for the fifth NGL fractionation unit – which will separate various hydrocarbon components – together with treatment and sweetening systems designed to remove impurities and ensure product quality.
The scope also includes a regeneration gas treatment unit, a propane refrigeration system, ancillary systems and storage facilities. Once completed in 2030, the plant will have an output capacity of 23,000 tonnes a day (t/d), or about 8 million tonnes a year, Milan-headquartered Maire said.
The detailed scope of work on the Ruwais NGL Train 5 project covers the EPC of the following units:
- An NGL fractionation plant with a capacity of 22,000 t/d, including NGL fractionation facilities, downstream treatment units, sulphur recovery units, product storage and loading facilities, and associated utilities, flares and interconnection pipelines with existing facilities
- Two propane liquefied petroleum gas storage tanks and one paraffinic naphtha storage tank
- Buildings, including a central control building, outstations, substations and plant amenities
- Electrical power connections. Power is to be sourced from the nearby Transco substation via a direct underground cable to the plot location
Adnoc Gas requires the project’s feed to be updated based on the design of Ruwais NGL Train 4, which has an output capacity of 27,000 t/d and was commissioned in 2014.
Alongside taking the final investment decision (FID) on RGD phase 3 in August, Adnoc Gas also announced it had reached FID on the second phase of the programme, with the two projects requiring a total investment of $8.2bn.
The second phase of the RGD programme involves constructing a new gas processing train at the Habshan complex in Abu Dhabi. Adnoc Gas awarded the EPC contract for the project, valued at $3.9bn, to China-based Wison Engineering.
Wison Engineering said the EPC contract for RGD phase 2 is the largest in its history. The total contract value is $4.04bn, the Hong Kong-listed company said, adding that the scope includes gas pipelines; separation and condensate stabilisation units; acid gas removal units; deep NGL recovery units; and a 220kV switch station.
Phase 2 will add a new natural gas processing train at the Habshan facility, “expanding Adnoc Gas’ natural gas processing capacity, enhancing operational flexibility, and supporting the UAE’s expanding downstream and petrochemical sectors”, Adnoc Gas said.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19942556/main3743.jpg