First Asfar destination to open by year-end
13 May 2024
Register for MEED's guest programme
Saudi Tourism Investment Company (Asfar) plans to open its first destination by the end of the year, according to its chief executive, Fahad Bin Mushtayt.
Speaking at the MEED Saudi Giga Projects event in Riyadh, Mushtayt said: “Asfar aims to build tier-two destinations in eight cities, and we are already in five cities in less than two years."
Owned by Saudi Arabia's Public Investment Fund (PIF), Asfar focuses on tier-two tourism destinations in the kingdom by building a value chain spanning the hospitality, retail and food and beverage sectors.
MEED understands the company has initiated projects in Al Baha, Yanbu, Al Ahsa and Taif.
Asfar is developing a co-investment model with the private sector to address destination gaps.
By partnering with developers and strategically investing through joint ventures, including acquisitions of companies, Asfar aims to establish a strong foothold in the tourism market.
“We are working closely with the private sector and local municipalities to provide unforgettable experiences for travellers while driving economic growth in these regions,” said Mushtayt.
“Asfar will partner with the private sector and make strategic investments through joint ventures and acquisitions.”
PIF has formed several companies that aim to invest in and develop tourism destinations across Saudi Arabia, including Aseer Investment Company and Saudi Downtown Company.
PIF previously signed a memorandum of understanding with the Oman Investment Authority for investment in Oman worth $5bn.
Follow exclusive coverage from MEED's Saudi Giga Projects summit today and tomorrow on meed.com

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Gas-fired projects drive resilience in UAE power sector
14 October 2026
-
 SAR sets November deadline for GCC rail design review
14 October 2026
-
 Algeria tenders gas compressor upgrade project
14 October 2026
-
 State-backed spending cushions UAE construction slowdown
13 October 2026
-
 Consortium signs EPC contract for Rabigh 2 IPP expansion
13 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Gas-fired projects drive resilience in UAE power sector
14 October 2026

The $3bn Taweelah C combined-cycle gas turbine (CCGT) project has been the UAE power sector’s standout contract award this year, accounting for the majority of the $4.17bn in awards as of early September.
The total is well below the record $12.02bn awarded in 2025, when Abu Dhabi’s $6bn round-the-clock solar photovoltaic (PV) and battery energy storage system (bess) project lifted the market to record levels. However, 2026 remains broadly consistent with recent years, compared with $5.93bn in 2024 and $3.05bn in 2023.
According to MEED Projects, generation accounted for $3.06bn across three awards, while transmission contracts totalled $1.11bn.
Gas-fired focus
Emirates Water & Electricity Company (Ewec) signed the power-purchase agreement (PPA) for Taweelah C in June with a consortium comprising Abu Dhabi National Energy Company (Taqa), Saudi Arabia’s Al-Jomaih Energy & Water Company and Singapore’s Sembcorp Industries.
The scale of the 2.5GW independent power producer (IPP) provides a useful lens through which to view the wider market. Although the UAE continues to expand solar generation and battery storage, it is still investing heavily in flexible thermal capacity to support rising electricity demand and a grid with significant renewable generation.
Major gas-fired opportunities are also moving into the Northern Emirates, with state utility Etihad Water & Electricity (EtihadWE) preparing to receive offers from five contractor groups for the 2.6GW Al-Zawra CCGT project in Ajman.
The project follows the retirement of EtihadWE’s older 200MW Al-Zawra gas plant in 2023. With Ewec acting as offtaker, the scheme also points to a wider role for EtihadWE in developing large-scale generation.
It is understood that the Ajman project will be the first of at least three planned power plant projects procured by the utility under a new long-term roadmap for future projects across both power and water.
Abu Dhabi’s 3.3GW Al-Nouf IPP is another major gas-fired plant moving towards execution. Japan’s Sumitomo Corporation is expected to formally sign the PPA by the end of the year, while the joint venture of Spain’s Tecnicas Reunidas and Egypt’s Orascom Construction is also set to be confirmed as the engineering, procurement and construction (EPC) contractor.
To put this into context, the deal would make 2026 the second most valuable year for power sector investment on record, eclipsing both 2017 and 2018, when contract awards in the UAE reached $7.39bn and $7.27bn, respectively.
Solar and storage
The UAE’s renewable procurement is increasingly combining solar generation with storage to provide electricity beyond daylight hours.
Dubai Electricity & Water Authority (Dewa) is preparing to award the seventh phase of the Mohammed Bin Rashid Al-Maktoum Solar Park, with Abu Dhabi Future Energy Company (Masdar) submitting the lowest tariff for the project in July.
China’s BYD will act as a bess supplier for the project, which combines 2,000MW of PV capacity with a 1,400MW bess designed to discharge for six hours, equivalent to 8,400MWh of stored energy.
The storage component will allow Dewa to use more solar power after sunset, reducing the gap between daytime generation and the evening demand peak.
The 1,800MW sixth phase is also nearing completion, with Larsen & Toubro delivering the estimated $1.5bn project for Shuaa Energy 4, the project company formed by Dewa and Masdar.
Dewa has increased the planned capacity of the solar park to 7,260MW by 2030, from its earlier target of 5,000MW.
Furthermore, Ewec is advancing its 1.5GW Al-Zarraf solar PV plant, with EDF and Korea Western Power Company selected as the consortium to develop the project.
Grid expansion
Multibillion-dollar IPP schemes have driven annual award values in recent years, while transmission work continues to provide a steadier flow of opportunities for contractors and equipment suppliers.
Transmission awards fell to $1.11bn across 22 packages in 2026, from $2.98bn in 2025, reflecting the absence of a comparable large-scale package rather than a halt in network investment.
Ewec and Taqa are expanding 400kV and 132kV networks across Abu Dhabi and the Northern Emirates, while Dewa continues to reinforce its cable and substation systems in Dubai.
In September, EtihadWE received bids for a contract to carry out a techno-economic feasibility study for a proposed 2GW subsea electricity interconnector with India.
The proposed 1,400-kilometre link would be the UAE’s first direct subsea cross-border electricity interconnector, illustrating a potential longer-term ambition to connect the UAE to wider regional and international power markets.
Earlier this year, the GCC Interconnection Authority awarded Omexom, part of France’s Vinci Group, a contract to build a 400kV overhead transmission line between the UAE and Saudi Arabia.
In October, the UAE and Saudi Arabia signed a memorandum of understanding to advance cross-border electricity interconnection, paving the way for feasibility studies on power exchange, commercial electricity trading and the expansion of the wider GCC interconnection grid.
Waste-to-energy
Waste-to-energy continues to become an increasingly important part of the UAE’s infrastructure pipeline as the country seeks to reduce landfill dependence and diversify its power mix through alternative generation sources.
Dubai Municipality recently invited developers to submit expressions of interest for its planned Jebel Ali waste-to-energy public-private partnership, a greenfield facility designed to treat up to 6,000 tonnes of municipal solid waste a day.
According to a source, the municipality plans to prequalify developers later this year, then issue a request for proposals in the first quarter of 2027.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20582379/main.gif -
SAR sets November deadline for GCC rail design review
14 October 2026
Saudi Arabia Railways (SAR) has set a deadline of 1 November for a contract to appoint a design management and review consultant to oversee engineering works on the GCC railway network, the latest step in advancing the long-delayed regional rail link.
The request for proposals (RFP) was issued on 9 September, with an initial submission deadline of 18 October.
The tender seeks a consultant to manage, audit and verify deliverables produced by SAR’s separately appointed design services consultant, rather than carry out the design itself. The tendering for the design services consultancy is currently in progress.
Construction will be tendered separately through competitive bidding once designs are approved.
The GCC railway will run for about 672 kilometres (km) inside Saudi Arabia, linking the kingdom’s existing network to Kuwait, Qatar, the UAE and Bahrain, with four sections of about 141km, 200km, 151km and 21km, respectively.
The line is planned as a single-track, non-electrified corridor for mixed freight and passenger traffic, with a maximum axle load of 32.4 tonnes and passing loops for bidirectional working.
The appointed consultant will develop a design management and review plan covering governance, interdisciplinary coordination and stage-gate approvals, and will issue formal review and audit reports against SAR’s requirements and international standards.
The scope also covers stakeholder engagement, interface management and oversight of land acquisition activity tied to the design consultant’s land acquisition plan.
Key design stages are expected to take about 16 months: four months for concept design, six for preliminary design and six for issued-for-construction design, each with four weeks of contingency.
SAR has asked bidders to mobilise a core team from day one. These must include a project director, engineering and design manager, stakeholder manager and lead document controller, all based at SAR’s offices, with minimum experience thresholds ranging from three years for junior operators up to 25 years, including 15 in rail, for the project director role.
Cross-border infrastructure related to the GCC rail is also gaining momentum, with the UAE and Saudi Arabia signing a preliminary agreement in early October to study rail connectivity.
The rail component covers technical and economic feasibility studies for a dedicated freight link between the two national networks to improve bilateral logistics and supply-chain integration.
The deal also covers potential electricity interconnection, including the exchange and sale of power. The countries will conduct technical, economic and environmental studies and coordinate with other GCC member states on broader grid-development plans.
GCC railway line
Under the overall plan, the railway will run from Kuwait, pass through Dammam in Saudi Arabia, reach Bahrain via a planned causeway, and continue from Dammam to Qatar, the UAE and, ultimately, Muscat via Sohar in Oman. The railway is reported to cover about 2,186km in total.
The route length within each member state is as follows:
- UAE – 684km
- Saudi Arabia – 672km
- Oman – 306km
- Qatar – 283km
- Kuwait – 145km
- Bahrain – 36km
The railway is designed for passenger trains travelling at 220 kilometres an hour (km/h) and freight trains operating at 80km/h-120km/h.
With high levels of project activity, governments in spending mode and renewed cooperation under the Al-Ula Declaration, the latest efforts to restart the GCC railway project may make more progress than previous attempts. If completed, the railway could prove transformational for a region that is globally connected but still divided by national borders.
MEED’s October 2026 report on Saudi Arabia includes:
> COMMENT: Saudi projects hold steady
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflict
> DATABANK: Saudi data indicates project spending shiftTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20576332/main.jpg -
Algeria tenders gas compressor upgrade project
14 October 2026
Algeria’s national oil and gas company Sonatrach has issued a tender for a project to upgrade 11 gas compressor stations in the Hassi Hassi Messaoud area.
The project scope includes study, design, procurement, construction, installation and commissioning of units at the compressor stations.
The deadline for submitting technical bids is 22 November.
The compression stations to be upgraded include 10 located at the Southern Industrial Complex.
These are known as: SC3, SC4, SC5, SC6, SC7, SC8, SC9, SC10, SC11 and SC12.
The eleventh compressor station, UC3, is located at the Naili Abdelhalim Industrial Complex.
The project appears to revive plans dating back to at least 2019, when Sonatrach identified the refurbishment of the SC3–SC12 facilities as part of its investment programme.
International companies wishing to bid must have an average turnover of at least $1bn over the last three years.
They are also required to have successfully completed at least two engineering, procurement and construction contracts relating to industrial hydrocarbon installation projects during the last 15 years.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20551634/main.jpg -
State-backed spending cushions UAE construction slowdown
13 October 2026
The UAE projects market is undergoing a structural realignment. Following a surge in private real estate investment after the Covid-19 pandemic, activity in the commercial and residential segments has softened amid regional geopolitical uncertainty.
Rather than allowing the market to contract, state and government-related entities (GREs) – particularly in Dubai – have stepped in to offset the shortfall, deploying balance-sheet capital countercyclically into strategic infrastructure, cultural and tourism projects.
Dubai recalibrates
Dubai’s construction sector has remained resilient at a headline level. On-site work continues, and major international contractors are securing new work.
A clear indicator of this stability came in September, when China State Construction Engineering Corporation secured an AED5bn ($1.3bn) contract from Dubai Holding for the developer’s new headquarters and the Jumeirah Residences Emirates Towers scheme.
Beneath this headline stability, however, procurement drivers have shifted dramatically. Private real estate activity, which supported the market’s post-pandemic resurgence, cooled following the onset of regional conflict at the end of February. Off-plan residential sales declined from a monthly peak of $9bn in February to $4bn in August.
Monthly contract awards for residential projects mirrored this contraction, dropping from $3bn to $306m over the same period as private developers deferred new project launches and conserved capital.
Government and government-related clients have absorbed much of the resulting shortfall. Dubai awarded $52.6bn of contracts in 2025, of which state-backed clients accounted for $26bn, or about 49%.
In 2026 to date, government and GRE procurement has reached $22.4bn of the $34.6bn in contracts awarded, representing almost two-thirds of total market activity.
The shift towards sovereign-backed spending appears intended to support construction activity and limit pressure on the supply chain during a period of private sector retrenchment.
This state intervention is underpinned by an unawarded projects pipeline of $530bn in Dubai, according to MEED Projects data.
The city’s future construction pipeline remains heavily weighted towards housing and integrated urban developments. Unawarded construction projects in the emirate total about $144.5bn, with residential and mixed-use developments accounting for almost 89% of the total value.
Planned residential schemes account for $66.5bn, or 46%, of the pipeline, followed by large-scale mixed-use developments at $62bn, or 42.7%. The remainder comprises hospitality projects ($5bn), commercial offices ($4.8bn), telecommunications ($2bn) and retail ($2bn), alongside smaller allocations for education and civic facilities.
Abu Dhabi accelerates
A similar dynamic is evident in Abu Dhabi, where sovereign-backed entities continue to shape construction procurement. Unlike Dubai, which has historically relied more heavily on private developers, Abu Dhabi’s market is largely led by state-affiliated master developers.
Entities such as Aldar Properties and Modon Holding remain the primary engines of the emirate’s residential and mixed-use pipeline, progressing vast masterplans across Saadiyat Island, Yas Island and Hudayriyat Island.
At the same time, Abu Dhabi is directing public capital expenditure towards entertainment, culture and hospitality as it pursues the objectives of its Tourism Strategy 2030.
Rather than moderating capital deployment amid regional geopolitical strains, state-backed entities are accelerating destination developments designed to expand visitor capacity and build long-term economic resilience.
Leisure developer Miral has already confirmed plans to invest more than AED12bn ($3.2bn) across Yas Island over the next five years. The investment will fund new attractions and expand hotel capacity, separate from the planned Disney development.
Work is already under way on a 63,000-square-metre phase-two expansion of Warner Bros World Yas Island, featuring a Harry Potter-themed zone.
Major civic entertainment venues are also moving to construction. In May, Alec Engineering & Contracting received the letter of award for the $1.7bn Sphere Abu Dhabi project on Yas Island. The venue is being developed by the Department of Culture and Tourism–Abu Dhabi (DCT Abu Dhabi) in partnership with US-based Sphere Entertainment, and is scheduled to be completed in the third quarter of fiscal year 2029.
On neighbouring Saadiyat Island, DCT Abu Dhabi has broken ground on Dar Al-Funoon, a performing arts venue designed by the late Frank Gehry. The project is planned to accommodate more than 6,000 people across a 2,000-seat multipurpose hall, an open-air amphitheatre, a studio theatre and a jazz venue. Main contract bids are currently under evaluation ahead of an imminent award and a 2030 opening.
Abu Dhabi’s unawarded projects pipeline is led by mixed-use and residential developments, which together account for about $51.3bn, or 54% of the roughly $95bn total shown.
Telecommunications and data infrastructure forms the single largest individual segment at $33.4bn (35%). Subsequent phases of the estimated $40bn Stargate project represent the bulk of the emirate’s planned data-centre capacity. The planned artificial intelligence infrastructure initiative is designed to strengthen Abu Dhabi’s position as a regional data and connectivity hub, with construction on phase one already under way.
Hospitality accounts for a further $7.6bn (8%) of the pipeline. The remaining balance of roughly $2.6bn is distributed across retail, culture, leisure, healthcare, public facilities, commercial offices, earthworks and education.
Along with Dubai’s $79.6bn in near-term tenders, the combined $116bn in active procurement confirms that sovereign liquidity will continue to insulate the UAE construction market from broader private sector volatility.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20536766/main.gif -
Consortium signs EPC contract for Rabigh 2 IPP expansion
13 October 2026
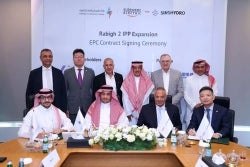
A consortium comprising PowerChina, Egypt’s Elsewedy Electric and Beijing-headquartered Sinohydro has signed an engineering, procurement and construction (EPC) contract for Saudi Arabia’s Rabigh 2 combined-cycle gas-turbine (CCGT) independent power project (IPP) expansion.
The signing ceremony took place in Riyadh on 12 October and the contract involves the plant’s design, procurement, installation, construction, commissioning, grid connection and performance testing.
MEED previously reported that construction works had commenced, with Elsewedy Electric and Sinohydro carrying out works on the project.
The signing follows the project’s financial close earlier this month, after it secured SR9.69bn ($2.58bn) in long-term financing.
The financing has a tenor of approximately 34 years and was provided by a consortium of local, regional and international lenders.
The project is being developed by Al-Morjan Two Electricity Company, in which Acwa and Saudi Energy, formerly Saudi Electricity Company, each hold a 40% stake.
In April, MEED reported that Acwa and Saudi Energy had signed a 31-year power purchase agreement (PPA) with Saudi Power Procurement Company (SPPC) for the project.
The agreement is valued at SR11.5bn ($3.07bn) and covers the development of a CCGT plant in the Mecca region under a build, own and operate arrangement. The project also includes the development and expansion of a 380kV electrical substation. The plant is designed to be ready for the future installation of carbon-capture technology.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20535598/main3026.jpg