Familiar realities threaten Egypt’s energy ambitions
7 February 2024
 This package on Egypt's power sector also includes:
> Egypt to complete Gabal El Zeit wind farms sale
> Egypt president and Putin mark El Dabaa construction
> EBRD invests in 1.1GW Egypt wind farm
> Scatec in talks for Nagaa Hammadi solar project
> Team signs land deal for 1.1GW Egypt wind project
> Acwa Power moves forward with Egypt green hydrogen project

As of early 2024, Egypt appears to have come full circle in terms of providing electricity services to its citizens.
The country faced severe power shortages in 2013-14, which gave way to the fast-tracked construction of 14.4GW of gas-powered generation capacity in 2018. This, along with the increase in renewable energy capacity, resulted in a surplus of up to 25%, yet since late last year consumers have once again been experiencing power outages lasting up to two hours.
This time, however, the power outages – which began in the summer of 2023 and are expected to last until March this year – are not due to a capacity deficit.
The government-initiated load-shedding programme initially aimed to rein in rising electricity consumption and reduce pressure on the country's gas network.
According to the country’s Electricity & Renewable Energy Ministry, national electricity consumption reached 43,650MW in mid-July last year, up significantly from previous highs of about 31,000MW.
While the record-high consumption level is still way below the official generation installed capacity of close to 60,000MW, consumption levels of between 34,000MW and 36,000MW will require around 129-146 million cubic metres of gas and diesel a day.
Barring load-shedding, any increase in consumption beyond 36,000MW will require a commensurate increase in gas and diesel, which is understood to be beyond the government’s capacity to procure.
Crucially, the other side of the electricity rationing initiative has to do with the need to save gas for exports, to boost the government’s dollar reserves in the face of the ongoing currency crisis.
Frustration over the power cuts and their impact on job productivity and the overall economy has been growing over the past few months.
There are no magic pills, however, and any solution needs to start with broader economic and energy sector reforms, to improve the prospects of attracting investments, notes Jessica Obeid, a partner at Dubai-headquartered New Energy Consult.
“Reducing reliance on gas for domestic power generation and increasing renewable energy plus storage are critical, not only to reduce the shortage gap but also to improve energy security, since one gas field, Zohr, feeds almost half of the domestic needs,” she explains. “In the immediate term, doubling down on energy-efficient measures and demand-side management is needed.”
It is an awkward and unprecedented situation for the North African state, which has espoused a clear intention – and started executing relevant projects – to establish itself as a regional energy hub, exporting natural gas and electricity to neighbouring countries, as well as to Europe.
“The government has signaled its prioritisation of exports, although no economy can grow nor become a hub while dealing with energy shortages,” Obeid says.
“The Egyptian government has showcased that the focus is on economic revenues from gas exports, even if that is at the expense of the living conditions of the citizens. However, Egypt cannot realise its hefty regional ambitions without efficient measures and reforms to mend the high domestic reliance on gas, and the lower gas production prospects.”
Another expert on Egypt’s energy policies notes that the country is in a tough spot and “needs ideas to move ahead from this”.
In addition to its energy hub plans, Egypt could look into other opportunities such as setting up repair hubs for ships, as well as education centres to cater to the needs of those hubs, the expert suggests, while noting – as Obeid does – the need for wide-ranging reforms, including improving the rule of law and developing alternative sources of wealth and income.
Important milestones
Six months of electricity rationing makes it easy to overlook the cumulative – though, in hindsight, insufficient – steps that Egypt has taken to avoid falling once again into the power outage trap.
Egypt has one of the highest renewable energy penetration rates in relation to overall installed capacity in the Middle East and North Africa region. While this is commendable, it has only served to highlight the weakness of the country's electricity grid when it comes to handling intermittent renewable energy sources such as solar and wind.
Nonetheless, the country is continuing to build additional renewable energy capacity, including hydropower, and with the help of Russian financing, it has also embarked on the construction of its first nuclear power plant. These projects could replace the ageing oil and gas fleet, lowering the sector's emissions while also supporting the country's energy diversification and security agendas.
Egypt aims to be a global green hydrogen and ammonia hub, and signed preliminary agreements for over a dozen such schemes when it hosted the UN global climate summit, Cop27, in November 2022.
If these projects reach the execution stage, not only do they have the potential to advance the country’s ambition to be a global green energy hub, they will also help to attract much-needed dollars to fund its economic diversification plans.
However, the ability to implement reforms and develop bankable projects lies at the heart of the deployment of any technology in Egypt, points out Obeid.
“Egypt’s existing experience in hydrogen, and being part of that trade market, along with abundant renewable energy resources, a vast land [area] and the country’s geographic location are enablers of a hydrogen market," she says.
“Yet, Egypt’s economic and financial challenges have led to higher interest rates, lower lending capacity and higher costs for system components, and these need to be addressed first.”
Never say die
Despite a bleak short- to medium-term outlook, some projects are moving ahead in Egypt.
The European Bank for Reconstruction & Development will invest $75m in equity in the Netherlands-based subsidiary of Egypt's Hassan Allam Utilities, which along with Saudi utility developer Acwa Power is co-developing a wind independent power producer scheme in the country's Gulf of Suez and Gabal El Zeit area.
Acwa Power also reached financial close for a 200MW solar photovoltaic facility in Kom Ombo in August last year, two years after the project was put on hold due to rising solar panel and freight costs.
Even the 505MW Amunet wind farm project, located in Ras Ghareb in the Gulf of Suez on the Red Sea coast, is moving ahead. A consortium of the UAE-based Amea Power and Japan’s Sumitomo Corporation last year enlisted Shanghai-headquartered Envision Energy to supply wind turbines for the project.
According to the New & Renewable Energy Authority (NREA), solar and wind projects with a total capacity of close to 3.5GW were under development in Egypt as of the end of 2023, while schemes totalling 39GW are in the planning stage.
Hydrogen and ammonia
In November, Abu Dhabi-based Fertiglobe delivered what might have been the world's first internationally certified renewable ammonia from its pilot electrolyser site in Egypt to India. The ammonia will be used to produce near-zero-emissions synthetic soda ash – a key ingredient in laundry powder – for Unilever.
Several planned integrated green hydrogen projects in Egypt are in the pre-front-end engineering and design (pre-feed) stage.
One of the green ammonia projects is being developed by Germany's DAI Infrastruktur. To be located in East Port Said, the Ra green ammonia project will have a total production capacity of 2 million tonnes a year (mtpa) of green ammonia, of which 1.65 mtpa is expected to be based purely on renewable energy resources when complete.
DAI has signed a preliminary agreement with Siemens Energy, which plans to supply electrolysers, auxiliary plant systems and critical equipment making up the hydrogen island of the project.
DAI and UK-headquartered Freepan Holding are also understood to have signed an offtake agreement for the ammonia produced at the Ra plant. The 10-year offtake agreement covers 800,000 tonnes a year of ammonia, with the first green ammonia delivery to Freepan expected in 2028.
A similarly sized project is being developed by Amea Power in the coastal town of Ain Sokhna in the Suez governorate. The company is in the process of appointing pre-feed consultants and contractors that will undertake geotechnical, topography and environmental studies for the project.
Detailed studies are also under way for interconnections transporting clean energy from Egypt to Europe, as the latter seeks alternatives to Russian energy exports.
Stakeholders in these projects will continue to monitor the Egyptian government's management of its energy policies at home and abroad over the next few months as they decide the next steps in their investment plans.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Lebanon sets October deadline for power generation projects
23 September 2026
-
 Jedco maps next phase of Jeddah airport expansion
22 September 2026
-
 Contractor wins $105m Medina university hospital deal
22 September 2026
-
 Oman tenders Thumrait Industrial City infrastructure
22 September 2026
-
 Kuwait halves drilling contractor pool
22 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Lebanon sets October deadline for power generation projects
23 September 2026
Lebanon’s Electricity Regulatory Authority (ERA) has extended the deadline for private sector companies to submit expressions of interest (EoIs) for several upcoming power generation projects.
The new deadline is 15 October. The original deadline was 30 September.
The regulator said the extension follows “requests received from interested applicants for additional time to finalise and submit the required documentation”.
The EoI covers up to five grid-connected solar photovoltaic projects with a combined installed capacity of 350 megawatts-peak. The projects are also expected to include battery energy storage systems with a combined capacity of 1,000 megawatt-hours.
The regulator is also seeking proposals for distributed dual-fired thermal power plants with net capacities ranging from 20MW to 100MW. The plants are expected to run on natural gas as the primary fuel and heavy fuel oil as a backup.
The ERA invited companies to submit EoIs at the beginning of August.
On 11 August, the ERA issued its first set of clarifications following queries regarding the EoI. The clarifications confirmed that “proposed dual-fired plants should be gas-ready”, with natural-gas infrastructure planned but no implementation timeline yet available.
The ERA also said key power purchase agreement (PPA) terms, including duration, tariff structure and indexation mechanisms, will be determined “during a future procurement process”.
Electricity reforms
The EoI comes as the government advances wider reforms to Lebanon’s electricity sector. On 4 September, the Higher Council for Privatisation and Partnership discussed steps to transform the state utility Electricite du Liban (EDL) into a company, including creating a new entity, transferring its assets, and taking measures to protect employees’ rights during the transition.
The government said the restructuring aims to improve the financial sustainability of the electricity sector, recover costs and improve electricity supply.
On 18 September, the council discussed a draft decree to establish the new EDL company, evaluate its assets and separate its activities. However, it deferred a decision for further study.
The ERA was established earlier this year, more than two decades after it was envisaged under Law No. 462/2002 but not implemented due to political delays. The Energy & Water Ministry and EDL previously oversaw the electricity sector.
Lebanon’s electricity sector continues to face insufficient generation capacity, fuel supply constraints, ageing generation assets and limited grid flexibility. These challenges have led to prolonged electricity shortages and increased reliance on private diesel generation and distributed solar systems, prompting the government to seek additional private investment in new generation capacity.
According to the EoI document, the projects are expected to be structured as independent power producer (IPP) schemes. The competent public authority will determine any future contractual arrangements, including PPAs, under the applicable legal framework.
The ERA said the EoI is open to private investors, IPP operators, engineering, procurement and construction contractors, equipment suppliers and consortiums. It aims to assess market interest, identify potential generation projects, and evaluate the technical and financial capabilities of prospective developers.
Respondents must provide information on their technical and financial capabilities, proposed project locations, grid connection plans and relevant project experience.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19906210/main.jpg -
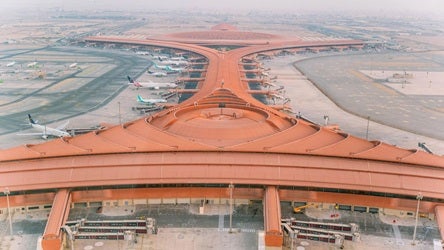
Jedco maps next phase of Jeddah airport expansion
22 September 2026
Jeddah Airports Company (Jedco) has outlined plans for the next phase of expansion at King Abdulaziz International airport (KAIA) in Jeddah.
The programme comprises six upcoming contractor packages spanning airside works, terminal upgrades and utilities as Jedco advances its long-term expansion plans.
The opportunities include airfield rehabilitation; a five-year construction framework covering multiple workstreams and facility types; a Terminal 3A (T3A) package; Terminal 1 (T1) optimisation; a fuel farm; and Concourse C works.
The packages cover terminal buildings and ancillary facilities, runways, taxiways and aprons, hangars, fuel systems, airside facilities, supporting infrastructure and utility networks.
Tendering and award activity will be staggered over the next two years. Airfield rehabilitation is targeted for Q3 2026. The construction framework is scheduled for Q4 2026 and will run for five years.
The T3A package is planned for Q1 2027 and will be delivered under an early contractor involvement contract. Local contractors are encouraged to bid as part of a joint venture with an experienced international partner.
T1 optimisation is planned for Q4 2027, the fuel farm for Q2 2027, and Concourse C – currently the latest of the six milestones – for Q2 2028.
The new packages add detail to Jedco’s wider expansion plans disclosed in 2023, when it was reported that the company would invest SR115bn ($31bn) to increase KAIA’s capacity to 114 million passengers a year, with an overall completion target of 2031.
Jedco has recently awarded several significant contracts linked to the airport’s upgrade programme.
In November 2024, a joint venture of local Algihaz Contracting and Turkey’s TAV was awarded a contract to rehabilitate the South Terminal to serve Umrah and Hajj pilgrims, with Singapore’s Surbana Jurong acting as consultant.
Earlier that year, Jedco also awarded France’s Alstom a contract to increase the capacity of the Innovia automated people mover at Terminal 1, including new cars and upgrades to signalling, communications and controls.
Surbana Jurong is expected to play a leading role in future KAIA expansion plans and is currently providing technical advisory and project management consultancy for more than 100 capital projects for Jedco, valued at over SR6bn ($1.6bn).
These upgrades are expected to boost KAIA’s annual capacity in line with Saudi Arabia’s Vision 2030 and National Aviation Strategy, enhancing the experience for domestic travellers and millions of Hajj and Umrah pilgrims.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19877992/main.jpg -
Contractor wins $105m Medina university hospital deal
22 September 2026
Riyadh-based construction firm Al-Mansouria General Contracting Company has been awarded a SR396m ($105.6m) contract to complete the remaining construction works on the Taiba University Hospital project in Medina.
The contract scope includes structural completion, remaining civil works, mechanical, electrical and plumbing installations, specialised clinical fit-outs and medical gas infrastructure to bring the long-stalled facility into operation.
Located on King Khalid Road along Medina’s Third Ring Road, the teaching hospital will have a capacity of 563 beds.
The contract duration is three years, with delivery targeted for late 2029.
The latest award follows a prolonged procurement cycle that began more than a decade ago as part of a public budget drive to expand Saudi Arabia’s higher education infrastructure.
The project’s first phase was initially signed in December 2011 with local firm Al-Muhaidib Contracting under a SR500m ($133.3m) contract.
Groundbreaking for the eight-storey complex took place in July 2013. The project covers a gross floor area of more than 200,000 square metres.
Progress stalled shortly thereafter due to reported structural delays and the reallocation of public capital budgets across the kingdom’s social infrastructure pipeline.
 READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Nuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19870032/main.jpg -
Oman tenders Thumrait Industrial City infrastructure
22 September 2026
Oman’s Public Establishment for Industrial Estates (Madayn) has tendered an estimated RO15m ($39m) contract to develop infrastructure for Thumrait Industrial City.
The tender was issued on 14 September, with bids due by 12 November.
The scope covers site-wide utilities and services, including an internal road network, stormwater channels and culverts. It also includes installing sewerage and water networks, along with landscaping works.
In addition, Madayn intends to build plug-and-play industrial units and a facilities building.
The first phase of the development will cover about 120,000 square metres (sq m).
Thumrait Industrial City is located in Oman’s Dhofar Governorate and spans an area of more than four million sq m.
The project location is close to concession blocks, quarry sites and the Najd agricultural areas. It is positioned to attract industrial investments in sectors such as mining and minerals processing (including gypsum and cement), food production, and a range of light and general manufacturing activities.
In March, Madayn said it is preparing to invest more than RO245m ($637m) to upgrade and expand infrastructure across its industrial cities between 2026 and 2030, as part of efforts to attract new investment and advance economic diversification.
According to media reports, Madayn chief executive Dawood Bin Salim Al-Hadabi said the programme is part of an expanded, phased plan aligned with Oman Vision 2040 and the authority’s long-term Madayn 2040 strategy.
The objective is to deepen Oman’s industrial base and spread growth across the sultanate’s governorates.
Madayn said the pipeline comprises about 90 strategic projects to improve industrial-city infrastructure, extend serviced land and increase the overall ease of doing business for investors.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19866218/main.jpg -
Kuwait halves drilling contractor pool
22 September 2026
State-owned upstream operator Kuwait Oil Company (KOC) has reduced the number of approved contractors for onshore drilling and shallow-well maintenance from 51 to 24.
Firms that are no longer qualified include major contractors such as Italy’s Saipem, Oklahoma-based Helmerich & Payne and Houston-based Patterson-UTI Energy.
The latest list still includes a wide range of Kuwaiti, regional and international companies, according to the latest update on its electronic system, published on 21 September 2026.
The full list of contractors that are now qualified to participate in tenders is:
- Burgan Company for Well Drilling, Trading & Maintenance (Kuwait)
- Kuwait Drilling Company (Kuwait)
- Sun Drilling Kuwait (Kuwait)
- TDL Kuwait for Oil Rigs & Natural Gas Extraction Activities, Services and Facilities (Kuwait)
- United Precision Drilling (Kuwait)
- Abraj Energy Services (Oman)
- Adnoc Drilling Company (UAE)
- Arabian Drilling Company (Saudi Arabia)
- Anton Oilfield Services (China)
- China Oilfield Services (China)
- Egyptian Drilling Company (Egypt)
- CNPC Bohai Drilling Engineering Company (China)
- Great Wall Drilling Company (China)
- John Energy (India)
- Kerui Oilfield Service (China)
- KCA Deutag Drilling (Germany)
- Mohammed Al-Barwani Petroleum Services (Oman)
- Nabors Drilling International (US)
- National Drilling & Services Company (Oman)
- Sea & Land Drilling Contractors (Oman)
- Sinopec International Petroleum Service Corporation (China)
- Karamay Jianye Energy (China)
- Modern Drilling Company (Egypt)
- Grey Wolf Drilling International (US)
An earlier list, which was published on 11 February, included 51 qualified companies.
The reduction in qualified drilling contractors follows KOC’s notice on 27 April this year, informing existing qualified contractors that they would need to reapply.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19863744/main3435.jpg