Dubai eyes tourism sector recovery
29 June 2026

> This package also includes: GCC presses ahead with tourism projects
Dubai’s tourism sector was in a position of strength when the regional conflict began on 28 February.
Full-year figures published by the Dubai Department of Economy & Tourism (DET) in February confirmed that the emirate welcomed 19.59 million international overnight visitors in 2025, a 5% increase on the 18.72 million recorded in 2024, and a third consecutive year of record-setting arrivals. The city received more than 2 million visitors in a single calendar month when December 2025 closed with 2.04 million arrivals, 6% ahead of the same period in 2024.
Average hotel occupancy in Dubai’s 827 properties reached 80.7% in 2025, up from 78.2% in 2024. Revenue per available room rose 11% year-on-year to AED467 ($127), while the average daily rate increased 8% to AED579 ($158).
By the end of December, the city’s hotel room inventory stood at 154,264, ahead of cities including Bangkok, New York, Paris and Singapore.
Western Europe remained the largest source market, contributing 4.1 million arrivals and accounting for 21% of total visitors, while the GCC and Middle East and North Africa regions together represented 26% , with 2.99 million and 2.17 million arrivals, respectively. South Asia, the CIS and Eastern Europe each contributed 2.89 million visitors.
The regional context was similarly buoyant. According to the World Travel & Tourism Council’s (WTTC) 2026 Economic Impact Research, Middle East travel and tourism GDP expanded 5.3% in 2025, outpacing the global sector average of 4.1%.
The UAE’s travel and tourism sector reached $68.5bn in GDP contribution in 2025, with international visitor spending of $56.9bn. Pre-conflict, WTTC had forecast $207bn in international visitor spending across the Middle East for 2026.
Sudden shock
The outbreak of conflict on 28 February produced a swift and serious impact across the regional tourism ecosystem. Within days, the WTTC estimated losses of at least $600m a day in international visitor spending across the Middle East, as air travel was disrupted, traveller confidence weakened and regional connectivity fractured.
The major Gulf aviation hubs including Dubai, Abu Dhabi, Doha and Bahrain, which together process about 526,000 passengers daily, experienced closures and operational disruption. On the day the conflict began, the EU Aviation Safety Agency issued a bulletin on the dangers of flying in the airspace of 11 countries, including the UAE, Saudi Arabia, Bahrain, Qatar, Oman and Kuwait.
The data for the first quarter of 2026 reflects the scale of the disruption. According to UN Tourism’s latest World Tourism Barometer, international arrivals across the Middle East fell 14% in the first quarter of 2026, with hotel occupancy in the region declining sharply to 48% in March from 75% in January, against a global average of 64%.
International air traffic among Middle Eastern carriers fell 61% in March, measured in revenue passenger-kilometres, according to the International Air Transport Association (Iata), dragging overall global international traffic into modest contraction for the month.
The conflict also introduced structural complications that extended beyond the immediate decline in arrivals. Several major source markets, including the UK, issued advisories against all but essential travel to the UAE. The UK’s Foreign, Commonwealth & Development Office (FCDO) guidance cited the risk of renewed strikes on civilian infrastructure, including ports, hotels, roads and airports, and advised residents to consider departing if their presence was not essential.
The divergence from Dubai’s own official position, which characterised the emirate as stable and operationally normal, created a coverage gap that complicated conventional travel insurance provision and suppressed bookings from key markets.
On 18 June, the UK updated its position, removing the advisory against all but essential travel to the UAE and noting that commercial flight routes to depart the region remain available. The change marks a significant shift in the formal risk landscape for one of Dubai’s most important source markets, removing a barrier that had complicated both insurance provision and leisure booking decisions across the UK market for nearly four months.
Emirates and Etihad Airways both moved to address the insurance gap directly ahead of the FCDO change. On 17 June, Emirates launched a comprehensive travel cover product developed in partnership with insurance provider Travel Guard, offering medical cover for conflict-related incidents, trip cancellation cover, compensation for baggage delay or loss, and unlimited medical expense and emergency evacuation cover worldwide. The product is available across 27 markets.
Emirates also committed to rebooking disrupted customers at no additional cost where flights have been cancelled due to conflict-related disruption, including itineraries connecting on other carriers.

Arrivals data
Data from UK-based analytics firm GlobalData illustrates both the scale of the expected contraction and the strength of the projected recovery. UAE international arrivals, which reached approximately 30 million in 2025, are forecast to fall to about 26.4 million in 2026 – a decline of roughly 12% – before rebounding sharply to 32.1 million in 2027.
GlobalData’s projections then show continued growth to about 33.5 million in 2028, 35.1 million in 2029 and 36.6 million by 2030.
On that trajectory, arrivals would exceed pre-conflict levels within a single year of recovery and surpass 2025 figures by more than 7% in 2027 alone.
The GlobalData numbers place the 2026 contraction in a longer historical context. UAE arrivals grew almost uninterrupted from 8.4 million in 2009 to 25.6 million in 2019, before collapsing to 8.4 million in 2020 at the height of the Covid-19 pandemic. The subsequent recovery was among the fastest recorded for any major destination: arrivals reached 22 million in 2022, crossed 26.3 million in 2023 and climbed to 28.7 million in 2024 before the 2025 peak.
That precedent – a two-thirds collapse followed by full recovery within three years – underpins the confidence embedded in GlobalData’s post-conflict forecast, which projects a return to growth momentum by 2027 and a trajectory that would deliver 36.6 million arrivals by 2030.
The near-term contraction nevertheless remains substantial. A decline from approximately 30 million to 26.4 million in a single year represents the sharpest drop in UAE arrivals outside the pandemic, and it comes at a point when the sector had been tracking well ahead of pre-pandemic levels.
Past experience
Historical precedent from comparable disruptions points to a consistent pattern: recovery shape is determined less by the severity of the initial decline than by the duration of the disrupting event and the speed at which the perception of the source market resets.
Single-event incidents with clear endpoints and no sustained security overhang have historically produced the fastest recoveries, with arrivals returning to trend within 12 months. Sustained conflicts or events that trigger prolonged travel advisory regimes produce more extended recovery arcs, with source market confidence rather than operational conditions defining the timeline.
The Egypt Metrojet bombing in 2015 remains the most instructive cautionary example for the Gulf: Russian airspace restrictions imposed after the incident kept a major source market out of the Egyptian market for more than five years, with arrivals recovery lagging the resolution of the underlying security concern by a significant margin.
The UAE’s own Covid recovery offers a relevant local reference point. The GlobalData numbers show arrivals collapsed from 25.6 million in 2019 to 8.4 million in 2020, before recovering to 21.9 million in 2022 and surpassing pre-pandemic levels by 2023. The post-conflict recovery forecast of a bounce back to above 2025 levels by 2027 is less aggressive than the post-Covid rebound, reflecting both the more moderate scale of the 2026 contraction and the more complex advisory and perception dynamics involved in a conflict resolution scenario.
The DET’s response is structured around three priorities: operational continuity, sector support and market confidence. The government announced a AED2.5bn ($612.7m) support package targeting the tourism, hospitality and entertainment sectors, structured to protect business continuity, preserve employment and maintain visitor experience standards. Dubai is doing all it can, but much depends on how quickly perceptions shift.
Pilgrimages drive Saudi tourism
More than 1.7 million pilgrims performed Hajj in 2026, according to official data published by Saudi Arabia’s General Authority for Statistics, underscoring the continued centrality of religious tourism to the kingdom’s visitor economy.
The total of 1,707,301 pilgrims comprised 1,546,655 from outside the kingdom and 160,646 internal pilgrims, which includes Saudi citizens and residents.
The vast majority of international pilgrims arrived by air, with 1,485,729 using this mode of transport. A further 54,429 arrived overland and 6,497 by sea. Pilgrims represented 165 nationalities, reflecting the global reach of the event.
The scale of the logistical operation accompanying Hajj is equally significant. Supporting the pilgrimage required 441,049 workers and 26,701 volunteers. Saudi Arabia’s pre-clearance programme, which processes travel documentation at the point of departure to streamline entry to the kingdom for participants from select countries, was used by 388,694 pilgrims.
Hajj is a structural pillar of Saudi religious tourism, which alongside Umrah, draws tens of millions of visitors to Mecca and Medina each year. The sector sits at the core of Vision 2030’s tourism diversification strategy, which targets 150 million visits a year by the end of the decade.
Continued investment in transport infrastructure, including the expanded King Abdulaziz International airport and Haramain high-speed railway capacity, will help Riyadh achieve this target.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Riyadh shifts bid deadline for King Salman Stadium works
11 November 2026
-
 Hormuz crisis sparks regional pipeline project boom
11 November 2026
-
 Saudi Arabia approves revival of Iraq oil pipeline
11 November 2026
-
 Dubai approves metro extension to Al-Maktoum airport
10 November 2026
-
 Bahrain tenders 100MW Bilaj Al-Jazayer solar project
10 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
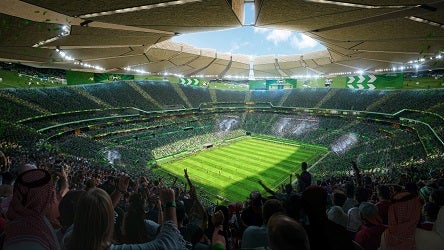
Riyadh shifts bid deadline for King Salman Stadium works
11 November 2026
Saudi Arabia’s Sports Ministry has set a deadline of 1 December for a contract covering early works at the King Salman International Stadium in Riyadh.
The tender scope encompasses enabling works, site preparation and initial construction activities. The tender was issued on 11 October, carrying an initial submission deadline of 19 November. Contractors previously submitted prequalification statements for the main design-and-build contract in February.
Designed by US-based architectural firm Populous, the stadium will cover approximately 660,000 square metres (sq m), seat 92,000 spectators and stand adjacent to King Abdulaziz Park. Facilities will feature a 150-seat royal suite, 120 hospitality suites, 300 VIP seats and 2,200 dignitary seats.
The broader masterplan encompasses more than 360,000 sq m of ancillary facilities, featuring two training fields, fan zones, a closed sports hall, an Olympic-sized swimming pool, an athletics track, and outdoor courts for volleyball, basketball and padel.
Scheduled for completion by 2029, the venue will serve as the home base for the Saudi national football team and host the opening match and final of the 2034 Fifa World Cup.
Saudi stadium plans
In August 2024, MEED reported that Saudi Arabia plans to build 11 new stadiums and refurbish four existing venues for the 2034 tournament. Eight venues will be located in Riyadh, four in Jeddah, and one each in Al-Khobar, Abha and Neom.
An additional 10 cities will host team base camps: Al-Baha, Jazan, Taif, Medina, AlUla, Umluj, Tabuk, Hail, Al-Ahsa and Buraidah. Across the kingdom, organisers plan to deploy 134 training sites, comprising 61 existing facilities and 73 new builds.
Saudi Arabia was officially selected to host the 2034 Fifa World Cup during an online convention of member associations at the Fifa Congress on 11 December 2024.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21325461/main.jpg -
Hormuz crisis sparks regional pipeline project boom
11 November 2026
 Analysis
Wil Crisp
Oil & gas reporterRegister for MEED’s 14-day trial access
The ongoing disruption to shipping through the Strait of Hormuz and the Bab Al-Mandab Strait has sparked a regional pipeline project boom, as countries seek to diversify export routes for oil and gas.
Since the US and Israel attacked Iran on 28 February, several major pipeline projects have been announced, while others are being revived or accelerated.
Countries that are participating in this regional pipeline boom include Iraq, Syria and Egypt.
While the regional conflict has changed the dynamics within the oil and gas sectors of each of these countries in different ways, all of them see major pipeline projects as a key part of their strategic response to the conflict.
Iraqi expansion
Iraq is one of the region’s oil exporters that has been hit the hardest by the disruption to shipping through the Strait of Hormuz.
Prior to the start of the regional conflict, the country was routing 94% of its total exports through the strait, with about 3.4 million barrels a day (b/d) being exported through its southern ports at the start of the year.
At the same time, about 200,000 b/d was being exported via the Iraq-Turkiye Pipeline (ITP) in the north of the country.
In the wake of the disruption to shipping through the Strait of Hormuz, Iraq has increased the volumes being exported via the ITP and has boosted its crude exports by truck through Syria.
Earlier this month, domestic news outlets reported that Iraq’s State Oil Marketing Organisation is exporting 500,000 b/d through the ITP.
The daily exports consist of 125,000 barrels of Kirkuk crude, 175,000-200,000 barrels of Kurdistan Region crude and about 200,000 barrels of Basra crude, according to the reports.
The Basra oil reaches collection stations at Sarallu and Khurmala by truck and from there is pumped north to Ceyhan in Turkiye.
The volume of crude exported from Iraq by truck to the Syrian port of Baniyas has risen significantly in recent months.
In October, Youssef Qablawi, the chief executive of the state-owned Syrian Petroleum Company, said that about 1,000 trucks were transporting fuel oil to Syria each day, with each truck carrying about 220 barrels.
This represents exports of 220,000 b/d, which is a significant volume for Iraq, but transporting crude by truck is much more expensive than using a pipeline.
Because of this, Iraq sees pipeline projects as a long-term solution to its reliance on the Strait of Hormuz and is rapidly pushing ahead with projects that are designed to replace exports currently transported by road, as well as increasing the volumes that can be exported via both Syria and Turkiye.
Earlier this month, MEED reported that the governments of Iraq and Syria, state-owned oil companies and a consortium led by Qatar’s UCC are currently discussing the terms of a deal for four interconnected pipeline packages that are expected to have a total value of about $5bn.
Stakeholders expect a contract to be signed before the end of the year that will make the UCC-led coalition the selected developer responsible for tendering engineering, procurement and construction (EPC) contracts for the project.
The consortium includes US-based Chevron, investment company TI Capital and France’s TotalEnergies.
The four pipeline routes that are being discussed are:
- Basra to Najaf
- Najaf to Haditha
- Haditha to Fish Khapour
- Haditha to Banias Port in Syria
The proposed plan will use a fast-track framework to bring the pipelines online as quickly as possible.
Red Sea route
Iraq and Saudi Arabia are also considering reviving an old pipeline route between the Zubair oil field in Basra and the Red Sea port of Yanbu.
Operations of this 1,568-kilometre (km) pipeline were halted in August 1990 following Iraq's invasion of Kuwait and the onset of the Gulf War.
At the end of October, Saudi Arabia granted preliminary approval to revive the joint oil export pipeline project, according to a report published by Saudi Arabia’s Shafaq News, which cited anonymous sources.
If the pipeline is reinstated, it could allow Iraq to export oil via the Red Sea, reducing its reliance on the Strait of Hormuz.
The pipeline was originally built at a cost of more than $2.6bn and featured a large network of storage tanks and offshore loading terminals.
Syrian strategy
In addition to its involvement in Iraq’s strategic export pipeline project, Qatar’s UCC is developing a pipeline project in Syria that will increase the country’s ability to deal with future supply disruptions.
On 30 September, UCC announced that it has , which will extend 186km between Homs and Aleppo.
The 36-inch pipeline will have a transmission capacity of up to 11 million cubic metres a day (cm/d) of gas and will connect gas networks in Jordan to those in Turkiye via Syria.
In its announcement, UCC said that the project is scheduled for completion within 22 months and will contribute to strengthening Syria’s gas infrastructure; enhancing the capacity of its gas transmission network; and supporting regional connectivity with Jordan, Turkiye and Lebanon.
Hisham Al-Saleh, Syrian Petroleum Company’s deputy chief executive for the gas sector, has said that the project includes the installation of three compressors in Furqlus, which will allow gas to be transported in both directions between Turkiye and Jordan.
Speaking to the state-owned Syrian Arab News Agency, he said that the project will add an estimated 8 million cubic metres of storage capacity to the Syrian gas network, providing greater flexibility in managing gas production and use.
Egyptian ambitions
Egypt is also ramping up pipeline project activity in order to increase the number of oil and gas links that it has with neighbouring countries.
The North African nation has long had ambitions to try and become a major regional energy hub.
These plans have been given a boost by the ongoing disruption to shipping through the Strait of Hormuz and the Bab Al-Mandab Strait, which has reduced exports from nations like Qatar, Kuwait, Iraq, the UAE and Saudi Arabia.
Concerns about the reliability of exports from Iraq and the GCC have led to increased investment in oil and gas infrastructure in countries that are not reliant on these waterways to transport hydrocarbons.
In recent months, significant progress has been made on an integrated project that was launched in order to export offshore gas reserves in Cyprus via Egyptian energy infrastructure.
In October, Italian oil and gas company Eni signed the main EPC and drilling contracts for the project, which will develop the Cronos field.
The project includes contracts with several companies that will develop infrastructure in both Egypt and Cyprus.
The awards include a $170m contract that has been won by Egypt’s Petrojet for a new onshore gas pipeline in Egypt that will help to transport gas to Egypt’s Damietta liquefied natural gas (LNG) facility.
Separately, US-based Baker Hughes signed a contract for the design, procurement and construction of subsea production systems, including associated equipment and control systems.
In September, it was announced that US-headquartered McDermott will carry out offshore work for the project, including the transportation, installation and connection of subsea pipelines and equipment.
The Cronos development project will significantly increase the volume of gas being imported into Egypt, where it can be exported as LNG as well as helping to meet domestic demand.
On top of the major pipeline project allowing the importation of gas from Cyprus, Cairo is also looking at other regional pipeline projects, including gas links to Libya.
In a statement released earlier this month, Egyptian Foreign Minister Badr Abdelatty said that a Libyan team will visit Cairo soon to continue technical talks about the gas pipelines, as well as other energy projects, with Egypt’s petroleum and electricity ministers.
Pipeline problems
While the planned oil pipeline projects in Iraq are seen as a possible solution to the disruption to shipping through the Strait of Hormuz, they are also likely to face problems relating to the importation of necessary equipment that would normally be shipped through the waterway.
The Common Seawater Supply Project, designed to bring water from the sea to inject into oil fields, is currently behind schedule, largely because of problems importing the pipeline segments through the strait.
This issue could plague other planned pipeline projects in Iraq if the disruption to shipping continues, forcing contractors to use other, more costly, import routes.
Challenging conditions
Even when Iraq’s major export pipeline projects are completed, they may fail to resolve the country’s oil export problems to the extent many are expecting.
While the export pipelines will go some way towards diversifying away from reliance on exports through waterways where oil and gas tankers are vulnerable to militant attacks, many industry insiders say Iraq could just be replacing one vulnerable export route with another.
Oil pipelines in the Middle East and North Africa region have a long history of suffering attacks and often stretch long distances through remote regions where they are difficult to defend.
Ultimately, it is likely that finding a diplomatic solution to the regional conflict will be the only way that Iraq can reliably increase its oil exports in the long term.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21305172/main.jpg -
Saudi Arabia approves revival of Iraq oil pipeline
11 November 2026
Register for MEED’s 14-day trial access
Iraq and Saudi Arabia are considering reviving an old pipeline route between the Zubair oil field in Basra and Saudi Arabia’s Red Sea port of Yanbu.
Operations of this 1,568-kilometre (km) pipeline were halted in August 1990 following Iraq’s invasion of Kuwait and the onset of the Gulf War.
At the end of last month, Saudi Arabia granted preliminary approval to revive the joint oil export pipeline, according to a report published by Saudi Arabia’s Shafaq News that cited anonymous sources.
If the pipeline is reinstated, it could allow Iraq to export oil via the Red Sea, reducing its reliance on the Strait of Hormuz.
The pipeline was originally built at a cost of more than $2.6bn and featured a large network of storage tanks and offshore loading terminals.
Under current discussions, Iraq will be required to fund the restoration of its own section of the pipeline.
The Middle East and North Africa region is currently experiencing a boom in pipeline project activity due to disruption to shipping as a result of the war that started when the US and Israel attacked Iran on 28 February 2026.
As a result of the conflict, the shipping of gas, chemicals, oil and refined products has been disrupted in both the Strait of Hormuz and the Bab Al-Mandab Strait.
Many countries, including Saudi Arabia and Iraq, see pipelines as a key way of diversifying export routes so that they are less reliant on shipping through these two waterways.
MEED’s October 2026 report on Saudi Arabia includes:
> COMMENT: Saudi projects hold steady
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflict
> DATABANK: Saudi data indicates project spending shiftTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/21304885/main.jpg -
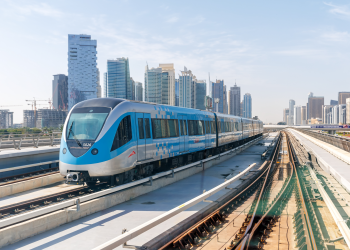
Dubai approves metro extension to Al-Maktoum airport
10 November 2026
Register for MEED’s 14-day trial access
Dubai’s Executive Council has approved a project to extend the Dubai Metro’s Route 2020 to Al-Maktoum International Airport City, with passenger services scheduled to begin operations in 2031.
Sheikh Hamdan bin Mohammed bin Rashid Al-Maktoum, Crown Prince of Dubai, announced the decision following a council meeting held during the UAE Government Annual Meetings 2026.
The rail project forms part of a package of strategic schemes worth over AED11bn ($3bn) approved by the council.
The wider approvals include a comprehensive framework to upgrade community facilities and public services by 2040, with priority given to residential communities for UAE citizens.
حمدان بن محمد يترأس اجتماع المجلس التنفيذي لإمارة دبي ضمن الاجتماعات السنوية لحكومة دولة الإمارات، ويعتمد خلاله موازنة بقيمة أكثر من 11 مليار درهم لمشاريع استراتيجية جديدة في دبي، وخطة شاملة لتطوير الخدمات والمرافق المجتمعية، ومشروع امتداد مترو دبي إلى مطار آل مكتوم الدولي، كما أعتمد سموه خلال الاجتماع نتائج دراسة مستقبل السوق العقاري في دبي.
— Dubai Media Office (@DXBMediaOffice) November 10, 2026
The project approval follows the procurement of detailed design work for the rail link. MEED exclusively reported in September that Dubai’s Roads & Transport Authority (RTA) had awarded US-based engineering consultancy Aecom the design contract for the Route 2020 extension.
The planned extension will run for about 3 kilometres from the existing Expo 2020 terminus station to connect directly with the West Terminal of Al-Maktoum International airport. The scheme will add two new stations to the network.
The existing Route 2020 corridor is a 15km spur that branches off the Dubai Metro Red Line at Jebel Ali station. It comprises 11.8km of elevated viaduct and 3.2km of underground track, serving five elevated and two underground stations.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21301168/main.png -
Bahrain tenders 100MW Bilaj Al-Jazayer solar project
10 November 2026
Register for MEED’s 14-day trial access
Bahrain’s Electricity and Water Authority (EWA) has issued a tender for the Bilaj Al-Jazayer independent power project (BAJ solar IPP), a utility-scale solar scheme with a planned capacity of at least 100MW.
The project will be procured on a public-private partnership basis using a build-own-operate (BOO) model.
The selected developer will develop, finance, design, construct, operate, maintain, decommission and restore the project site over a 25-year contract period.
EWA has set a target commercial operation date of 31 December 2028.
The scope includes photovoltaic generation facilities, utility-scale inverters, access roads and internal roads. The plant will use proven photovoltaic modules and inverters designed for Bahrain’s local operating conditions.
The tender was published on 8 November. Companies have until 20 December to submit bids, with bid opening scheduled for 21 December.
The tender requires an initial bond of BD300,000 ($796,000).
The project will be awarded through a single-stage request-for-proposals process.
Bidders will first be assessed against minimum eligibility requirements covering financial strength, project-financing capability and experience in large-scale solar developments before their technical and financial proposals are evaluated.
A single bidder must demonstrate tangible net worth of at least $50m.
In a consortium, each member must demonstrate net worth equivalent to its proposed shareholding in the $50m threshold, while the managing member must have a tangible net worth of at least $20m.
The managing member must also have secured at least $150m of limited-recourse financing across three or more infrastructure projects during the past 10 years. It must hold at least a 15% equity stake in each reference project.
Bidders or their engineering, procurement and construction contractors must demonstrate experience delivering either three grid-connected ground-mounted solar projects of at least 100MWac each globally, or two projects of at least 70MWac each in the GCC. The reference projects must be connected to the grid at 66kV or above.
The BAJ solar IPP supports Bahrain’s target of sourcing 20% of its energy from renewable sources by 2035.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21291585/main.jpg