Driving tech in the Middle East
20 December 2024

Heading into 2025, a spate of technological breakthroughs are set to fundamentally reshape industries worldwide, driving unprecedented innovation across critical sectors.
 Cutting-edge developments in artificial intelligence (AI), renewable energy, digital currencies, transportation and healthcare are converging to create transformative opportunities, according to the Tech Predictions 2025 report by GlobalData Thematic Intelligence.
AI stands at the forefront of this technological revolution, with generative models and autonomous systems pushing the boundaries of what is possible.
Simultaneously, advancements in battery technology and mineral exploration are accelerating the global transition to sustainable energy solutions.
In the Middle East, these global technological trends are not just being adopted but actively amplified
Emerging technologies such as blockchain are revolutionising finance, while the mobility sector is being reshaped by autonomous and electric transportation technologies.
Healthcare is experiencing a digital renaissance, leveraging AI, telemedicine and bio-technology to deliver more personalised and accessible medical services.
The future of work is being redefined by hybrid models and sophisticated digital collaboration tools, all underpinned by increasingly robust cybersecurity innovations that protect against evolving digital threats.
Regional priorities
In the Middle East, these global technological trends are not just being adopted but actively amplified through strategic national initiatives.
Regional governments and enterprises are making significant investments in AI-driven startups, renewable energy infrastructure and advanced technologies. From pioneering smart city projects like Neom to emerging leadership in cryptocurrency and gaming industries, the Middle East is positioning itself as a global innovation hub.
The region’s commitment to technological diversification is evident in its targeted investments across multiple sectors.
Global technology giants are establishing significant cloud and data centre infrastructure, while local initiatives in health tech, gaming and digital innovation are gaining international recognition.
These efforts collectively demonstrate the Middle East’s strategic vision to transform its economic landscape and establish a prominent role in the global digital economy.
By embracing these technological advancements, the region is not merely adapting to global trends, but actively shaping a more interconnected, sustainable and digitally sophisticated future.
ARTIFICIAL INTELLIGENCE
The global AI market is on a trajectory of major growth, with projections indicating it will surpass $1tn by the end of the decade.
Generative AI is emerging as a particularly transformative capability, promising to drive growth through unprecedented automation and a reimagining of traditional business models.
 Another emerging trend is the increasing focus on small language models (SLMs), which offer greater cost-effectiveness, enhanced security and simplified management over their larger counterparts and are especially powerful in domain-specific applications.
Big tech firms such as Microsoft, Open AI and Amazon are well-positioned in both the generative AI and SLM spaces.
Looking ahead, the next technological frontier appears to be agentic AI – intelligent, autonomous systems that are capable of sophisticated multi-step reasoning and dynamic context adaptation. This holds immense potential and could revolutionise efficiency and customer experiences across diverse sectors.
Market winners will successfully develop and implement enterprise AI solutions while laggards risk obsolescence.
The Middle East is positioning itself as a global AI innovation hub, with countries including the UAE and Saudi Arabia investing heavily in areas such as AI governance, autonomous systems and smart city technologies.
Projects like Saudi Arabia’s Neom and Dubai’s smart city initiatives are integrating AI for urban management, enhancing infrastructure and optimising public services through real-time data analysis.
DATA CENTRES
The demand for AI-ready data centres is surging as cloud providers like Microsoft Azure, Amazon Web Services and Google Cloud expand their capabilities to host advanced AI models, such as Open AI’s GPT-4. According to GlobalData, total investment in data centres reached $70.6bn in 2024 and is projected to grow by 5% to $74.3bn in 2025.
This rapid growth is bringing challenges such as power shortages and increasing pressure from governments to reduce energy consumption in alignment with climate targets.
 The International Energy Agency estimates that data centre electricity consumption will hit 1,000 terawatt-hours by 2026, doubling from 2023 levels. To meet this rising demand sustainably, tech giants are turning to low-carbon energy solutions, including solar, wind, biofuel and nuclear power.
The Middle East data centre market is experiencing rapid growth, driven by increased digital adoption and internet access. The region’s data centre construction market is projected to reach $4.39bn by 2029, growing at a compound annual growth rate of 10.99%.
The UAE has the highest concentration of data centres, while Saudi Arabia is the fastest-growing regional market, attracting global players like Google and Huawei.
Sustainability initiatives are also gaining traction, with both countries aiming for significant renewable energy integration in their power mix.
Overall, the Middle East and North Africa region is poised for major investment in the development of data infrastructure.

The region’s data centre construction market is projected to reach $4.39bn by 2029
CYBERSECURITY
The cybersecurity landscape is undergoing a transformation, with the market projected to expand to $208.5bn by 2025, representing a 10% growth from $188.8bn in 2024.
This growth will be accompanied by increasingly sophisticated threats that leverage AI to create more complex and dangerous cyber attacks.
 AI is shaping both defensive and offensive cybersecurity strategies. Cybercriminals are now utilising generative AI to craft more convincing phishing attempts and develop more advanced malware.
The scale of this threat is alarming, with AI-powered malware attacks surging by an extraordinary 275% in 2024 compared to 2023, presenting unprecedented challenges for cybersecurity vendors and organisations worldwide.
Ransomware attacks continue to escalate, with criminals estimated to have extracted $1.1bn in ransom payments during 2023.
The democratisation of cyber attack tools through AI and ransomware-as-a-service platforms is making more sophisticated attacks increasingly accessible to less technically skilled individuals.
While direct ransom payments remain unbanned, emerging regulations are expected to introduce mandatory breach reporting and enhance international collaborative efforts to combat these threats.
In line with global trends, cybersecurity is a growing concern in the Middle East, with governments and enterprises prioritising advanced cyber defence strategies, including AI-based security solutions and regional collaboration to enhance risk assessment, address cyber risks and detect fraud.
CRYPTOCURRENCIES
The digital financial landscape is undergoing a transformation as cryptocurrencies are increasingly accepted by institutional investors as a mainstream asset.
 This, alongside regulatory developments that could create a more favorable environment for digital asset adoption, are positioning the sector for significant growth in 2025.
The anticipated regulatory approach suggests increased institutional interest and broader mainstream acceptance of cryptocurrency technologies.
The US is expected to develop a more accommodating regulatory framework for cryptocurrencies, potentially reducing enforcement barriers and creating a more welcoming global environment for financial innovation. This shift could make it easier for financial institutions to invest in and manage crypto assets, signalling a potential mainstream breakthrough for digital currencies.
The Middle East is similarly emerging as a cryptocurrency hub, with Dubai leading in regulatory frameworks and blockchain innovation.
Crypto exchanges, tokenised real estate projects and interest in decentralised finance are gaining momentum throughout the region.
HEALTH TECH
The healthcare industry stands on the cusp of a technological revolution, with AI and three-dimensional (3D) printing poised to transform medical care and patient outcomes.
AI is rapidly emerging as a game-changing technology in the fields of medical diagnostics and imaging.
 Computer vision technologies are already demonstrating remarkable capabilities in assisting radiologists, enabling quicker and more precise identification of abnormalities in medical scans.
This technological frontier is experiencing explosive growth, with the global computer vision market projected to expand from $19bn in 2023 to $125.1bn by 2030, signalling the immense potential of AI in healthcare.
Also emerging as a revolutionary technology in healthcare, 3D printing enables the production of highly personalised medical devices such as prosthetics and implants.
This technology promises to dramatically reduce production costs while providing customised solutions tailored to individual patient needs.
The 3D-printing healthcare market is forecast to grow from $1.4bn in 2023 to $9bn by 2035, reflecting the technology’s enormous potential to reshape medical device manufacturing.
In the Middle East region, governments are investing in health tech startups that are adopting emerging technologies, including the use of AI analytics or predictive diagnostics and telemedicine based on patient data, as a means of enhancing healthcare access and boosting efficiency.
FUTURE OF WORK
The future of work is undergoing a profound metamorphosis, with technology emerging as the primary catalyst for transforming traditional workplace environments. This evolution promises a more dynamic, collaborative ecosystem in which human capabilities are augmented and enhanced by digital technologies.
Generative AI is poised to become a cornerstone of workplace innovation, capable of driving unprecedented levels of automation and business process optimisation.
 The generative AI market is projected to reach $75.7bn by 2028, reflecting the huge potential of these intelligent systems to reshape organisational productivity and efficiency.
Hybrid working models are rapidly transitioning from experimental approaches to standard operational practices.
Despite some organisations advocating for a return to traditional office environments, sophisticated collaboration technologies are enabling employees to work effectively across diverse settings. This flexibility represents more than a temporary trend – it signifies a fundamental reimagining of workplace dynamics and productivity.
Talent acquisition and development will face significant challenges as digital technologies continue to evolve.
Automation, AI, augmented reality, virtual reality and digital twin technologies are creating an urgent need for comprehensive workforce upskilling.
By 2025, proficiency in data management and generative AI tools will become an expected competency across various professional roles, not merely for technical positions.
Remote work and hybrid models are being embraced, driven by investments in digital infrastructure and upskilling initiatives. AI-driven human resources tools and collaboration platforms are helping to shape a more flexible and digitally enabled workforce in the Middle East.
GAMING
The gaming software industry is poised for significant growth, with projections indicating an expansion from $219bn in 2023 to $246bn by 2025, and an ambitious target of $337bn by 2030.
This trajectory is being driven by transformative technologies including AI, augmented reality, virtual reality, e-sports and cloud gaming.
 Co-streaming is emerging as a revolutionary approach to content delivery in the increasingly popular field of e-sports, enabling several streamers to broadcast events simultaneously.
In 2024, content created by co-streamers demonstrated significantly higher engagement rates compared to official streams, a trend expected to continue gaining momentum in 2025. This innovative approach is reshaping audience interaction and creating new monetisation opportunities.
The boundaries between streaming platforms and social media are becoming increasingly blurred. Platforms such as Twitch and YouTube are integrating with social media applications such as TikTok and Instagram, enabling real-time interactions and creating enhanced monetisation channels.
This convergence represents a fundamental transformation in how gaming content is created, shared and consumed.
The Middle East is rapidly emerging as a significant gaming ecosystem, with substantial investments in e-sports, mobile gaming and local game development. Saudi Arabia, in particular, is positioning itself as a global gaming hub through strategic initiatives like the Savvy Gaming Group.
FUTURE MOBILITY
The future of mobility is poised for a radical transformation, driven by technological innovation and evolving societal needs. Emerging trends such as autonomous vehicles, electric mobility, shared transportation, electrification and enhanced connectivity are reshaping how people and goods will move in the coming years.
 China is emerging as a global leader in both electric and autonomous vehicle technology, and in the case of the latter is positioning itself to be the first to deploy commercial Level 4 autonomous driving at scale.
Benefitting from supportive government policies and more relaxed regulatory environments, China is advancing faster than the US in autonomous vehicle development.
Breakthrough advances in battery technology are meanwhile set to unlock new frontiers in mobility, particularly for electric vertical take-off and landing (eVTOL) vehicles.
Innovations in lithium-ion and solid-state battery technologies are expected to make commercial eVTOL operations viable within the next 12-18 months. Solid-state batteries are particularly promising, offering superior energy efficiency, rapid charging capabilities and enhanced durability that could revolutionise aerial transportation.
The Middle East is likewise witnessing transformations in mobility that include the expansion of electric vehicles, autonomous transport pilots and innovative urban mobility solutions like smart public transit systems. Projects such as Neom in Saudi Arabia are setting the stage for futuristic transportation networks.

Autonomous vehicles and electric mobility are reshaping how people and goods will be transported
BATTERIES
The lithium-ion battery market is poised for substantial growth, with projections indicating an expansion from $130.5bn in 2023 to an impressive $408.3bn by 2035. This trajectory represents a consistent 10% annual growth rate, reflecting the increasing global demand for advanced energy storage solutions.
 Lithium-ion batteries will maintain their technological supremacy, characterised by superior energy density and rapid charging capabilities. Simultaneously, sodium-ion batteries are emerging as an intriguing alternative, attracting significant investment.
Geopolitical complexities and potential mineral supply disruptions – particularly concerning lithium, nickel and cobalt – are anticipated to create temporary global battery shortages. Despite ongoing advances in recycling technologies, these supply-chain challenges will pose significant obstacles for manufacturers and consumers alike.
With the push for renewable energy and electric vehicles, the Middle East is exploring advanced battery technologies. Efforts are being made to localise battery production and establish strategic partnerships for energy storage solutions that are tailored to the region’s climatic conditions.
Morocco is planning to establish the region’s first battery gigafactory, with a planned capacity of 20 gigawatt-hours annually, focusing on electric vehicle batteries.
Meanwhile, Saudi Arabia is also establishing battery manufacturing capabilities to meet growing demand for lithium-ion batteries due to investments in renewable energy projects and EV adoption.
MINERALS
The global demand for critical minerals is experiencing an unprecedented surge, driven by ambitious net-zero targets and the rapid adoption of transformative energy transition technologies. Lithium, copper, nickel, cobalt and rare earth elements have become pivotal resources in the production of electric vehicles, solar panels and wind farms, creating significant pressure on mineral prices and global supply chains.
China’s historical monopoly on rare earth element production has gradually diminished, with its market share dropping from a near-total 97% in 2010 to approximately 70% today.
 While other nations are pursuing diversification strategies, China remains a dominant force in both rare earth element production and refinement, maintaining substantial control over this critical market segment.
Latin America is emerging as a crucial player in the critical minerals landscape. Countries like Argentina, Bolivia and Chile boast extensive lithium reserves, while Brasil holds the world’s third-largest rare earth element reserves. This geological wealth positions the region as a potential game-changer in global mineral supply.
The Middle East region’s focus on economic diversification has likewise spurred interest in mining critical minerals. Significant mining projects are under way, including copper and gold projects in Oman and expansions of existing gold mines in Saudi Arabia.
There is a regional race to secure lithium deposits and access to other rare earth elements necessary for the technology and energy sectors.
GLOBALDATA REPORTS
This article was written by GlobalData Thematic Intelligence. Click here to see more thematic research.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Read the October 2026 MEED Business Review
30 September 2026
-
 Aramco receives interest for major gas processing plant
30 September 2026
-
 Libya refinery expected to be worth more than $600m
30 September 2026
-
 Joint venture wins $230m Ras El-Hekma buildings
30 September 2026
-
 Neom tenders Oxagon freight rail design
30 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Read the October 2026 MEED Business Review
30 September 2026
Download / Subscribe / 14-day trial access For all the talk of cancellations and cutbacks, Neom is still building – and its biggest completed project to date offers a clue to where the $500bn gigaproject is heading. Our October Agenda feature examines how Oxagon is moving to the centre of Neom’s strategy, as investment shifts towards projects with the potential to generate tangible commercial returns, from green hydrogen and ports to AI data centres and logistics infrastructure.
 Read the full analysis in the October issue of MEED Business Review.
As Neom reshapes its priorities, Saudi Arabia’s wider project market continues to show resilience. Contract awards have reached $68bn in 2026, despite regional conflict and economic uncertainty, with activity spanning energy, infrastructure, power and the future economy.
But with $91.5bn of projects completed this year, new awards will be crucial to maintaining momentum into 2027.
This edition also includes MEED’s 2026 power developer ranking, revealing the companies driving the region’s rapidly expanding power market.
The issue also explores key trends shaping the region, from AI’s growing demands on grid capacity and the implications of ICE Futures Abu Dhabi’s wind-down for Gulf commodity markets, to how the Hormuz crisis is redirecting oil companies’ focus to North Africa. Our Leadership feature asks whether the future city really needs to hang above the ground.
We hope our valued subscribers enjoy the October 2026 issue of MEED Business Review.
Must-read sections in the October 2026 issue of MEED Business Review include:
 > AGENDA: Oxagon takes centre stage at Neom
INDUSTRY REPORT:
MEED’s 2026 power developer ranking
> Regional power market diversifies
> Battery storage broadens IPP market> POWER: AI is creating a grid capacity problem
> LEGAL: What IFAD’s wind-down means for Gulf commodity markets
> OIL: Oil companies focus on North Africa amid Hormuz crisis
> LEADERSHIP: The future city does not need to hang above the ground
> SAUDI ARABIA MARKET FOCUS:
> COMMENT: Saudi projects hold steady
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflict
> DATABANK: Saudi data indicates project spending shift> MEED COMMENTS:
> Dubai Inc steps in as developers turn cautious
> Saudi Arabia redirects towards AI
> Kuwait plans biggest oil and gas contract award in 10 years
> Saudi Arabia battery storage awards provide fresh lift> GULF PROJECTS INDEX: Saudi Arabia and UAE lead Gulf index gains
> AUGUST 2026 CONTRACTS: Middle East contract awards
> ECONOMIC DATA: Data drives regional projects
> OPINION: The boomers’ last act
> BUSINESS OUTLOOK: Finance, oil and gas, construction, power and water contracts
To see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20134595/main.gif -
Aramco receives interest for major gas processing plant
30 September 2026
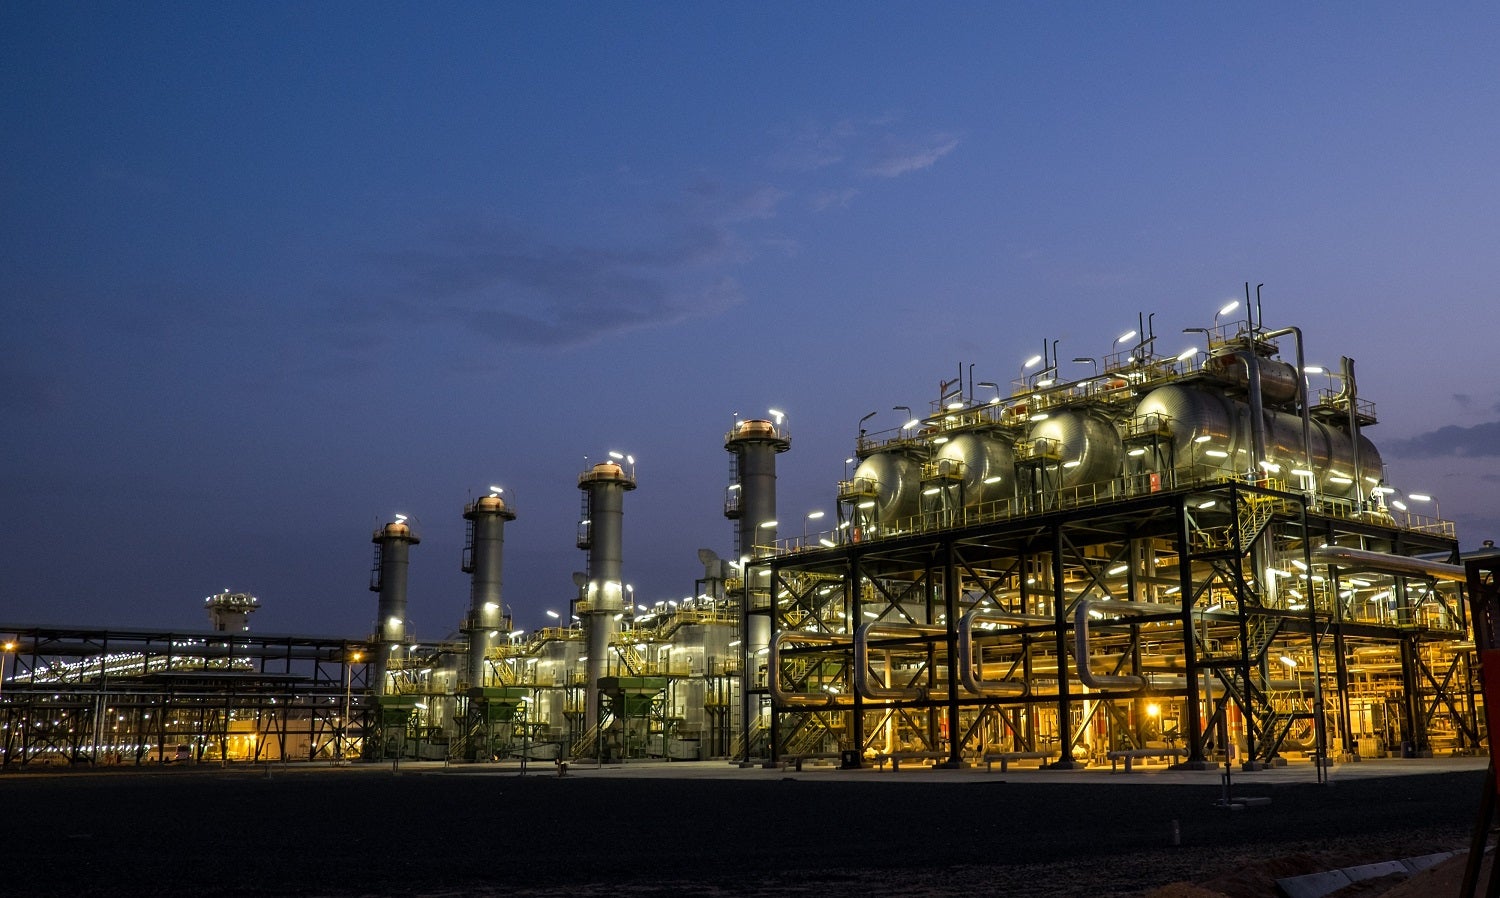
Saudi Aramco has received expressions of interest from contractors to participate in the main tendering exercise for a project to expand the Alhada gas processing plant, located about 85 kilometres northwest of Jubail in Saudi Arabia’s Eastern Province.
The Alhada gas processing plant expansion is critical to Aramco’s goal of increasing gas production capacity by 80% by 2030 from a 2021 baseline.
Aramco issued a solicitation of interest document for the main tendering exercise in early September, with contractors submitting responses by 17 September, sources told MEED.
The engineering, procurement and construction (EPC) scope of work has been divided into three main packages, sources said.
The first EPC package relates to the main gas treatment facilities, primarily three processing trains, along with:
- Three acid gas removal units
- Triethylene glycol (TEG) dehydration unit
- Two high-pressure and two low-pressure flares
- Two flare gas recovery units
- Two T&l flares
- Two burn pits
- A digital twin
The acid gas removal units will treat sour gas by removing hydrogen sulphide and carbon dioxide to produce sales gas, as well as acid-gas feed for the downstream acid gas enrichment unit and sulphur recovery unit.
The acid gas removal units will also process gas from the flare gas recovery units through a dedicated amine contactor to meet specifications for use as fuel gas. The TEG dehydration unit will then remove water from the treated gas to meet sales-gas specifications.
The project’s second EPC package covers the sulphur recovery units. The third package involves inlet channels for monoethylene glycol, as well as common utilities and supporting structures.
ALSO READ: Contractors express interest in sixth Jafurah expansion phase
https://image.digitalinsightresearch.in/uploads/NewsArticle/20127671/main4900.jpg -
Libya refinery expected to be worth more than $600m
30 September 2026
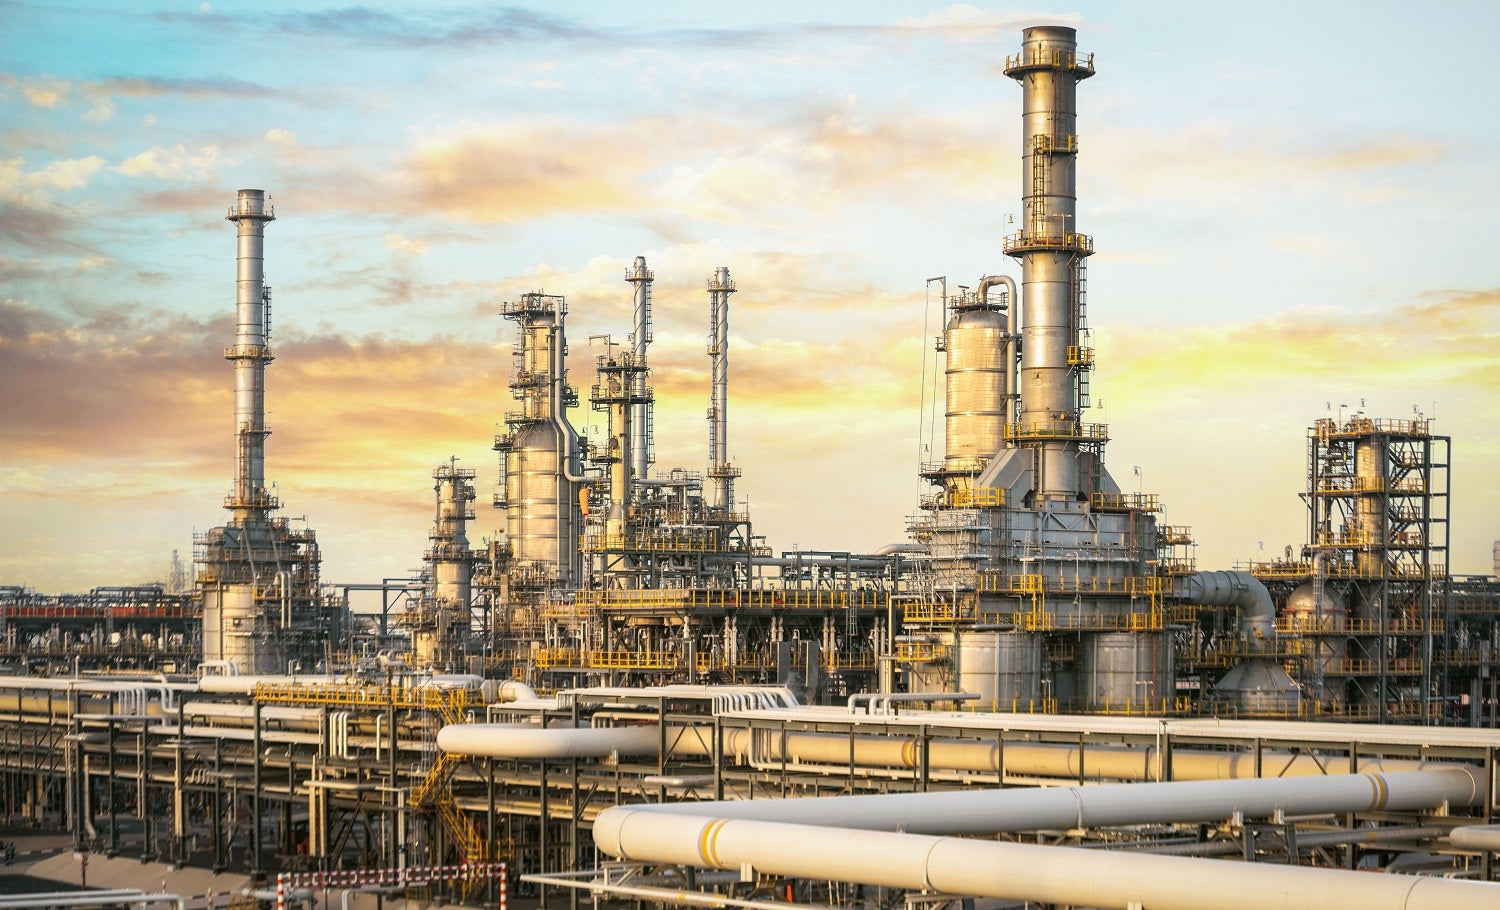
The main contract for Libya’s planned South Refinery project is expected to be worth more than $600m, according to industry sources.
The project, located in Ubari in southern Libya, has gained momentum over the past year. The main contract is expected to be procured under an engineering, procurement and construction (EPC) model.
In March, US-based engineering company KBR was awarded a contract by Zallaf Exploration, Production & Refining of Oil & Gas Company to provide project management and technical services for the project.
Under the terms of the contract, KBR will provide contract management, project management and supporting technical services throughout the project’s EPC phases.
The EPC work is expected to take 50 months, and the facility will be designed to process 30,000 barrels a day (b/d) of crude oil.
The refinery is expected to produce:
- Propane and butane for domestic and industrial uses
- Gasoline
- Kerosene
- Diesel
- Fuel oil
In March, KBR said that the project was aligned with its “long-standing commitment to advancing vital oil and gas infrastructure in Libya”.
Libya currently operates five main refineries with a combined nameplate capacity of 380,000 b/d, but actual throughput is closer to 180,000 b/d due to poor maintenance and damage from military clashes.
In addition to the South Refinery project, Libya also plans to upgrade the Zawiya refinery and carry out projects at the Serir, Brega, Tobruk and Ras Lanuf refineries.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20124329/main.jpg -
Joint venture wins $230m Ras El-Hekma buildings
30 September 2026
A joint venture of UK-based Innovo Build and Egypt’s Redcon Construction has won a contract worth about E£12bn ($230m) to carry out infrastructure and construction works for the DP03 East package of the Wadi Yemm development at Ras El-Hekma on Egypt’s North Coast.
Wadi Yemm is being developed by the UAE’s Modon Development as the first phase of its Ras El-Hekma masterplan, which will comprise 17 planned districts.
DP03 East has a built-up area of 323,000 square metres and is scheduled for completion within 21 months.
The scope of work includes more than 660 residential units – comprising standalone villas and townhouses – as well as public service areas, lakes, a commercial mall, landscaping and roadworks.
The delivery of units at Wadi Yemm is expected to begin in the third quarter of 2029.
Ras El-Hekma is located on a spur of land on Egypt’s northern Mediterranean coast, about 240 kilometres west of Alexandria.
Abu Dhabi-based holding company ADQ appointed Modon Holding as master developer for the Ras El-Hekma project in 2024. Modon will oversee the overall development, which covers more than 170 million square metres (sq m).
Modon will develop the first phase, covering 50 million sq m. The remaining 120 million sq m will be developed in partnership with private developers, under the supervision of the recently established ADQ subsidiary Ras El-Hekma Urban Development Project Company and Modon.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20123189/main.jpg -
 Hassan Allam wins $1bn Cairo mixed-use project deal
30 September 2026
Register for MEED’s 14-day trial access
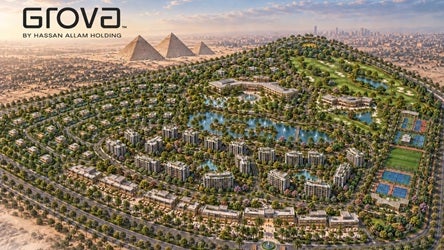
Grova Developments, the real estate development arm of Egypt’s Hassan Allam Holding, has awarded Hassan Allam Construction a $1bn contract to deliver the Grova Westfields project in West Cairo.
Hassan Allam Construction’s scope of work includes a 150-key five-star hotel, branded residences, luxury villas and apartments, as well as infrastructure and landscaping works.
The project spans about 1.2 million square metres and is being developed in partnership with the Egyptian Kuwaiti Company for Real Estate Development.
Broadway Malyan has been appointed to lead the master planning and architectural design.
In October last year, Hassan Allam Construction announced that it had won a $550m contract to build another mixed-use development spanning more than 128 hectares in New Cairo.
That development comprises villas, townhouses, commercial and office space, mixed-use buildings, infrastructure and other associated facilities.
Hassan Allam Properties is co-developing the project with Grova Developments.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20123048/main.jpeg