
Construction guard undergoes a shift
30 March 2026

The 2026 GCC Construction Contractor Ranking reflects two key trends. One is a growing trend that has been steadily rising across the region for more than a decade, while the other is a more recent development, which is now followed by the added uncertainty of a war with Iran.
The long-running trend is the rise of Chinese contractors. After years of Saudi-based dominance, Beijing’s China State Construction Engineering Corporation has claimed the top spot as the region’s most active contractor, with $10.399bn of work currently at the execution stage. This represents a notable rise for the firm, which was ranked second in 2025.
China State is not the only Chinese contractor in the top three. China Harbour Engineering Company ranks third, with $8.64bn of work under execution. Both firms are among China’s largest construction companies and have a longstanding presence in the region. In recent years, their success has encouraged other Chinese contractors to enter the market and win work. This trend is reflected in the national rankings, where other Chinese players feature prominently and may follow China State and China Harbour in rising to the top of the regional rankings.
Saudi reprioritisation
The other more recent trend affecting the 2026 ranking is the reprioritisation of projects in Saudi Arabia. The reassessment of the kingdom’s capital expenditure commitments led to a sharp decrease in contract awards during 2025. Combined with contractors completing work on projects secured immediately after the Covid-19 pandemic in 2021 and 2022, this has resulted in an overall decline in the value of work at the execution stage.”
This trend is reflected in China State’s figures. Although it moved up the rankings in 2026, the total value of work at the execution stage declined from $13.5bn to $10.4bn – a drop of about 30%.
The decline was even more pronounced for Saudi Arabia-based Nesma & Partners, which, unlike China State, does not have extensive operations in other GCC markets. Nesma moved to second place with $8.844bn of work under execution.
Despite the slowdown in activity in the kingdom, Saudi contractors continue to hold four of the top 10 positions, down from six in the 2025 ranking. El-Seif Engineering Contracting, Al-Bawani and Shibh Al-Jazira dropped out of the rankings, while Modern Building Leaders entered the top 10.
The other newcomer to the list is London-headquartered Innovo, which has rapidly become one of the most active building contractors in the UAE, with projects in Dubai and Abu Dhabi.
Bahrain
The Bahraini market remains dominated by large-scale social infrastructure and residential developments. In 2026, the ranking shows that contractors that have maintained a steady amount of work at the execution stage have risen up the ranking as other contractors complete projects and drop down the listing.
China Machinery Engineering Company maintains its position at the top of the ranking, with $689m of work under execution. Its primary focus continues to be the East Sitra housing scheme, a multi-phase project for the Ministry of Housing & Urban Planning that has involved the construction of thousands of housing units since 2019.
Nass Contracting has climbed back to second position with $639m. The local contractor was ranked fourth in 2025. Its portfolio is bolstered by significant infrastructure wins, including the Busaiteen Link scheme and the expansion of the RCSI Bahrain campus. Al-Hamad Building Contracting follows in third place with $610m, continuing its work on major Manama-based projects such as the Villamar residential complex.
In fourth position is the local Saleh Abdulla Kameshki & Sons, with $237m of work at the execution stage, followed by the local Kooheji Contractors in fifth place, with $230m of work at the execution stage. Kooheji was the seventh-ranked contractor in 2025.
Another local contractor that has risen up the ranking is Cebarco, which now sits in sixth place up from eighth, with $218m of work under execution. The local Almoayyed Contracting Group now sits in seventh place, down from sixth last year.
The other companies were not in the top 10 in 2025. They are CCT Constructor Group, Dar Al-Binaa Construction and Haji Hassan Group.
Kuwait
Turkiye’s Limak remains the top-ranked contractor in Kuwait, with $6.052bn of projects at the execution stage. The firm’s ranking reflects its work on the multibillion-dollar expansion of Kuwait International airport Terminal 2 and various road maintenance contracts for the Ministry of Public Works.
Chinese contractors have significantly increased their footprint in the country. China signed a series of agreements in 2023 that covered the delivery of some of Kuwait’s immediate development goals between 2024 and 2028. These agreements positioned Chinese companies to play a leading role in the Fourth Kuwait Master Plan 2040, and this is now shown in the contractor ranking for 2026.
China Communications Construction Company (CCCC) takes the second spot with $3.625bn, while China Gezhouba Group Construction holds third with $1.670bn.
In December last year, CCCC signed a $4bn agreement to develop the next phases of Kuwait’s Grand Mubarak Port on Boubyan Island. In March 2025, China Gezhouba won two contracts worth over $557m from the Public Authority for Housing Welfare for the South Saad Al-Abdullah residential project in Al-Jahra Governorate.
While Chinese contractors are playing a growing role, local players continue to manage substantial orderbooks, including Al-Ahmadiah with $1.071bn of work under execution, Khalid Ali Kharafi & Sons with $1.017bn of work, and Mohamed Abdulmohsin Al-Kharafi & Sons with $992m.
Oman
The Omani construction sector has changed at the top as the value of projects that contractors have at the execution stage has declined. Al-Adrak Trading & Contracting Company has moved into first place with $1.423bn of work. The top-ranked contractor in 2025 had $2.4bn of projects at the execution stage.
Al-Adrak was the eighth-ranked contractor in 2025, with $700m of projects at the execution stage.
The local contractor’s recent success has been anchored by securing work on Oman’s new generation of real estate projects. In May 2025, it secured a contract with Saudi developer Dar Global to build the villas and apartments at the Aida project.
Last year’s top-ranked contractor, Galfar Engineering & Contracting, is now in second place with $1.392bn. Galfar’s portfolio is headlined by the $1.5bn Hafeet Railway project connecting Oman and the UAE.
Sarooj Construction Company follows closely in third with $1.372bn, while India’s Larsen & Toubro maintains a strong presence in fourth with $906m. Overall, the market shows further softening in 2026, with contractors across the rest of the ranking holding less work than in 2025, when the 10th-ranked contractor, PowerChina, had $500m of projects under construction. In 2026, it has $250m.
Qatar
Qatar’s market is transitioning into a post-World Cup phase, focusing on social infrastructure and utility projects. Midmac Contracting Company has moved to the top spot with $2.082bn, nearly doubling the value of projects held by the second-ranked UCC Holding, which has $1.05bn.
Midmac’s return to the top 10 and the top of the ranking is largely due to it recently securing the $2bn Amiri flight facilities project at Hamad International airport, while UCC’s work remains centred on public-private partnership school schemes and road infrastructure for Ashghal.
The contracting joint venture of Qatari Diar and Saudi Binladin Group, QD-SBG Construction, is in third position with $843m. Its largest ongoing project is Al-Rafidain Mall for Abraaj Al-Mustaqbal RealEstate.
As the Qatari market transitions, four other contractors have moved into the top 10 in 2026. They are Badr Contracting & Trading with $534m of projects under execution, Al-Masaken Trading & Contracting Company with $400m, Marbu Contracting Company with $395m and Al-Mohannadi Group with $369m. As these contractors join the ranking, Consolidated Contractors Company (CCC), Shelter Contracting, InfraRoad Trading & Contracting Company, Changda Construction and American International Contractors Incorporated have moved out of the top 10.
Saudi Arabia
Much is changing in Saudi construction, but one constant is Nesma & Partners’ position at the top of the kingdom’s contractor ranking. While its position remains the same, the value of construction work that Nesma has under execution has decreased significantly when compared to 2025. This year, the contractor tops the Saudi ranking with nearly $9bn of work; last year it led with nearly $14bn of work.
Nesma is not the only contractor that has experienced a reduction. Second-placed Almabani has $6.5bn of projects under construction this year compared with $8.5bn in 2025. Third-placed contractor Saudi Binladin Group has maintained a total of about $6.5bn over 2025 and 2026, and this has allowed the Jeddah-based contractor to jump up from seventh position last year. The company is working on several high-profile projects in the kingdom, including the world’s tallest tower in Jeddah, which will be over 1,000 metres tall.
All the other contractors in the top 10 have similar declines in the value of their projects under execution. The exception is the local Building Contracting Company, which joins the top 10 in 10th position with $3.2bn of work. The 10th-ranked contractor in 2025 was China Harbour Engineering Corporation with $5.9bn of work, a total that in 2025 would have meant it would be the fourth-ranked contractor in 2026.
The reduction in work volumes reflects the ongoing reprioritisation of projects in Saudi Arabia. Government officials have said that while some projects, such as The Line at Neom, have slowed down, other projects, such as those for Expo 2030 Riyadh and the Fifa World Cup in 2034, will be accelerated.
UAE
Contractors in the UAE are benefitting from high levels of spending across public infrastructure and real estate. Following on from 2025, Trojan General Contracting continues to lead the UAE ranking. In 2026, it has $7.59bn of projects under execution, up slightly from the $7.2bn recorded in 2025. The Abu Dhabi-based contractor has work on public infrastructure schemes for Abu Dhabi-based government agencies, and this base is supplemented by work on real estate projects across the UAE.
China State Construction is in second position with $5.618bn under execution. The Beijing-based contractor has risen up the rankings from seventh position last year when it had $4bn of work under execution thanks to a series of deals for the construction of real estate and roads.
In third position is London-headquartered Innovo with $5.443bn of work at the execution stage. Innovo is working on major real estate developments in Abu Dhabi and Dubai and has quickly grown in recent years to become one of the key players in the UAE’s construction sector.
Sobha Constructions, the construction arm of property developer Sobha, is in fourth position with just over $5bn of work under execution. It is the main contractor for Sobha’s projects, which include the $763m Sobha Reserve and the $400m Skyvue Towers at Sobha Hartland 2.
The local Dutco, with $4.43bn of work under execution, has joined the top 10 in fifth position. The contractor has picked up a wide range of work on Dubai real estate projects over the past two years. Three other contractors in the ranking, Ginco, Unec and Arabian Construction Company, also work extensively on real estate projects in Dubai and Abu Dhabi. The local Alec is active in the real estate sector too. Additionally, it is working on a large data centre project in Abu Dhabi as well as the Wynn resort in Ras Al-Khaimah.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Algeria tenders 310km Tamanrasset railway
16 October 2026
-
 Joint venture wins $246m RCRC bridges contract
16 October 2026
-
 Humain tenders 100MW Riyadh AI data centre
16 October 2026
-
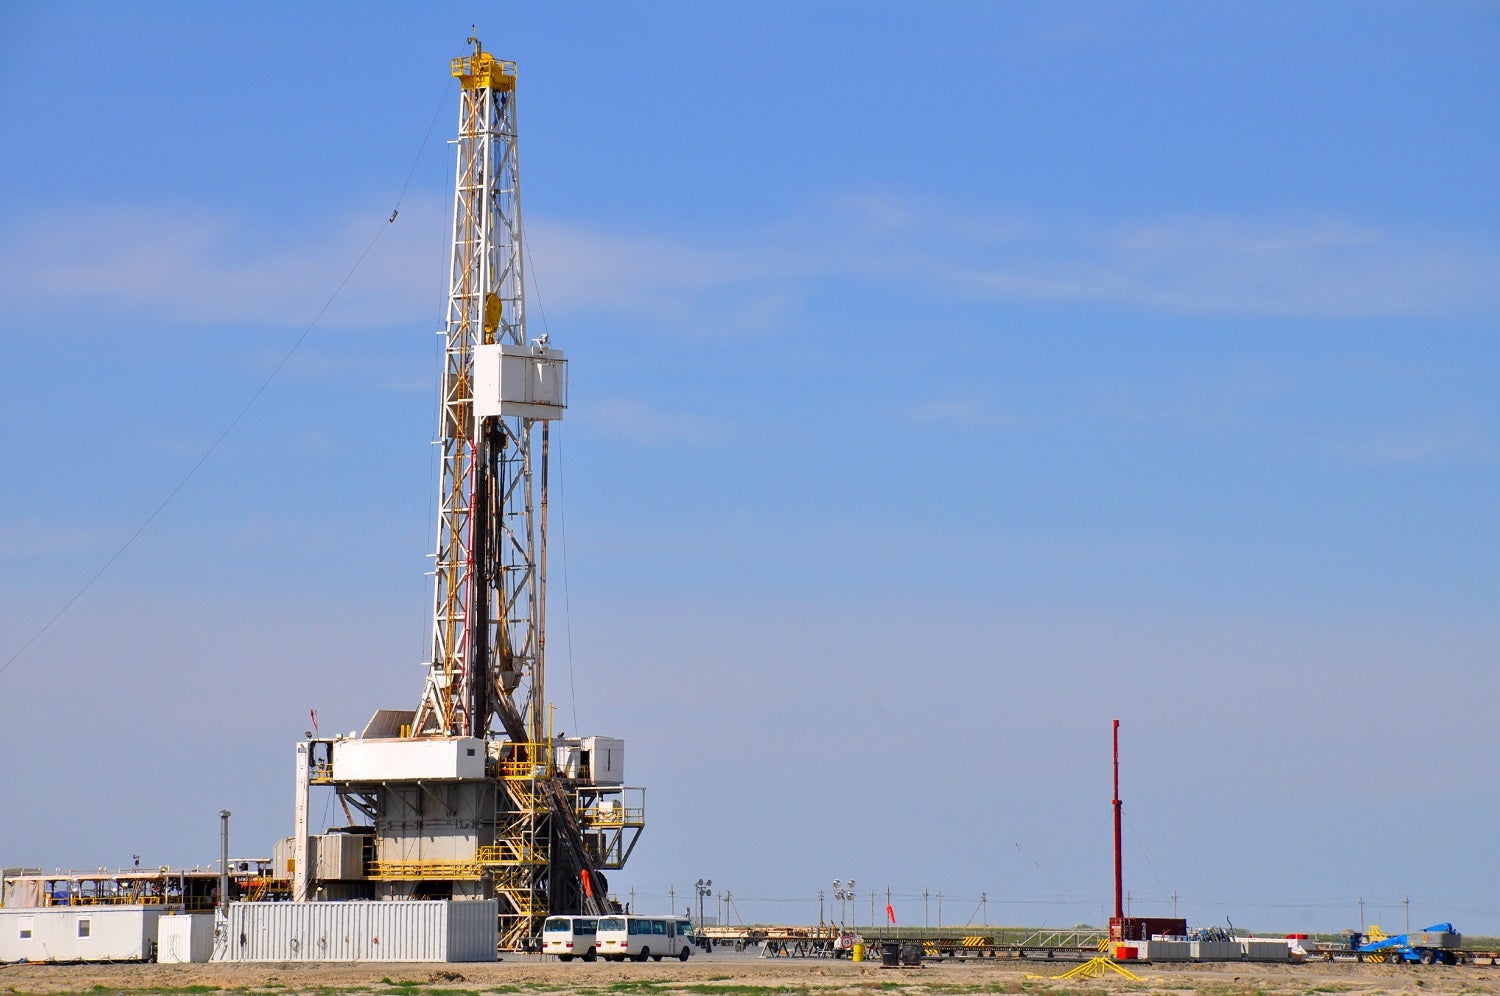 Adnoc Onshore seeks bids for Bu Hasa field EOR project
16 October 2026
-
 OTTCO issues tender for Oman oil storage park expansion
16 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends

Related Articles
-
Algeria tenders 310km Tamanrasset railway
16 October 2026
Algeria’s state railway project developer, Agence Nationale d’Etudes et de Suivi de la Realisation des Investissements Ferroviaires (Anesrif), has invited national and international contractors to bid for the construction of a 310-kilometre (km) railway line between Hotel Station and Moulay Lahcen Station.
The planned line is a key segment of the proposed railway corridor connecting El-Menea, In-Salah and Tamanrasset across the southern wilayas of In-Salah and Tamanrasset.
The tender notice was issued on 12 October, with bids due by 10 November.
The tender is open to single contractors and consortiums. To qualify, single firms must have executed at least 200km of new railway lines or track-doubling works since 2010, with accepted project certificates covering sections of at least 100km, along with a cumulative 800 metres of railway bridges with individual spans exceeding 30 metres.
Bidders must also provide at least two rail-tamping machines, two ballast regulators, and a project director with an engineering degree and at least five years of railway construction management experience.
From a commercial and classification perspective, single bidders and consortium leaders must hold a category-nine (IX) professional qualification in public works.
Bidders must also demonstrate an average annual turnover in construction of at least DZ260bn ($1.96bn) across the 2023-2025 financial period.
For joint ventures, the cumulative turnover of all members must meet the $1.96bn threshold, with the consortium leader accounting for at least $1.3bn.
Offers must be accompanied by a bid bond exceeding 1% of the total bid value for submissions exceeding $7.4m, with proposals remaining valid for 90 days beyond the submission date.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20665591/main.jpg -
Joint venture wins $246m RCRC bridges contract
16 October 2026
A joint venture of local contractor Mofarreh Group and Turkey-based Gulsan Holding has won an estimated SR923m ($246m) contract from the Royal Commission for Riyadh City (RCRC) to construct a series of grade-separated steel flyovers across the capital.
The contract, known as Package 2 (Groups 2 and 3), is part of RCRC’s urgent bridges programme under the wider project to build steel bridges at 10 junctions across Riyadh.
The works have a 12-month execution timeline to fast-track traffic decongestion across major arterial corridors.
The joint venture’s scope covers the engineering and construction of grade-separated steel bridge interchanges across seven key intersections:
- IC04: Al-Khair Road and King Salman Bin Abdulaziz Road
- IC05: Prince Turki Road and Imam Saud Road
- IC06: Al-Takhassosi Road and Saeed Al-Sulami Road
- IC07: Khurais Road and Al-Hareth Bin Abdullah Road
- IC08: Khurais Road and Ash-Sharq Road
- IC09: Khurais Road and Marmar Road
- IC10: Al-Kharj Road and Al-Hilla Road
The total length of the flyovers is 8.86 kilometres, excluding Junction IC10.
In addition to the structural steel superstructures, concrete bridge foundations, decks and approach ramps, the contract includes retaining walls, utility diversions, temporary phased traffic arrangements, associated roadworks, drainage networks, roadway lighting, intelligent transportation systems and landscaping.
The client received commercial proposals from several local and international contractors. Other bidders included:
- Masco
- Nesma & Partners
- Al-Omaier Trading & Contracting Company
- Yuksel Saudia
- Batco
- Modern Building Leaders
- Sapac
The urgent bridges initiative is part of Riyadh’s rapid transport infrastructure programme to improve traffic throughput, enhance safety and ease vehicular congestion across central and ring-road corridors ahead of major events, including Expo 2030 and the 2034 Fifa World Cup.
In July, Mofarreh Group and Turkiye’s Gulsan Holding formed a joint venture to bid for and deliver transport infrastructure projects in Riyadh for RCRC.
The joint venture said it will target road, bridge, viaduct and interchange projects.
Mofarreh will provide local market access and operational capacity, while Gulsan will contribute international experience in large-scale transport projects.
The companies said the new venture will support knowledge transfer and localisation, and promote the use of international engineering and construction standards aligned with Saudi Arabia’s Vision 2030 infrastructure and sustainability goals.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20663255/main.png -
Humain tenders 100MW Riyadh AI data centre
16 October 2026
Register for MEED’s 14-day trial access
Saudi artificial intelligence infrastructure developer Humain has issued a request for proposals for an engineering, procurement and construction (EPC) contract to deliver a 100MW artificial intelligence (AI) data centre facility in Riyadh’s Al-Saad area.
The tender was issued on 17 September, with bids due by 8 November.
The contract includes core-and-shell works; civil works; mechanical, electrical and plumbing installation; testing and commissioning; and site infrastructure across a 350,200-square-metre plot.
The project also includes an optional expansion phase that could raise total site capacity to 200MW.
The initial 100MW development is split into two equal 50MW phases, structured across two single-storey IT buildings housing four 25MW data halls.
Phase one targets a ready-for-service date by October 2028, followed by phase two in January 2029.
Under the optional phase three, an additional 100MW facility would be brought online by July 2029.
The data centre will be designed to support high-density graphics processing unit clusters and AI-compute workloads, with rack densities of 240kW to 250kW.
The facility will be built to Uptime Institute Tier III topology and LEED Silver standards as a baseline, targeting LEED Gold.
The operational design targets an annualised power usage effectiveness below 1.35.
Power will be delivered through four 33kV connections supplied by Saudi Electricity Company from two separate high-voltage/medium-voltage primary substations. The scope requires 15 transformers, 15 static 2,250kW IT uninterruptible power supply (UPS) units, and 450kW mechanical UPS systems with lithium-ion battery storage for each 25MW block.
Backup emergency diesel generators will be provided on an owner-furnished, contractor-installed basis, with the EPC contractor handling their installation, connection and testing. Fuel storage will provide 24 hours of autonomous run-time, split between on-site underground bulk tanks and generator belly tanks.
Thermal management combines air and liquid cooling. High-density server racks will be equipped with direct-to-chip liquid cooling loops using coolant distribution units and technical water distribution, paired with air-cooled chillers operating in dual high- and low-temperature loops, alongside fan-wall units.
The total construction timeline is capped at 25 months from site handover or contract signing, with pre-execution early mobilisation scheduled to start in January 2027.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20661045/main.jpg -
Adnoc Onshore seeks bids for Bu Hasa field EOR project
16 October 2026
Register for MEED’s 14-day trial access
The onshore oil and gas business of Abu Dhabi National Oil Company (Adnoc Onshore) has sought bids from contractors for a key project to increase the oil production capacity of the Bu Hasa oil field, primarily through enhanced oil recovery (EOR) techniques.
The main objective of the Bu Hasa-Shuaiba EOR Unit 1 (Phase 1) project is to achieve a targeted 70% increase in oil production, extend the Bu Hasa field development’s production plateau and maximise the field’s potential in an economical manner.
The project aims to confirm and validate the optimum EOR technology for the top-ranked reservoirs/units; assess incremental recovery on top of the improved oil recovery (IOR) wedge; extend the field plateau for as long as is economically feasible; and achieve an ultimate recovery factor of 70% from the Shuaiba reservoir. It will evaluate and execute the recommended EOR option through pattern phasing for any technology proven by Adnoc.
Adnoc Onshore is understood to have issued the tender for the project on 20 September, with an initial technical bid submission deadline of 8 October, according to sources. The client later extended the technical bid submission deadline to 17 October, sources told MEED.
The chosen contractor will execute the project under a hybrid contracting strategy comprising:
- A lump sum (turnkey) EPC scope covering the complete pipeline system from East Hub to the separation plant
- A call-out-based scope for execution of all WAG injector and WSW tie-in works
Unless otherwise specified, all activities defined under the contractor’s scope will be deemed included within the lump-sum contract price. This will cover engineering, procurement, construction, testing, pre-commissioning and support to commissioning for a complete and operable system.
At the Bu Hasa field development, three remote degassing stations (RDS-1/2/3) and two satellite stations, Bida Al-Qemzan and Huwaila, are currently in operation. Production from oil wells completed in Shuaiba, Thamama B, Thamama F, Bida Al-Qemzan and Huwaila is routed via individual flowlines to the three remote degassing stations and the Bida Al-Qemzan and Huwaila stations across different parts of the field.
Combined production from the wells at each of these stations is routed to the central degassing stations (CDS) via transfer lines ranging from 16 inches to 24 inches in diameter. In addition, some wells in the central part of the field are connected directly to the CDS.
Previous studies have identified carbon dioxide (CO2) flooding as a promising tertiary recovery mechanism in the Shuaiba reservoir, delivering incremental recovery on top of the IOR wedge (P5 project), extending the field plateau as long as economically feasible, and achieving an ultimate recovery factor of 70% from the Bu Hasa Shuaiba units.
Located 200 kilometres south of Abu Dhabi city, Bu Hasa is Adnoc Onshore’s westernmost producing field. It is one of Abu Dhabi's biggest onshore assets, with crude oil production capacity of 650,000 b/d. It is also one of the Adnoc Group’s oldest oil fields, having been discovered in 1962 and in production since May 1965.
As part of the ongoing Bu Hasa Integrated Field Development Project (BUIFDP), 13 new well pads and two pad hubs have been added to the field. Oil, gas and water produced at these sites will be collected at a central gathering facility, then sent through production headers and transfer lines to the CDS for processing.
Adnoc Onshore is the Adnoc Group’s largest oil-producing subsidiary, accounting for 2 million b/d of oil and about 7 billion cubic feet a day of associated gas production from four main onshore field developments in Abu Dhabi: Bab, Bu Hasa, North East Bab and South East.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20639750/main0548.jpg -
OTTCO issues tender for Oman oil storage park expansion
16 October 2026
Register for MEED’s 14-day trial access
Oman Tank Terminal Company (OTTCO) has issued the main tender for a major project related to the expansion of the Ras Markaz crude oil storage complex at Duqm, on the sultanate’s Arabian Sea coast.
The project, titled Trade Bridge, involves the engineering, procurement and construction (EPC) of eight large storage tanks, each with a capacity of 650,000 barrels. This will increase the Ras Markaz terminal’s total storage capacity by 5.2 million barrels.
The project represents the next expansion phase (phase 1.4) of the Ras Markaz oil storage terminal within the Special Economic Zone at Duqm (Sezad).
State-owned OTTCO issued the prequalification notice for the project on 28 July, with contractors submitting initial responses by 4 August and final responses by 19 August, MEED previously reported.
According to sources, OTTCO issued the main tender for EPC works on Project Trade Bridge in the weeks following completion of the prequalification exercise.
The following contractors, among others, are understood to have been prequalified by OTTCO to bid for Project Trade Bridge:
- China Petroleum Pipeline Engineering Company (China)
- China Tianchen Engineering Corporation (China)
- Daqing Oilfield Construction Group Company (China)
- Enppi Muscat (local branch of Egypt-based Enppi)
- Gulf Petrochemical Services & Trading (Oman)
- Hualu Engineering & Technology Company (China)
- Rotary Engineering (Singapore)
- Sinopec Ningbo Engineering Company (China)
OTTCO commissioned the first phase of the Ras Markaz crude oil storage park, covering 10 square kilometres and with a capacity of 26.7 million barrels, in December 2022.
The storage facility has two parts. The first is a marine services area, which includes a floating station for crude imports and exports. This zone is about 7 kilometres offshore and is connected via two 42-inch pipelines and associated facilities.
In water depths of up to 42 metres, the floating station can accommodate very large crude carriers. It is linked to four main pumps that transfer crude oil to the storage area, which is located more than 120 metres above sea level. OTTCO could add pumps at a later stage to keep pace with future demand for oil storage.
The second part of the storage facility features oil pumping systems, water treatment facilities, reservoirs, power station networks and other associated systems.
Region’s largest oil storage park
OTTCO will build the Ras Markaz oil storage facility in five phases over several years across an area of about 40 square kilometres, for which it signed a land agreement with Sezad in July 2017.
It will be able to hold 200 million barrels of crude a year. Total investment in the scheme is understood to be $5.2bn.
The storage terminal in the first phase of the Ras Markaz facility is connected to the estimated $7bn Duqm refinery and other oil-derivatives production plants at Sezad via a pipeline that will supply crude feedstock to the refinery when required.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20638090/main0749.jpg