Bridging the infrastructure capacity gap
2 April 2024

The Middle East and North Africa (Mena) region faces a massive infrastructure gap, with estimates of the shortfall ranging from $75bn to $100bn annually.
This translates to a cumulative need for $2-2.5tn in infrastructure investment alone by 2050. Bridging this funding gap will require a drastic increase in the level of investment.
In 2020, the World Bank stated that Mena countries needed to spend at least 8.2% of GDP to meet their infrastructure goals through to 2030. However, it had been averaging a spend of just 3% over the prior decade – mostly from public sector funds, alongside multilateral and bilateral debt financing.
In the intervening years, the additional fiscal constraints imposed by the pandemic and global economic shocks, such as food price inflation, have further hindered regional public spending on infrastructure.
In 2023, the ICD-Refinitiv OIC Infrastructure Outlook valued the region’s outstanding funding gap for infrastructure development at $994bn. The gaps included a $685bn shortfall in investment in road infrastructure; a $111bn funding gap in the water sector; a $65bn gap in telecoms; $47bn in rail; $34bn in port infrastructure; $27bn in electricity network investment; and $25bn in airport infrastructure investment.
This funding gap has real, material impacts on economic prosperity and the prospects for economic growth. The shortfall in investment in road infrastructure, for example, is estimated to cost the Mena region a staggering 5.5% in GDP a year due to inefficiency and accidents, according to the World Bank.
A 2020 study in the Review of Middle East Economics and Finance found that manufacturing firms in the Mena region faced the most severe durations of power outages a month of any region, at 64 hours a month. The perceived value of the business losses due to these power outages was estimated to be around 4.8% of total sales.
Meeting the region’s annual investment needs could generate about 2 million direct jobs and 2.5 million direct, indirect and induced infrastructure-related jobs, according to the OECD.
This is critical when half of the region’s population is under 24 years old, and 29% are not in employment, education or training, as per the OECD figures.
Another very tangible infrastructure gap is water capacity. The current annual water shortage in the Mena region is about 42 cubic kilometres, but by 2050, this is projected to grow fivefold to 199 cubic kilometres a year under average climate scenarios and potentially up to 283 cubic kilometres a year under drier conditions.
These examples highlight the need for substantial investments to bridge the infrastructure deficiencies, ensure the conditions for economic growth, and enhance overall sustainability in the Mena region.
To address the challenges, a comprehensive and multi-faceted approach is needed to incentivise the private sector to support regional infrastructure investments. This includes governments establishing clear policy directions and regulatory frameworks to attract private capital mobilisation.
This funding gap has real, material impacts on economic prosperity and the prospects for economic growth
Technological adaptation
In parallel with the need for governments to proactively improve the conditions for investment, the delivery of future infrastructure requirements also anticipates the adoption of emerging technology.
The goal of many countries to achieve net zero by 2050 also layers further complexity onto existing infrastructure challenges. Regional efforts such as the Middle East Green Initiative and the Circular Carbon Economy framework nevertheless demonstrate the region’s commitment to achieving its net-zero targets.
Reaching net zero will entail building infrastructure that is not just bigger and better, but smarter. At the Global Infrastructure Initiative Summit hosted by McKinsey in Dubai in February, disruptive thinking and technology were identified as vital to the industry’s evolution to meet the needs of a net-zero future.
Industry leaders called for a nuts-and-bolts overhaul of the industry from the bottom up, with more sustainable alternatives to even centuries-old staples such as Portland cement and rebar. The digitalisation of the industry and the advent of machine-learning and AI also hold huge potential for cutting waste and designing more organic, efficient structures.
The summit highlighted that solving future infrastructure requirements will also likely necessitate overcoming technology hurdles and bringing costs down through research and development, much like the costs of solar power or reverse osmosis desalination have come down in the region.
Alistair Green, a senior partner in McKinsey’s global infrastructure practice, pointed to the technologies that “are not at conviction, yet: the technology hasn’t even really been proven outside of the lab – like flow batteries, which are an alternative to lithium-ion batteries that can be used for grid-scale storage of long duration, energy storage. This is a technology problem that we’re actively investing in researching in order to bring the costs down.”
Strategy& and engineering consultancy Dar recently reported that sustainable construction technologies can potentially reduce lifecycle emissions from the Mena region’s $2tn construction pipeline through to 2035 by 50%-60% for planned projects. Simple changes can be highly effective, such as incorporating dynamic facades into building designs, which can deliver energy savings of up to 55% in hot countries.
The key is the level of innovation, not the level of technology. In the right application, a low-tech solution may be more efficient. If a low-tech solution is scalable, it is also likely to be more cost-efficient.
In the arid Ait Baamrane region of Morocco, a 2015 project by the NGO Dar Si Hmad has created the world’s largest operational fog-harvesting system, providing potable water using a system of shore-side nets that capture and condense the fog rolling in off the ocean. Launched after a decade of research, the system yields approximately 22 litres of water a day for each square metre of net. It demonstrates that infrastructure does not need to be expensive or complex to have a positive sustainability outcome.
The most pressing need for the Mena region is to improve the attractiveness of its infrastructure investment opportunities
Accessing finance
Without sufficient finance, the effectiveness of infrastructure development, including technological innovation within the sector, will be throttled. The most pressing need for the Mena region is to improve the attractiveness of its infrastructure investment opportunities.
Many governments, especially in the Gulf, have been focused on encouraging the private sector through better and wider public-private partnership (PPP) arrangements, with mixed results. Some countries have struggled to deliver PPP frameworks with sufficient commercial appeal and bankability, a problem usually linked to unattractive risk allocations on the private sector side.
Nevertheless, the mobilisation of PPPs and the creation of more transparent and efficient regulatory frameworks around them are routinely identified as vital for attracting and mobilising private capital.
The delivery of more sustainable infrastructure with a view to net-zero targets also brings the potential to tap into green finance, including green bonds and sharia-compliant sukuk. Projects targeted towards carbon neutrality open themselves up to more diverse avenues of potential finance, including international climate mitigation and adaptation funds.
Multilateral development banks, such as the Asian Infrastructure Investment Bank, support initiatives like the Catalyst Mena Climate Fund 2, which works to mobilise private capital for infrastructure projects focused on renewable energy, sustainable utility schemes and green hydrogen capacity.
Governments in the region are also taking steps to mobilise climate finance by issuing green sovereign bonds and sukuk to fund clean transportation, waste management and green building schemes.
The UAE’s infrastructure development is guided by the Green Agenda 2030 policy framework. Under this aegis, UAE banks, including Mashreq Bank and First Abu Dhabi Bank, have pledged to mobilise $270bn in green financing by 2030 for environmentally impactful projects.
Infrastructure financing schemes are an important step towards drawing more private sector liquidity into the infrastructure industry, but it is also just a start compared to what will be required to deliver the region’s infrastructure needs.
Deep regional inequality also needs to be addressed. While countries such as Saudi Arabia and the UAE may currently be meeting the World Bank’s 8.2% of GDP infrastructure spending targets, the region’s hydrocarbon importers will likely need far more outside assistance.
For the region as a whole to thrive, countries will also need to work together and synergistically to deliver holistic infrastructure roadmaps. Just as the GCC is working together to deliver the Gulf Railway, the Levant and North Africa must work together to develop their shared infrastructure.
Only through cooperation and joint initiatives will the Mena region stand to bridge its infrastructure gap.
 Gulf construction holds huge emissions savings potential

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Rabigh 2 IPP expansion secures $2.58bn financing
5 October 2026
-
 Contractors submit bids for Libya refinery
5 October 2026
-
 Dubai tenders sewage and stormwater projects
5 October 2026
-
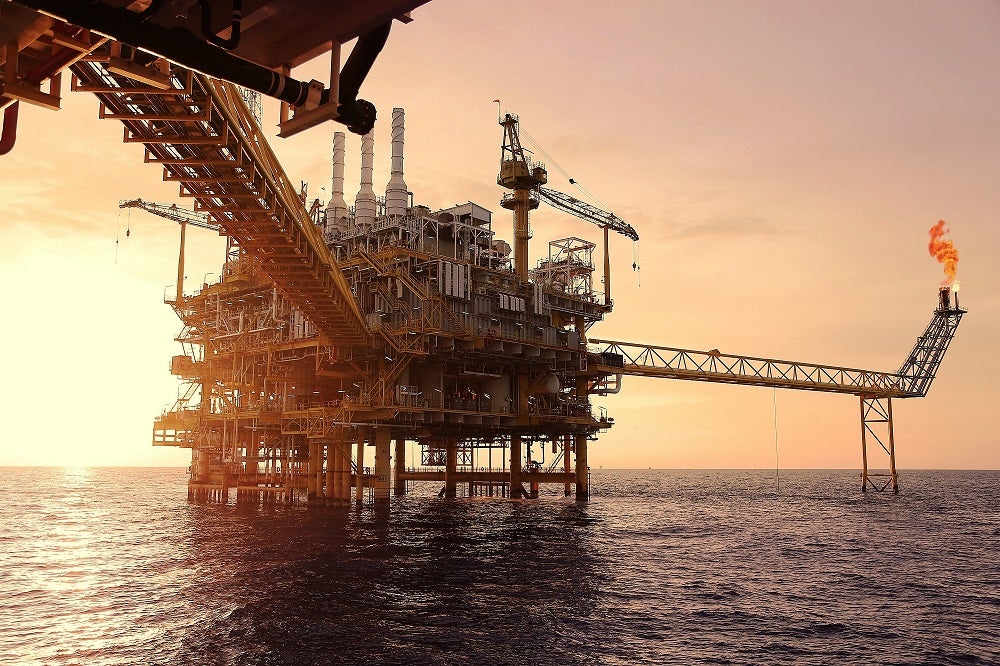 QatarEnergy gives North Field West topside bidders more time
2 October 2026
-
 Egypt implements oil and gas storage projects worth $1.1bn
2 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Rabigh 2 IPP expansion secures $2.58bn financing
5 October 2026
Saudi Arabia's Rabigh 2 combined-cycle gas-turbine (CCGT) independent power project (IPP) expansion has reached financial close.
In a disclosure to the Saudi Exchange, Acwa said it had secured SR9.69bn ($2.58bn) in long-term financing for the project, which has a generation capacity of 2,313.5MW.
In April, MEED reported that Acwa and Saudi Energy (formerly Saudi Electricity Company) had signed a 31-year power purchase agreement (PPA) with Saudi Arabia’s principal buyer, Saudi Power Procurement Company (SPPC), for the project.
The project involves the development of a combined-cycle gas turbine (CCGT) plant in the Mecca region. It is being developed by Al-Morjan Two Electricity Company, with Acwa and Saudi Energy each owning a 40% stake in the project.
The contract is valued at SR11.5bn ($3.07bn), the companies said in separate stock exchange filings at the time. The carbon-capture-ready power plant will be implemented under a build, own and operate contract.
The financing has a tenor of about 34 years and was provided by a consortium of local, regional and international lenders.
The lenders are:
- Abu Dhabi Commercial Bank
- Alinma Bank
- Boubyan Bank
- China Minsheng Banking Corporation, Hong Kong Branch
- Commercial Bank of Dubai
- HSBC Bank Middle East
- Industrial and Commercial Bank of China
- Industrial Bank, Beijing Branch
- National Bank of Greece, Cyprus
- Riyad Bank
- Saudi Awwal Bank
- Saudi National Bank
- Standard Chartered Bank, Taiwan
- Sumitomo Mitsui Trust Bank, London Branch
The project scope also includes financing and expansion of a 380kV electrical substation.
According to regional project tracker MEED Projects, construction works have commenced on the project and a joint venture of Egypt's Elsewedy Electric and China's Sinohydro has been working as the main contractor.
Rabigh 1 extension
In January, Saudi Energy announced a spearate energy conversion agreement with SPPC for the purchase of electricity from the Rabigh 1 power plant expansion.
The contract is valued at SR5.33bn ($1.42bn).
It covers the development, financing, construction, ownership and operation of the gas-fired power plant, which will have a generation capacity of 1,179MW.
A joint venture of Elsewedy Electric and Germany’s Siemens Energy is undertaking the engineering, procurement and construction work for the project, which is expected to be completed by the end of 2026.
US/India-based Synergy Consulting is the financial advisory consultant to Saudi Energy on this project.
Acwa also recently started initial commercial operations at the Taiba 1 and Qassim 1 combined-cycle gas turbine (CCGT) power plants, as reported by MEED.
The plants have a combined generation capacity of about 3.8GW and are two of four projects procured under the first round of Saudi Arabia’s gas-fired independent power producer (IPP) programme by Saudi Power Procurement Company.
A team of Saudi Energy, formerly Saudi Electricity Company, and Acwa won the contract to develop and operate the projects in 2023.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20270643/main.jpg -
Contractors submit bids for Libya refinery
5 October 2026
Bids have been submitted for the main contract for Libya’s planned South Refinery project and are currently under technical evaluation, according to industry sources.
The project, located in Ubari in southern Libya, has gained momentum over the past year, and the main contract is anticipated to be worth more than $600m.
The main contract is expected to use the engineering, procurement and construction (EPC) model.
The EPC work is expected to take 50 months, and the facility will be designed to process 30,000 barrels a day (b/d) of crude oil.
In March, US-based engineering company KBR was awarded a contract by Zallaf Exploration, Production & Refining of Oil & Gas Company to provide project management and technical services for the project.
Under the terms of the contract, KBR will provide contract management, project management and supporting technical services throughout the project’s EPC phases.
The refinery is expected to produce:
- Propane and butane for domestic and industrial uses
- Gasoline
- Kerosene
- Diesel
- Fuel oil
In March, KBR said that the project was aligned with its “long-standing commitment to advancing vital oil and gas infrastructure in Libya”.
Libya currently operates five main refineries with a combined nameplate capacity of 380,000 b/d, but actual throughput is closer to 180,000 b/d due to poor maintenance and damage from military clashes.
In addition to the South Refinery project, Libya also plans to upgrade the Zawiya refinery and carry out projects at the Serir, Brega, Tobruk and Ras Lanuf refineries.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20267178/main.jpg -
Dubai tenders sewage and stormwater projects
5 October 2026
Register for MEED’s 14-day trial access
Dubai Municipality has issued tenders for a 3,000-cubic-metre-a-day sewage treatment plant (STP) and a strategic stormwater drainage system.
The first tender is for the design and construction of the Al-Lissaily STP.
The project, identified as DS311/1, covers the design, supply, installation, construction and commissioning of the plant in the Al-Lissaily area.
Dubai Municipality’s Sewerage and Recycled Water Projects Department is issuing the tender. The bid submission deadline is 29 October.
The facility is located near residential communities and farming areas. The project will therefore include measures for odour control, treated effluent quality, noise mitigation and environmental performance.
The municipality said the plant will incorporate landscaping and architectural features designed to reflect Dubai’s heritage character and the surrounding farming environment.
The second tender is for project TF-07-C1, a strategic stormwater drainage system covering more than 100 million square metres.
The project area extends from Sheikh Mohammed Bin Zayed Road (E311) to the north to Emirates Road (E611) to the south, and from Expo Road in the west to Dubailand in the east.
The project will provide stormwater infrastructure and service connections for more than 20 private developers, as well as the Al-Yalayis 5 community.
It will also support major roads in the Jebel Ali area, including Sheikh Mohammed Bin Zayed Road, Emirates Road, Sheikh Zayed Road, Sheikh Zayed Bin Hamdan Al-Nahyan Road, Hessa Street, Al-Yalayis Road and Al-Fay Road.
The scope includes a major stormwater gravity drainage system, with pipeline diameters of up to 3,000mm.
Dubai Municipality said the project is intended to increase drainage capacity, improve relief for existing and new stormwater systems, and strengthen protection against extreme rainfall events.
The bid submission deadline is 22 October.
The municipality also recently invited contractors to bid for a contract to upgrade and rehabilitate the stormwater system in Abu Hail.
The project comprises a stormwater pumping station with a total discharge capacity of 26 cubic metres a second. It is estimated to cost up to $163m.
Bid submissions are due by 15 October.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20266881/main.jpg -
QatarEnergy gives North Field West topside bidders more time
2 October 2026
QatarEnergy has granted contractors more time to prepare bids for a tender covering the engineering, procurement, construction and installation (EPCI) of large platforms for the North Field gas field in Qatari waters.
Contractors now have until 12 October to submit technical bids for the project, according to sources. Commercial bids are currently due on 10 November.
The following contractors, among others, are understood to be bidding for the North Field West (NFW) production deck modules (PDMs) tender:
- China Offshore Oil Engineering Company (China)
- Larsen & Toubro Energy Hydrocarbon (India)
- McDermott (US)
- Saipem (Italy)
The core scope comprises the EPCI of four PDMs and associated structures. The PDMs will increase gas production from North Field reservoirs and provide additional gas feedstock for the NFW liquefied natural gas (LNG) development.
The tender, issued earlier this year, forms part of the wider NFW project, the third and final phase of the state enterprise’s North Field LNG expansion programme.
The previous deadlines for technical bids were 30 August, 15 September and 28 September, while commercial bids were previously due on 25 October, as MEED reported.
Before issuing the PDMs tender, QatarEnergy awarded US firm McDermott a contract for the EPCI of four offshore jackets that will also support gas feedstock supply for the NFW LNG project. The contract is estimated to be worth about $200m, MEED reported in January.
North Field LNG expansion
QatarEnergy is advancing the three phases of its estimated $40bn North Field LNG expansion project. EPC works on all three projects are progressing.
QatarEnergy is understood to have committed nearly $30bn to the first two phases – North Field East (NFE) and North Field South (NFS) – which will lift Qatar’s LNG production capacity from 77.5 million tonnes a year (t/y) to 126 million t/y by 2028.
QatarEnergy awarded the main EPC contracts for NFE in 2021. The project was intended to raise LNG output to 110 million t/y by 2025. The $13bn EPC package – covering the EPCI of four LNG trains, each with a capacity of 8 million t/y – was awarded in February 2021 to a consortium of Japan’s Chiyoda and France’s Technip Energies.
In May 2023, QatarEnergy awarded the $10bn main EPC contract for NFS to a consortium of Technip Energies and Consolidated Contractors Company (CCC). The contract includes two LNG trains, each with a capacity of 7.8 million t/y.
Once fully operational, the first two phases are expected to add 48 million t/y of LNG supply to the global market.
QatarEnergy took the final investment decision on NFW earlier this year, awarding an EPC contract estimated at $8bn to a joint venture comprising Technip Energies, CCC and Gulf Asia Contracting in February.
Chiyoda carried out the front-end engineering and design work for the NFW LNG project.
The NFW scope covers the EPC of two LNG trains with a combined capacity of 16 million t/y, as well as associated facilities for gas treatment, natural gas liquids recovery and helium extraction.
In addition to LNG, NFW is expected to produce about 175,000 barrels of oil equivalent a day of condensate, ethane and liquefied petroleum gas.
With all three phases under EPC execution – and NFE scheduled for commissioning later this year – QatarEnergy is positioning itself to remain one of the world’s largest LNG suppliers in the long term.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20208200/main.jpg -
Egypt implements oil and gas storage projects worth $1.1bn
2 October 2026
Egypt is implementing oil and gas storage projects worth a total of £E54bn ($1.1bn), according to a statement released by the country’s cabinet.
Active developments include expanding El-Hamra Petroleum Port in El-Alamein on the Mediterranean coast, as well as building a jet-fuel storage and transport hub at the Badr depot in Cairo.
Other projects include constructing new storage tanks at refinery complexes in Amreya, Alexandria; Assiut; and Cairo.
Over the past 12 years, Egypt has built 84 petroleum storage facilities with a total capacity of 5.2 million tonnes, the cabinet statement said.
Egypt has invested £E42.7bn ($880m) in developing these facilities, with the aim of bolstering domestic energy security.
Completed infrastructure projects include facilities in Sohag (Upper Egypt) and Alexandria.
They also include offshore terminal and storage facilities, a liquid bulk station in Ain Sokhna, and strategic crude oil storage tanks across the country.
Storage facilities have become a strategic priority for Egypt since the US and Israel attacked Iran on 28 February, triggering a regional war that has disrupted shipping through the Strait of Hormuz.
The disruption has made imports of hydrocarbon products into Egypt less predictable, increasing the importance of strategic stockpiles.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20208195/main.jpg