
Activity ramps up in Syria’s oil and gas sector
3 June 2026

Foreign interest in Syria’s oil and gas sector is growing as the government moves to revive the industry and elevated global energy prices improve the economics of new developments.
A series of agreements signed in recent months has attracted some of the world’s largest energy companies, raising expectations that investment and production could accelerate.
However, despite growing optimism, significant security, financial and regulatory challenges remain, which could constrain the pace of growth for years to come.
Military control
Optimism among foreign businesses about potential opportunities in the country was boosted in January this year when Syria’s central government regained control of most of the country’s oil and gas assets.
On 13 January 2026, the Syrian government launched an offensive against the Kurdish-led Syrian Democratic Forces (SDF) in the territories of the Democratic Autonomous Administration of North and East Syria.
The offensive was initially focused on eastern Aleppo Governorate, around the towns of Deir Hafer and Maskanah, and was expanded on 17 January to include Raqqa, Deir ez-Zor and Al-Hasakah Governorates.
The offensive eventually led to Syria’s Omar and Conoco fields being seized, as well as the Tanak, Rmeilan and Suwaydiyah fields.
The Omar field is Syria’s largest oil field and the Conoco field hosts Syria’s largest gas processing plant, which previously supplied several power stations, including the Jandar plant in Homs, one of the country’s largest.
Before the outbreak of the Syrian civil war in 2011, this field produced about 10 million cubic metres of natural gas a day.
On 18 January, an agreement was signed under which Damascus assumed administrative and security control over all major oil and gas assets previously held by the SDF in the northeast of the country.
Wider market
The push to take control of the oil and gas assets came ahead of the US and Israel attacking Iran on 28 February, which led to a regional conflict and disrupted shipping through the Strait of Hormuz.
Disruption in the waterway – which normally transports about 20 million barrels a day (b/d) of oil and refined products, as well as around 20% of the world’s liquefied natural gas – triggered a surge in global energy prices and sent oil companies scrambling to develop resources that did not rely on the strait as an export route.
Syria is increasingly being viewed as a potential option for major oil and gas development projects due to its significant unrealised reserves and its geographic position across the Mediterranean from consumer markets in Europe.
Syria’s production currently stands at around 110,000 b/d, down from a peak of 380,000 b/d in 2011, according to a report published by the US-Syria Business Council in April.
The country’s recoverable oil reserves are estimated at 2.5 billion barrels, and Syria also has significant gas reserves.
In April, Yousef Qiblawy, chief executive of the state-owned Syria Petroleum Company (SPC), said his organisation aimed to double national production before 2027 and boost output to 800,000 b/d by the end of 2029, not including offshore production.
He said: “Before the takeover of the northeast, we were producing 10,000-15,000 b/d.
“Currently, we are producing 100,000 b/d, and the plan now is to double this production number by the end of this year.”
He also expressed optimism about the outlook for projects in Syria’s portion of the Mediterranean Sea, saying: “New offshore and onshore exploration is also starting … there are 15 or 17 brand new green blocks, untouched in Syria, with huge reservoirs of oil mainly, and some gas.”
So far, no offshore wells have been drilled in Syrian waters.
In 2013, Russia’s Soyuzneftegaz signed an offshore exploration agreement with Damascus, but the project was abandoned during the civil war and never progressed to drilling.
Making deals
In recent months, a range of significant deals and meetings has raised expectations for the future of Syria’s oil and gas sector.
On 11 May, SPC announced plans for Syria’s first-ever offshore oil and gas exploration project.
The deep-water project is being carried out in partnership with US-based Chevron and Qatar’s UCC Holding.
SPC said that it had, together with Chevron and UCC Holding, defined the boundaries of the offshore block, paving the way for finalising contracts and starting technical operations this year.
The three companies previously signed a preliminary deal in February to evaluate offshore oil and gas exploration in Syrian waters.
On 12 May, France’s TotalEnergies, state-owned QatarEnergy and US-based ConocoPhillips signed a memorandum of understanding (MoU) with SPC relating to the exploration of Syria’s offshore Block 3.
Under the terms of the preliminary deal, the companies will carry out a technical review of the area.
The agreement also established a framework for technical and commercial discussions related to exploration activities on the block.
ConocoPhillips also signed another MoU in November last year, along with Houston-headquartered Novaterra Energy, focused on developing several gas fields and launching exploration programmes.
This MoU included an agreement to rehabilitate the gas plant at the Conoco field in Deir ez-Zor province.
At the time, Qiblawy said the agreement was expected to boost the country’s gas production by 4-5 million cubic metres a day within a year.
On 8 May, the Croatian oil company INA and Hungary’s MOL announced that they had held a series of meetings with SPC focused on exploring options to restart INA’s oil and gas operations in Syria.
They said a joint technical team established by INA and SPC was assessing the feasibility of INA resuming operations on its Syrian concessions by evaluating operational, technical, commercial and regulatory conditions.
In 2011, oil and gas production at INA’s Syrian concessions had reached 37,300 barrels of oil equivalent a day.
By the time the company suspended operations in Syria in 2012, it had invested approximately $1.1bn in the country and had built a gas processing plant at the Hayan gas field.
Resuming activities
In April, the managing director of London-headquartered met with Syria’s president, Ahmed Al-Sharaa.
Gulfsands is the official operator of Syria’s Block 26, but for 15 years after the start of the Syrian civil war, it could not access the asset.
The company declared force majeure in late 2011 and, until recently, it was under the control of the Kurdish-led SDF.
In a statement released after the April meeting with Syria’s president, John Bell confirmed that his company had recently regained access to Block 26, which he described as “an important milestone for Gulfsands and for Syria”.
He added: “This development provides a strong foundation for the recommencement of operations and investment.
“We are now back on the ground in Syria, working closely with SPC to accelerate towards a full resumption of activities.”
Bell also said that, as a result of a global drive to diversify away from “traditional choke points like the Strait of Hormuz”, Syria had the potential to become “a new world energy hub”.
In April, Saudi Arabia’s ADES Holding Company signed an implementation contract with SPC to develop several gas fields in Syria.
In a statement, SPC said the scope of the deal with ADES included executing maintenance and development works on existing wells, in addition to drilling new exploratory wells within the agreed operational areas.
It added that it expected the deal to increase gas production by 25% within the first six months and by 50% by the end of this year.
Industry insiders are also watching US-based HKN Energy, which has close ties to the Trump administration, after Qiblawy said in January that the company had expressed interest in entering the Syrian oil and gas sector.
In April, a statement from the US-Syria Business Council said an MoU with HKN was “in the pipeline”.
Over recent months, expectations have been building about a potential deal involving US-based oil and gas companies Baker Hughes, Hunt Energy and Argent LNG.
In July last year, Jonathan Bass, chief executive of Argent LNG, said that the three companies were planning to develop a masterplan for Syria’s oil, gas and power sector.
It was later reported, in February this year, that the three US-based companies were planning to form a consortium for oil and gas exploration and energy production in northeast Syria.
The consortium is expected to become involved in approximately four to five exploration blocks.
Commenting on his company’s plans in Syria, Argent LNG’s chief executive said: “We're very excited to be realising the visions of US President Donald Trump and Syrian President Ahmed Al-Sharaa, bringing the country forward from darkness to light.”
In a separate statement in April, Hunter Hunt, chief executive and chairman of Hunt Oil Company, said: “President Sharaa’s vision is bold, it is comprehensive, and it is full of execution and getting things done … We like what we see on a forward-looking basis.”
Challenges remain
While SPC’s Qiblawy has outlined ambitious targets to increase oil and gas production and international interest in the sector is growing, significant obstacles remain.
A report published by the US-Syria Business Council in April highlighted several risks facing prospective projects. Among the most significant is the threat posed by Islamic State, particularly to pipeline infrastructure crossing remote desert regions.
The report warned that securing large stretches of sparsely populated territory remains difficult, increasing the risk of attacks on critical energy infrastructure.
It also highlighted the possibility of renewed conflict in northeastern Syria, where the SDF previously controlled many of the country’s most important oil and gas assets. According to the report, the current ceasefire remains fragile and any deterioration in relations could reignite territorial disputes.
Beyond security concerns, international investors continue to face substantial financial and regulatory hurdles.
Although sanctions on Syria have been eased considerably, the country remains designated by the US as a State Sponsor of Terrorism. As a result, licences are still required for many controlled exports, including oilfield equipment, software and technology.
Restrictions also remain on support from international financial institutions. The US Export-Import Bank and the US International Development Finance Corporation continue to face limitations on their ability to support projects in Syria, constraining access to capital for large-scale developments.
These factors suggest that progress towards SPC’s production targets is likely to be slower than official projections imply.
Nevertheless, if Syria can continue to improve security conditions, strengthen political stability and maintain a supportive investment environment, the country’s oil and gas sector has the potential to deliver steady production growth over the coming years.
For international energy companies seeking opportunities outside traditional export routes and geopolitical chokepoints, Syria is increasingly emerging as a market with significant long-term potential, albeit one accompanied by substantial risk.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Rabigh 2 IPP expansion secures $2.58bn financing
5 October 2026
-
 Dubai announces $490m e-commerce hub expansion plan
5 October 2026
-
 Iraq and Turkiye discuss oil and gas deal
5 October 2026
-
-
 Contractors submit bids for Libya refinery
5 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends

Related Articles
-
Rabigh 2 IPP expansion secures $2.58bn financing
5 October 2026
Saudi Arabia’s Rabigh 2 combined-cycle gas-turbine (CCGT) independent power project (IPP) expansion has reached financial close.
In a disclosure to the Saudi Exchange, Acwa said it had secured SR9.69bn ($2.58bn) in long-term financing for the project, which has a generation capacity of 2,313.5MW.
In April, MEED reported that Acwa and Saudi Energy (formerly Saudi Electricity Company) had signed a 31-year power purchase agreement (PPA) with Saudi Arabia’s principal buyer, Saudi Power Procurement Company (SPPC), for the project.
The project involves developing a CCGT plant in the Mecca region. It is being developed by Al-Morjan Two Electricity Company, with Acwa and Saudi Energy each owning a 40% stake in the project.
The contract is valued at SR11.5bn ($3.07bn), the companies said in separate stock exchange filings at the time. The carbon-capture-ready power plant will be implemented under a build, own and operate contract.
The financing has a tenor of about 34 years and was provided by a consortium of local, regional and international lenders.
The lenders are:
- Abu Dhabi Commercial Bank
- Alinma Bank
- Boubyan Bank
- China Minsheng Banking Corporation, Hong Kong Branch
- Commercial Bank of Dubai
- HSBC Bank Middle East
- Industrial and Commercial Bank of China
- Industrial Bank, Beijing Branch
- National Bank of Greece, Cyprus
- Riyad Bank
- Saudi Awwal Bank
- Saudi National Bank
- Standard Chartered Bank, Taiwan
- Sumitomo Mitsui Trust Bank, London Branch
The project scope also includes financing and expanding a 380kV electrical substation.
According to regional project tracker MEED Projects, construction works have commenced on the project, and a joint venture of Egypt’s Elsewedy Electric and China’s Sinohydro has been working as the main contractor.
Rabigh 1 extension
In January, Saudi Energy announced a separate energy conversion agreement with SPPC for the purchase of electricity from the Rabigh 1 power plant expansion.
The contract is valued at SR5.33bn ($1.42bn).
It covers the development, financing, construction, ownership and operation of the gas-fired power plant, which will have a generation capacity of 1,179MW.
A joint venture of Elsewedy Electric and Germany’s Siemens Energy is undertaking the engineering, procurement and construction work for the project, which is expected to be completed by the end of 2026.
US/India-based Synergy Consulting is the financial advisory consultant to Saudi Energy on this project.
Acwa also recently started initial commercial operations at the Taiba 1 and Qassim 1 CCGT power plants, as reported by MEED.
The plants have a combined generation capacity of about 3.8GW and are two of four projects procured under the first round of Saudi Arabia’s gas-fired IPP programme by SPPC.
A team of Saudi Energy and Acwa won the contract to develop and operate the projects in 2023.
MEED’s October 2026 report on Saudi Arabia includes:
> COMMENT: Saudi projects hold steady
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflict
> DATABANK: Saudi data indicates project spending shiftTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20270643/main.jpg -
Dubai announces $490m e-commerce hub expansion plan
5 October 2026
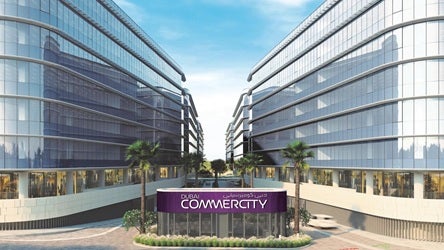
Dubai CommerCity has launched a second expansion phase valued at more than AED1.8bn ($490m), adding over 91,000 square metres (sq m) of office, retail and logistics space across the free zone’s business, social and logistics clusters.
Dubai CommerCity is a joint venture of Dubai Airport Free Zone Authority (Dafza) and Dubai government-owned Wasl Asset Management Group.
The expansion is scheduled for delivery between the first quarter of 2027 and the fourth quarter of 2028.
The developer said the move builds on sustained demand at Dubai CommerCity, where occupancy has reached nearly 96% across its office, logistics and retail assets.
Phase two will comprise a series of developments across Dubai CommerCity’s three districts: the Business Cluster, Logistics Cluster and Social Cluster.
The Business Cluster comprises 13 office buildings with a total leasable area of 108,000 sq m. The Logistics Cluster consists of 84 logistics units with a leasable area of 68,000 sq m, while the Social Cluster features art galleries, restaurants and cafes. The development will also include 4,000 parking spaces.
Dafza and Wasl Asset Management Group announced plans to develop the AED2.7bn ($735m) e-commerce free zone In 2017.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20270228/main.jpg -
Iraq and Turkiye discuss oil and gas deal
5 October 2026
Iraq and Turkiye have opened talks in Ankara on a framework agreement for oil, gas and energy cooperation, according to a statement from the Iraqi Oil Ministry.
Iraq’s Oil Minister Bassem Mohammed Khudair Al-Abadi led the Iraqi side, while the Turkish Energy and Natural Resources Minister Alparslan Bayraktar led the Turkish side.
Officials discussed a proposed roadmap to deepen work on oil and gas infrastructure, petrochemicals, and trade in oil, gas and power.
Discussions about a future long-term deal to govern the Iraq-Turkiye Pipeline (ITP) were central to the talks.
The ITP exports oil from northern Iraq to the port of Ceyhan in Turkiye.
In July, Turkiye and Iraq signed a temporary agreement to allow crude flows through the ITP for a period of 12 months.
Before the temporary agreement was signed, the previous deal governing oil exports through the pipeline was due to expire on 27 July.
Speaking last month, Ali Al-Shatri, director general of Iraq’s state organisation for marketing oil (Somo), said the temporary deal was “a prelude” to a much bigger agreement.
As well as governing pipeline exports, the new agreement is expected to cover electricity, chemicals and gas deals as well as the construction of a new oil refinery in Ceyhan.
Under current plans, the new refinery will process Iraqi crude in order to produce refined products that can be exported to Europe.
Bayraktar said: “Following the crude oil transportation agreement signed between our national company … we are clarifying our roadmap for a new, longer-term and more comprehensive agreement.
“In this regard, we plan to activate our joint working groups to rapidly finalise oil and natural gas infrastructure, exploration and production, oil trading, refining-petrochemical and electricity projects.
“In close cooperation with the new Iraqi Government, we will strongly continue to implement these concrete projects for the stability and prosperity of our shared geography.”
Bayraktar said it was important to consider extending the Kirkuk-Ceyhan pipeline to reach Basra in southern Iraq.
He also said it was important to consider expanding the capacity of the ITP to create a strong alternative to the Strait of Hormuz.
The Strait of Hormuz is a key oil export route that has been disrupted by a regional war since the US and Israel attacked Iran on 28 February.
Bayraktar also said that he wanted state-owned Turkish Petroleum Corporation (TPAO) to expand its footprint in Iraq.
He said: “We aim for our national company TPAO to play an active role not only in the Kirkuk fields but also in different fields in Iraq, to reach the target of supplying one million barrels of crude oil as stated by Iraqi Prime Minister Ali ez-Zeydi; and to transform Ceyhan into a global energy hub by increasing trade volume.”
Bayraktar said that Turkiye wanted energy to be a key part of the plan for a north-south trade corridor from the Grand Faw Port to the Turkish border.
Under current plans, the corridor will combine a new railway and highway system.
Bayraktar said that Turkiye also wants the route to include oil and gas pipelines as well as electricity transmission lines.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20268590/main.jpg -
RTCC/Ictas wins $214m King Salman airport private aviation terminal
5 October 2026
Register for MEED’s 14-day trial access
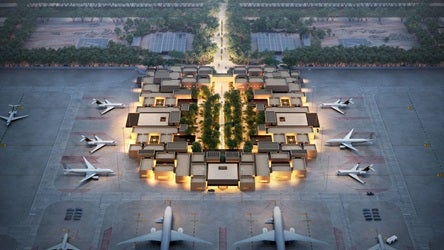
Saudi Arabia’s King Salman International Airport Development Company (KSIADC) has awarded an estimated SR800m ($214m) construction contract to build the private aviation terminal.
The contract was awarded to a joint venture of Riyadh-based Al-Rashid Trading & Contracting (RTCC) and Turkiye’s IC Ictas.
The scope includes constructing a central courtyard, grand boulevard, parking facilities, access-control checkpoints, logistics and ground-support facilities, internal road networks and landscaping.
It also includes all civil, structural, architectural, and mechanical, electrical and plumbing (MEP) works, along with testing, commissioning and handover activities.
KSIADC is making rapid progress on its overall project masterplan. In July, it reported major progress on landside and airside infrastructure works linked to its third runway and private aviation facilities, as part of the wider airport expansion programme.
Project scale
The project covers an area of about 57 square kilometres (sq km), allowing for six parallel runways, and will include the existing terminals at King Khalid International airport. It will also include 12 sq km of airport support facilities, residential and recreational facilities, retail outlets and other logistics real estate.
The airport aims to accommodate up to 100 million passengers by 2030. The cargo target is to process 2 million tonnes a year by 2030.
Saudi Arabia plans to invest significantly in its aviation sector. Riyadh’s Saudi Aviation Strategy, announced by Gaca, aims to triple Saudi Arabia’s annual passenger traffic to 330 million travellers by 2030.
It also aims to increase air cargo traffic to 4.5 million tonnes and raise the country’s total air connections to more than 250 destinations.
MEED’s October 2026 report on Saudi Arabia includes:
> COMMENT: Saudi projects hold steady
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflict
> DATABANK: Saudi data indicates project spending shiftTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20268414/main.jpeg -
Contractors submit bids for Libya refinery
5 October 2026
Bids have been submitted for the main contract for Libya’s planned South Refinery project and are currently under technical evaluation, according to industry sources.
The project, located in Ubari in southern Libya, has gained momentum over the past year, and the main contract is anticipated to be worth more than $600m.
The main contract is expected to use the engineering, procurement and construction (EPC) model.
The EPC work is expected to take 50 months, and the facility will be designed to process 30,000 barrels a day (b/d) of crude oil.
In March, US-based engineering company KBR was awarded a contract by Zallaf Exploration, Production & Refining of Oil & Gas Company to provide project management and technical services for the project.
Under the terms of the contract, KBR will provide contract management, project management and supporting technical services throughout the project’s EPC phases.
The refinery is expected to produce:
- Propane and butane for domestic and industrial uses
- Gasoline
- Kerosene
- Diesel
- Fuel oil
In March, KBR said that the project was aligned with its “long-standing commitment to advancing vital oil and gas infrastructure in Libya”.
Libya currently operates five main refineries with a combined nameplate capacity of 380,000 b/d, but actual throughput is closer to 180,000 b/d due to poor maintenance and damage from military clashes.
In addition to the South Refinery project, Libya also plans to upgrade the Zawiya refinery and carry out projects at the Serir, Brega, Tobruk and Ras Lanuf refineries.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20267178/main.jpg