Acquisition with a view to transition
24 October 2024

Adnoc International’s $16.3bn bid for German plastics group Covestro, signed on 1 October, has called fresh attention to the Middle East and North Africa (Mena) region as a source of merger and acquisition (M&A) activity.
The deal by the UAE state energy company’s overseas business arm, which is the largest Mena deal of the year, is just one of a string of acquisitions by regional energy companies seeking to diversify both sectorally and in terms of geography. And energy – notably the low-carbon variant – has emerged as a key focus for buyers.
Within the Mena region, the GCC remains the mainstay of deal flow, with its clutch of sovereign wealth funds (SWFs) and government-related entities (GREs) underpinning activity through transformative agendas that are shaped by government-led ambitions to shift away from oil and gas and embrace newer areas of the economy.
The figures underscore the Gulf bias in M&A deal flow. Ten of the Mena region’s highest-valued M&As in the first six months of 2024 were concentrated in the GCC region.
The UAE and Saudi Arabia saw a combined 152 deals worth $9.8bn and were among the top Mena bidder countries in terms of deal volume and value, according to data from EY.
The largest transaction came in February, when private equity firms including Clayton Dubilier & Rice, Stone Point Capital and Mubadala Investment announced the acquisition of Truist Insurance Holdings, the US’s fifth-largest insurance brokerage, for $12.4bn – a sign that Gulf entities have the appetite and balance sheet to lock down opportunities in North America.
Indeed, according to EY, the US remained the preferred target destination for Mena outbound investors in the first half of 2024, with 19 deals amounting to $16.6bn.
Meanwhile, Gulf-based SWFs dominate in regional M&A activity in terms of deal value. Consultancy Bain & Company says they represented 86% of deal value in 2023, either directly or through portfolio companies.
Industrial focus
Sector-specific drivers have come to the fore for some participants, and that is evident in the spread of M&A activity. Take Saudi Arabia’s Public Investment Fund (PIF), which acquired steel companies Al-Rajhi Steel and Hadeed last year, from Rajhi Invest and Saudi Basic Industries Corporation, respectively, creating a national champion in a domestic steel sector that has consolidated.
Similarly, Adnoc’s Covestro acquisition confirms the prominent role that national oil companies continue to play as they morph into energy companies with more diverse product slates, and in turn are required to grow inorganically at times.
The Covestro deal represents a similar move to the PIF’s steel sector play last year. The German company would become a key plank in Adnoc’s ambition to create a speciality chemicals business. In a similar way, Borealis, in which Adnoc is a minority stakeholder, acquired Austrian chemicals group Integra Plastics in a deal announced in April 2024.
“The acquisitions from Adnoc are in line with a vision that they set out [in 2017], when the company restructured and broadened its scope to be a global business, looking actively for global opportunities to grow and diversify,” says Alice Gower, a partner at Azure Strategy.
She says that the interest in the European downstream sector is “a really smart move, because it not only ensures a market for their products, but it replaces Russian supplies and creates a dependency between Europe and, in this case, the Saudis or Emiratis”.
UAE companies’ interest in buying into European industrial firms has been evident this year. February saw Adnoc complete its long-running effort to acquire a 24.9% stake in Austrian petrochemicals firm OMV, and in May, state held Emirates Global Aluminium completed the acquisition of German aluminium recycling firm Leichtmetall Aluminium Giesserei Hannover.
Another geographic theme has seen GCC firms target Asia and Africa – the latter increasingly a focus in terms of its resource opportunity, as well as its capacity to provide a growing consumer market with an emergent middle class.
Last year, Asia figured in some of the biggest deals involving Mena companies, such as the $2bn investment by the UAE’s Mubadala in Chinese fashion retail firm Shein, and Qatar Investment Authority’s purchase of a $1bn stake in India’s Reliance Retail Ventures.
Resources – particularly transition minerals – look set to remain a prominent theme for Mena dealmakers. In Africa, the UAE’s International Resource Holding, an affiliate of Sheikh Tahnoon Bin Zayed-headed International Holding Company, completed its acquisition of Zambia’s Mopani Copper Mine in March 2023, paying $1.1bn for a 51% stake. The UAE firm has moved into critical metals and sees this entity as playing a key role in developing the metal and mining supply chain.
Energy transition
The energy transition will continue to push Gulf acquirers’ M&A agendas.
Abu Dhabi’s Masdar, eyeing a target 100GW of clean energy by 2030, has become an active M&A player. In June, it acquired a 67% stake in Greek company Terna Energy for $2.9bn.
Deal flow at Masdar has been brisk, with a deal struck in September to acquire renewable energy provider Saeta Yield from US investment firm Brookfield for $1.4bn, handing it significant power assets in Spain and Portugal and a 1.6GW development pipeline.
Masdar has also been growing its US foothold, closing a deal in October for a 50% stake in US renewables company Terra-Gen, which boasts a wind, solar and battery storage portfolio of 3.8GW.
Meanwhile, with the PIF and Mubadala both committed to net-zero targets by 2050, in addition to working to decarbonise their existing portfolios, the funds are investing in green assets and in technologies that support decarbonisation, notes Bain & Company.
Azure Strategy’s Gower cautions against reading too much into the professed diversification agenda, however.
“Everybody talks about diversification, but if you actually look at what they’re investing in, it’s not that far from the fossil fuel industry,” she says.
“There is a vertical integration logic: you’re upstream and you want to then become more involved in midstream and downstream – that makes sense. But the businesses that they are buying are pretty low-margin, so there has to
be a different reason behind this approach.”
Instead, defensive motivations are in play. “It is about capturing shares in assets across different markets in order to spread risk, and then diversifying revenue streams away from direct exports, given their geographic location,” she says.
“Look at what is going on in the region at the moment, and the increase in shipping costs, the instability and insecurity risk.”
Banking mergers
M&A in the Mena banking sector has slowed down in the past five years, following a spate of deals that mainly reflected the reordering of state holdings in large Gulf banks.
In March 2024, the Egyptian subsidiary of Bahrain’s Bank ABC completed its merger with the Egyptian subsidiary of Lebanon’s Blom Bank, tripling Bank ABC’s market share in Egypt.
Market speculation is now centring on consolidation within Kuwait’s banking sector.
The proposed merger of Boubyan Bank and Gulf Bank – Kuwait’s third- and fifth-largest lenders – would create an Islamic lender with assets of about $53bn.
“GCC banks in general have been keeping their options open because these are small, concentrated economies and markets, and therefore international expansion will help diversify business models and improve profitability,” says Redmond Ramsdale, senior director for banks at Fitch Ratings.
M&A moves have taken Gulf banks into the wider region.
“External growth is part of some GCC banks’ strategy to diversify business models and improve profitability,” says Ramsdale. “By deploying capital into high-growth markets, they may be able to compensate for weaker growth in their home markets.”
In the wider Mena region, M&A activity in 2025 will be driven by the big regional SWFs and GREs. The need to decarbonise their portfolios will shape inorganic growth strategies as they look to buy lower-carbon assets ‘off the shelf’ to meet net-zero and emission-reduction targets.
With sizeable acquisition budgets at their disposal, these players do not lack the financial firepower to target assets that will help them meet their goals.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Saudi Arabia raises electricity tariffs
26 October 2026
-
 Dubai Municipality confirms AED3bn Tasreef drainage awards
26 October 2026
-
 Nakheel awards $259m Dubai Islands buildings contract
26 October 2026
-
 Expo 2030 Riyadh tenders Culture of Wisdom Pavilion
26 October 2026
-
 Morocco plans second high-speed rail phase to Agadir
26 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Saudi Arabia raises electricity tariffs
26 October 2026
Saudi Energy, formerly Saudi Electricity Company, has announced revised electricity tariffs, which will take effect on 1 January 2027.
The revised tariff schedule, published on the company’s official website, covers residential, commercial, industrial, agricultural, charitable and government customers.
The largest percentage increase in consumption rates is 16.7%, for residential customers using up to 6,000 kilowatt-hours (kWh) a month. Residential customers will pay 21 halalas/kWh for monthly consumption of up to 6,000kWh, up from 18 halalas. For consumption above 6,000kWh, the rate will rise from 30 to 33 halalas/kWh, a 10% increase.
The industrial tariff will increase by 15%, from 20 to 23 halalas/kWh. Commercial customers, private healthcare facilities and private educational facilities will pay 25 halalas/kWh, up from 22 halalas, for consumption up to 6,000kWh a month, and 35 halalas/kWh above that level, up from 32 halalas.
Tariffs for charities and government customers will also increase. In addition to consumption-based charges, customers will pay a fixed monthly fee based on the capacity of their electricity meter. This replaces the previous separate charge for meter reading, maintenance and billing, with VAT applied to the revised tariffs.
Electricity investment
The new tariffs coincide with changes to water consumption tariffs announced by the National Water Company, also effective from 1 January 2027.
King Salman Bin Abdulaziz Al-Saud directed support measures following a proposal presented by Crown Prince and Prime Minister Mohammed Bin Salman Bin Abdulaziz Al-Saud.
This includes raising the minimum wage required for Saudi nationals to count as full employees towards private sector localisation quotas under the Nitaqat programme.
The tariff changes come as Saudi Arabia plans substantial investment in its electricity infrastructure. In September 2025, Saudi Energy announced plans to invest SR220bn ($58.7bn) in power infrastructure projects between 2025 and 2030.
A June 2025 report by Fitch Ratings forecast negative free cash flow of about SR16bn a year over the period and rising leverage, reflecting the financial demands of the programme.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20924301/main.jpg -
Dubai Municipality confirms AED3bn Tasreef drainage awards
26 October 2026
Dubai Municipality has confirmed it has awarded four contracts worth AED3bn ($817m) to expand the emirate’s stormwater drainage network by about 100 square kilometres under phase three of the Tasreef programme.
The projects will cover Jumeirah, Umm Suqeim, Al-Quoz, Al-Barsha, Al-Wasl and Al-Marmoom. The works include constructing and extending main stormwater drainage lines with diameters of up to three metres.
The four packages are part of Dubai’s AED30bn Tasreef programme, which aims to increase the emirate’s stormwater drainage capacity by 700% and reduce costs associated with pumping stations, network operations and maintenance by 20%.
The contracts have been awarded to China State Construction Engineering Corporation (CSCEC) and three local firms: Arifco Group, Nael Construction & Contracting (NCC) and Detech Contracting. Dubai Municipality did not state which projects the awards relate to.
According to sources, the contract awards include packages TF-15-C1, TF-15-C2 and TF-13-C1.
The first package, TF-15-C1, involves the construction of 21 kilometres of main and secondary drainage lines along Al-Wasl Road and in surrounding areas. It will cover Za’abeel 2, Al-Wasl, Jumeirah 1 and 2, Al-Bada’a, Al-Satwa and Dubai World Trade Centre. The estimated $100m contract was awarded to Detech in July, as exclusively reported by MEED.
The second package, TF-15-C2, covers the corridor between Sheikh Zayed Road and Al-Khail Road. It includes about 14km of main drainage lines serving Al-Quoz Industrial Areas 1, 3 and 4, and Al-Barsha 1. In July, MEED reported that CSCEC had won the engineering, procurement and construction contract for this project.
The third package, TF-13-C1, covers Al-Marmoom, where 23km of drainage infrastructure will be developed. According to a source, Arifco has been awarded this contract.
The final package covers Jumeirah and Umm Suqeim, where about 42km of main drainage lines will serve Umm Suqeim 1, 2 and 3; Umm Al-Sheif; Jumeirah 3; Al-Safa 1 and 2; and Al-Manara.
In May, MEED reported that NCC had been awarded a contract to build a sewage and stormwater drainage system, DS-204. However, it is unconfirmed whether this relates to the same project.
Earlier, in February, the municipality confirmed it had awarded contracts for five new projects under phase two of the programme to expand and strengthen Dubai’s stormwater drainage network.
These included two contracts awarded to Detech and one to CSCEC for stormwater drainage infrastructure. In addition, two consultancy contracts were awarded for the study and design of drainage systems in selected areas across the emirate.
Cumulatively valued at AED2.5bn, the new projects will serve 30 vital areas, spanning approximately 430 million square metres and supporting an estimated population of three million residents by 2040.
Previously, in April 2025, an earlier package of awards was announced under phase one of the Tasreef programme. The overall masterplan aims to expand Dubai’s rainwater drainage capacity by 700% by 2033.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20923924/main4827.jpg -
Nakheel awards $259m Dubai Islands buildings contract
26 October 2026
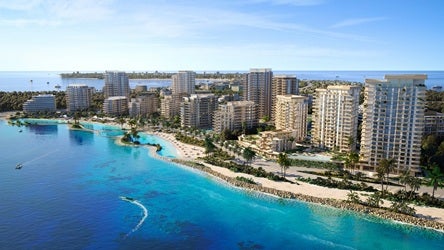
Dubai-based master developer Nakheel, part of Dubai Holding Real Estate, has awarded local firm Parkway International Contracting a construction contract valued at about AED950m ($259m) for phases two and four of Bay Grove Residences on Dubai Islands.
The package covers 617 residential units across eight buildings, ranging from one to four bedrooms, together with basement structures, infrastructure and community amenities including swimming pools, sports courts and fitness centres.
Phase two comprises 360 homes across four buildings, with main construction scheduled for completion in late 2028.
Phase four includes 257 homes across four buildings, with completion targeted for the second quarter of 2029.
The award follows an earlier contract valued at about AED800m ($218m) awarded to local contractor Metac General Contracting Company for phases one and three, covering 537 homes across seven buildings.
Together, the two contracts total more than AED1.75bn ($476m) and account for all 1,154 planned homes across the 15 buildings of Bay Grove Residences.
Project activity on Dubai Islands has gathered pace in recent months. Earlier this month, Nakheel awarded local firm Mar Marine & Building Contracting a contract for marine and coastal works on Island B. The scope includes constructing breakwaters, removing existing rock revetments and creating a new 320-metre beach near the Bay Villas development, as well as remedial and refurbishment works along approximately 3 kilometres of the island’s western shoreline.
In August 2025, Nakheel awarded Fibrex Contracting a AED2.6bn ($708m) construction contract for the Bay Villas residential project. That followed a AED527m ($143m) contract awarded to Al-Nasr Contracting Company in April 2026 for primary infrastructure and utilities on Island B.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20923389/main.jpg -
Expo 2030 Riyadh tenders Culture of Wisdom Pavilion
26 October 2026
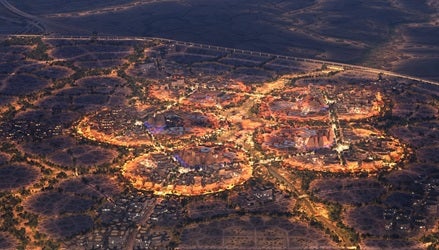
Saudi Arabia's Expo 2030 Riyadh Company (ERC) has tendered the design-and-build main contract for the construction of the Culture of Wisdom Pavilion in the expo’s Humanity District.
The tender was issued on 1 October, with a bid submission deadline of 6 January 2027.
The scope covers the pavilion’s design and the delivery of the building, visitor experience, landscape and public-realm works, in addition to testing, commissioning and operational handover.
The pavilion will be built on a plot of at least 12,293 square metres and will include a one-level basement, ground- and first-floor public areas, three interconnected courtyards, exhibition spaces on three levels, and an auditorium.
Other facilities will include visitor engagement areas, food and beverage outlets, retail space, VIP areas, offices, back-of-house and technical spaces, as well as vertical circulation and building services.
The facility is designed to accommodate at least 20,000 visitors a day during peak periods, with an anticipated average daily footfall of about 15,000 visitors. The project has a target of Leed Gold certification.
The successful contractor will complete the design, including specialist contractor design portions, and will coordinate the works with the lead design consultant. The scope also includes substructure and early works, including earthworks, excavation, soil improvement, raft foundations, basement reinforced-concrete walls, waterproofing and backfilling.
The main works tender is based on Royal Institute of British Architects' Stage 3 design at 60%, with the 100% Stage 3 design to be issued by addendum.
The main contractor will take over early construction, foundation works and the lead designer’s role. Visitor experience works will be confirmed at a later stage.
The contract also covers the building envelope; internal fit-out; mechanical, electrical and plumbing systems; information and communications technology; fire and life safety systems; security; specialist lighting; landscaping; utilities; and digital and immersive visitor-experience installations.
ERC has also tendered the design-and-build main contract for the Adaptation and Innovation Pavilion in the exhibition’s Technology District, as MEED reported last week.
Expo 2030 Riyadh will run from October 2030 to March 2031 with the theme Foresight for Tomorrow, with host authorities projecting approximately 42 million visits.
The masterplan covers 6 square kilometres, making it one of the largest sites ever designated for a World Expo event.
Situated north of the Saudi capital, the site is located near the future King Salman International airport and will provide direct access to Riyadh landmarks.
The Public Investment Fund, Saudi Arabia’s sovereign wealth vehicle, launched ERC – a wholly owned subsidiary – in June 2025 to build and operate facilities for Expo 2030.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20921052/main.jpg -
Morocco plans second high-speed rail phase to Agadir
26 October 2026
Morocco has outlined a second rail investment cycle for 2030-35, which includes beginning construction of a high-speed rail extension from Marrakech to Agadir and connecting Essaouira to the national rail network.
The pipeline forms part of the government’s 2026-31 programme, presented to parliament last week.
The Marrakech-Agadir link is estimated to cost close to MD55bn ($5.5bn) and will cover a 240-kilometre (km) route through the High Atlas Mountains via Chichaoua. Civil engineering structures, including tunnels and viaducts, are expected to account for nearly 70% of the alignment.
In September, the government issued a decree declaring the Marrakech-Agadir and Chichaoua-Essaouira rail corridors to be of public utility, paving the way for land acquisition and expropriation procedures.
Under the long-term masterplan Plan Rail Maroc 2040, Essaouira is expected to connect to the network via a separate line branching off at Chichaoua, designed for operating speeds of up to 200km an hour. The mainline to Agadir is designed for speeds of up to 320km/h.
The 2030-35 cycle also includes rehabilitating the Casablanca-Khouribga-Oued Zem line; constructing a new line between Oued Zem and Beni Mellal via Bejaad, with a branch to Fquih Ben Salah; doubling and upgrading the 140km Benguerir-Safi line; expanding capacity on the Fez-Oujda corridor; and building new-generation passenger stations.
The plans follow Morocco’s ongoing MD134bn ($13.4bn) 2024-30 rail investment programme, which focuses on completing the Kenitra-Marrakech high-speed line ahead of the 2030 Fifa World Cup.
The programme also includes developing regional express network services across five regions, electrifying the Fez-Oujda line and completing a freight rail link to the Nador West Med port.
Work on the Kenitra-Marrakech line had reached about 30% by May 2026, with commercial services targeted to begin in September 2029.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20920349/main.jpg