A case study in procurement
18 March 2025

Register for MEED’s 14-day trial access
While it may not be in the headlines as much as some of its more eye-catching official gigaproject counterparts, Roshn has already delivered thousands of residential units in Saudi Arabia as it seeks to fill the upscale and community living housing map.
Launched in 2020, the Roshn gigaproject is a component of the Vision 2030 plan to achieve 70% home ownership among Saudi nationals by 2030. Alongside the National Housing Company, it is the delivery vehicle for government-backed housing construction as Riyadh seeks to meet the shortfall in available stock.
Its first project was its Sedra community in the north of the capital. Currently on its fourth of eight delivery phases, the multibillion-dollar masterplanned development will comprise 30,000 homes over 20 million square metres (sq m) when completed.
Roshn’s second Riyadh community under construction is Warefa in the northeast of the capital. More compact than Sedra, it will have 2,300 units over an area of 1.4 square kilometres, with 150,000 sq m of green open space.
Three years after the launch of its first projects, Roshn announced Marafy, its first scheme in Jeddah and its largest mixed-use development to date. Designed to accommodate more than 130,000 residents, Marafy will be built around an 11-kilometre, 100-metre-wide canal, linking with Obhur Creek in the northern outskirts of the kingdom’s second city.
Already breaking ground, Marafy’s first core component is the Alarous residential community, which will offer 18,000 units over a 4 million sq m land area.
Elsewhere in the kingdom, Roshn’s other planned community projects include Almanar in Mecca, Alfulwa in Hofuf and Aldanah in Dhahran. Between them, these schemes total more than 50,000 units. It is expected that thousands of additional homes in other parts of the kingdom will be announced by the developer in the next two years.
Delivering such projects at many different locations is a complex exercise, requiring procurement strategies that not only encompass on-time and on-budget completion, but also ensure that local content is maximised while at the same time maintaining stringent quality standards.
Tasked with handling Roshn’s overall procurement strategy is Iain McBride, the gigaproject developer’s head of commercial.
It is expected that thousands of additional homes in other parts of the kingdom will be announced by the developer in the next two years
Like other gigaprojects in the kingdom, McBride and his procurement team have had to deal with the twin challenges of soaring cost inflation and maximising local content in materials and equipment.
The five official gigaprojects – Diriyah, Neom, the Red Sea Project, Qiddiya and Roshn – are free to employ their own procurement rules and processes, and each has taken a different approach to address its specific requirements. For example, Red Sea Global uses a construction management approach wherein it contracts directly with companies and suppliers that would normally work as subcontractors under the main contractors.
Similarly, Diriyah Company employs a strategy of bundling several smaller contract packages into a single large contract, as a means of consolidating work to ensure lower costs and maintain contractor interest.
Hear directly from the gigaproject owners at the biggest construction event – The Saudi Gigaprojects 2025 Summit, happening in Riyadh from 12-14 May 2025. Click here to know more
Demand signalling
The nature of Roshn’s mainly residential projects means that from the outset it knew it would need thousands of items with similar specifications, such as doors; glass panes; sanitaryware; and heating, ventilation and air-conditioning systems.
To secure this supply chain, early on the company identified local manufacturers of these products and reached long-term agreements with them for the delivery of required materials.
“Our first step was signing a lot of long-term partnership agreements through master purchase agreements where we could leverage preferential rates,” says McBride, speaking to MEED in late January.
“Ultimately, it's all about balance and risk – derisking the opportunities for the supply chain by telling them how many doors, for example, we're going to need each quarter for the next five to 10 years. It gives confidence to the manufacturers that they can start committing to.”
Roshn was the first of the gigaprojects to publicly signal its demand requirements. In 2021, it announced that it would require at least 5 million doors, 3.5 million air-conditioning units, 4.3 million windows, 80 million sq m of tiles and 6.5 million pieces of sanitaryware. These numbers have since changed, but they are indicative of the scale of the supply chain challenge.
Armed with the knowledge that Roshn is both supported by its parent, sovereign wealth vehicle the Public Investment Fund (PIF), and that it is a central element of Saudi Vision 2030, local manufacturers had the confidence to commit to investing in production capacity to meet its needs.
Significantly, most of these deals have been with manufacturers within the kingdom, thereby maximising the local content aspects. Just as importantly, Roshn has not had to make any fixed orders – so-called ‘take-or-pay agreements’ – with suppliers, such is the latter’s faith in the developer.
“For the time being, we’ve not had to make any firm commitments,” says McBride. “We did look at it at one point, but our approach has always been to keep it as simple as possible by listening to the supply chain and seeing what they need. When we were speaking to them, it wasn’t their number one driver; they weren’t screaming at us saying, ‘We need you to give us a firm order’.
“Now, many people think a take-or-pay agreement is essential – where you commit to ordering [a certain quantity] of materials over a period of months or years and, if you don’t, you have to pay a penalty, thereby adding risk and complexity for the developer.
“What we were able to agree instead was that we'll be open and transparent with [the suppliers about] what we need. We said to ourselves, ‘Let's get a good price that works, whether we buy directly from the supplier or whether we include that supplier within our tenders with major contractors’. And we’ve seen great success with that approach, with multiple companies.”
The localisation push is supported by the design process. Wherever possible, the designs for Roshn’s projects incorporate and specify equipment and materials that are known to be manufactured locally.
There have been instances where specific, specialised materials and products are not produced in the kingdom, or not in the quantities required, such as marble and certain architectural facades.
Where this is the case, Roshn is keen to explore how it can help to build in-kingdom capacity. The developer has initiatives through which it looks to co-invest in production facilities that come with high capital requirements.
As McBride explains, Roshn is only one part of the huge and rapidly accelerating Saudi projects market ecosystem, and in helping to increase capacity, it is also putting itself in a position to help other developers with their supply chain needs.
A case in point is Roshn’s contract with China Harbour Engineering Company, which was awarded the $2bn deal in 2023 to build villas at Sedra and Warefa.
Part of the contract requires the Chinese contractor to set up a precast manufacturing facility on site at Sedra. In this way, Roshn could not only ringfence the plant for its own needs, but when it no longer requires the output, other projects could benefit from its production capacity.
“The factory has a 15-year lifespan, so any additional capacity will be there for another 10 years after our requirements are met,” says McBride. “In Riyadh, we have Expo 2030, the new airport, the stadiums and many other projects that could draw on its output.”
There are some situations where even this is not enough, particularly when it comes to contracting expertise. One such case is Roshn’s mandate to develop a 45,000-seat stadium in the southwest of Riyadh as part of the kingdom’s Fifa World Cup 2034 plans. On such a complex, highly engineered project, Roshn has insisted that an international contractor teams up with a local company as a condition of tender participation.
This insistence is based on Roshn’s experience overseeing the construction of a football stadium in Dammam alongside co-developer, Saudi Aramco. The project, which is being built by a joint venture of Belgium’s Besix and the local Albawani, is proceeding at a rapid pace and progress has been relatively trouble-free.
McBride says: “If we have to go abroad, let’s go abroad. But make sure it’s done in a smart way and that we’re not just throwing money out of the kingdom.”
Early contractor involvement
On the issue of contracting, it is well known that the massive amount of work in Saudi Arabia is stretching contractors to the limit, pushing up prices and straining labour, engineering and equipment resources.
Roshn’s approach to this challenge has been to engage with contractors at the earliest possible stage of project planning, specifically at the design phase, through an early contractor involvement (ECI) procurement framework. In this way, the company is able to obtain contractor feedback during concept and design and subsequently lower construction risk by improving a project’s constructability.
“It's about signposting the demand by getting the contractor in early, where you can really influence the design, the buildability and the value-engineering opportunities,” says McBride. “Ideally, we bring them in as quickly as possible during the concept stages, when there's very little cost to changing things.
“The worst thing for a contractor is receiving a [request for proposal] cold. They have to … come back in four weeks and then be squeezed for a best price, whereas with ECI they can add value. They really appreciate that.”
When asked to quantify the cost benefits of such an approach, McBride is forthright: “It’s not even a case of doing the maths,” he says. “We have a great example of where it’s worked on our Aldanah project in Dammam. We selected the contract very early on and locked in the floor plans and facades that we wanted. We were then able to deliver a street of 10 show homes [that took] not much more than four months to design and construct.
“The saving, in terms of time, was massive; we probably halved the duration. I probably wouldn’t be exaggerating if I said it saved about a year.
“There are two ways you can follow your engineer,” he continues. “One: you can follow them early and make sure that the way you're looking to save costs is in areas that are not impacting the customer.
“Or two: the worst thing you can do is get to the end and you have a full structural design that could be over-engineered and you’re spending money in the wrong places.
“We don’t want to get to a point where we're trying to value-engineer by cutting things out that are important to customers,” McBride explains. “And that's what you avoid by having this early contractor involvement.”
The company is able to obtain contractor feedback during concept and design and subsequently lower construction risk by improving a project’s constructability
Unlike the other gigaprojects, Roshn has been in the favourable position of being able to raise some revenue by marketing and selling its properties off plan. While this has been beneficial from a development perspective, it has also meant that the developer must get its pricing and housing specifications right if it is to develop homes within an already-defined budget.
Having a contracting partner on board during the design and specification stage facilitates the conversation between the property sales team, which is informing on market requirements, and the builder, who can deliver within the designed cost and quality parameters.
This is in contrast to many real estate developments for which sales are completed before the construction estimates come in, potentially undermining the business case.
The step beyond ECI is for contractors and suppliers to partner with Roshn to inject equity into the projects by acting as co-developers. McBride points to several planned mid-rise towers at Marafy that could be a starting point for this.
Contractors financing projects or bringing in replacement equity has long been an ambition in the region, but builders have been reluctant to adopt this approach. Nonetheless, McBride is confident that it could happen, indicating that there has already been strong interest from the contracting community.
Cost inflation
Another major talking point in Saudi construction is the escalating costs caused by high inflation, logistical challenges and a tightening of contracting and skilled labour capacity.
In many cases, this has required the rescoping of projects, revisions to timelines and even the scrapping of elements. Neom is arguably the best example of this, as it has reprioritised The Line and is facing an estimated cost of $50bn for building each of its first three modules – far in excess of original estimates.
Roshn’s approach to the challenge is to be as open and transparent as possible with the contractor and supplier community. This has involved outlining a long-term pipeline of work that gives the supply chain confidence about its requirements, enabling them to fix in long-term pricing structures. In return, the developer expects prices to come in competitively.
“It’s no secret within the supply chain market that Roshn has quite aggressive price points,” says McBride, a former chartered surveyor who, prior to joining Roshn, worked as a quantity surveyor and cost-management director at consultants Faithful+Gould (now AtkinsRealis) and Rider Levett Bucknall.
“What we're trying to do is engage early, build trust with the contractors, let them see we’re a good client that's going to pay and have honest and fair contracting terms, and work together to try and solve issues post-contract.
“We don't mind if there's inflationary pressures because of commodity prices increasing. But what we're trying to avoid is inflationary prices through just the demand increasing.
“An innovative way that we've implemented this even on our lump-sum contracts – our traditional Redbook or older contracts – is that we have preferred supplier agreement clauses in them,” he adds.
“So, rather than a traditional bill of quantities (BoQ) that has a rate, a quantity, a total, within our rate section we have the material supply rate, the installation rate and then everything else, such as overhead profit. We protect the installation rate, so it's not a percentage of the material; it's a fixed SR100 a square metre to install, for example.
“One of the big frustrations for contractors is [that the supplier has] a material we think they're going to deliver. It's maybe not available, so they submit alternative materials. The client keeps rejecting it – it's not what they want – and it becomes a delay; it's painful.”
McBride gives the example of a pre-approved bathroom sink. Thanks to Roshn’s relationships with key long-term suppliers, the company is able to negotiate better rates for sanitaryware than would be available to a contractor on an ad hoc basis. If the developer’s rates for sinks are better than the BoQ, it splits the savings 50:50 with the contractor.
“The contractors are winning out of that exercise, we're winning out of it and, ultimately, the customers are winning out of it as well, because we’re passing on those savings,” says McBride.
Flexibility
The benefits to contractors and suppliers extend to payment terms. In today’s sellers’ market, vendors are effectively able to pick and choose the clients they want to work for. As a result, clients – including the gigaprojects – have had to introduce more flexible payment terms and develop market reputations for paying on time.
Roshn may lead the pack on this, with an average payment time from invoice to payment of just 13 days in 2024. A decade ago, this would have been unheard of, but it is now increasingly becoming the norm among the gigaprojects.
In addition, like its PIF peers, Roshn has done away with tender fees and tender bonds, viewing them as outdated means of enforcing vendor participation, especially given the tight liquidity and cashflow situation in the projects market in Saudi Arabia.
Will such flexibility ever extend to performance bonds? McBride is sceptical, pointing to the fact that Roshn’s strong relationship with local banks allows to it facilitate credit agreements between contractors and their lenders. Being a gigaproject developer supported by the PIF – and by tacit extension the state – also helps provide the underlining ease of mind for financers.
Nonetheless, Roshn also takes a proactive approach with advanced payments, enabling up to 20% of the total contract value at the initial stage of the project.
“We've been quite clever in how we do this,” says McBride. “We don't go and release 20% straight away. We’ll do 10% and then, when we’ve evidence that you’ve expended that 10% on mobilisation and site establishment, we’ll release the second 10% tranche.”
Subcontractors
One of the chief sticking points in the kingdom’s projects ecosystem in the past decade has been the capacity and capability of its subcontractors.
The payments crisis in 2017-20 forced many main and general contractors to reduce their permanent labour forces, plant and general resources. Wary of a repeat, most have retained their leaner structure and so have turned increasingly to subcontractors for their manpower and delivery requirements.
In theory, this makes sense, but in practice subcontractors in Saudi Arabia are themselves often overstretched in terms of both delivery capacity and labour availability. In turn, they frequently use their own subcontractors, which then also outsource, to the point that specific elements of a project may be completed by companies very far down the supply chain – with the quality issues that this implies.
Roshn’s solution is to ensure any subcontractor on site goes through a vetting process encompassing quality and financial checks, thereby ensuring it has full visibility on every company on site.
Increasingly, Roshn is dealing with suppliers directly, under supply-install contracts. This can create interfacing issues with the main contractors, however, which are ultimately responsible for the project’s delivery.
“We have to be quite careful on that,” McBride says. “We have to go through all the checks and balances during the prequalification process because if we are going to give a subcontractor to a contractor that we're saying is pre-vetted by Roshn, we could be opening the door to lots of claims from the main contractor against us. So, vetting for us is absolutely crucial.”
Roshn is also working with smaller suppliers and subcontractors to help them evolve and grow, so that they can start taking on smaller main contractor roles themselves.
“Not every construction package we award is in the billions of riyals,” says McBride. “Our thinking is to let the big tier-one contractors focus on the multibillion-riyal deals while we encourage the smaller ones to grow as part of our supplier development programme.”
To achieve this, the developer holds events and bootcamps with its vendors to discuss best practices on subjects including health and safety, variation procedures and how to submit good tender returns.
Roshn is also working with smaller suppliers and subcontractors to help them evolve and grow
Building information modelling
Vendor education also extends to the use of building information modelling (BIM) and other construction technologies.
BIM is mandatory on Roshn’s projects, as it is on the other gigaprojects. While use of the technology is standard across almost all main contractors in the region, its take-up among smaller companies in the supply chain has been slower, with firms pointing to the cost of its adoption and integration as a barrier, as well as the fact that some clients, particularly government ones, view it as providing limited benefit.
Roshn’s task in this area is made difficult because its projects are less complex from an engineering and construction perspective.
“We’re building villas; it’s completely different to building stadiums or airports,” McBride says. “Can these contractors build from [two-dimensional] drawings? Yes, of course they can. You're not going to convince a smaller contractor that all of these benefits will make it easier to build because they know how to build. They've been doing it for decades.
“But the savings are in making it easier to procure, savings in the repeatability, and in the change control. If you upskill yourself on a Roshn project, you are building your capability, which you can then [demonstrate] to other clients as proof you can go after bigger and more complex projects. It's something that the whole industry has to get behind.”
Indeed, there is much to learn from Roshn’s approach to delivering its infrastructure and building plans. While the comparatively straightforward nature of its projects means that its procurement strategies may not be suited to those gigaprojects with more iconic designs, for many other developers it is a case study in efficient processes that have proven effective in delivering work on time and to budget.
This is just as well given that Roshn is set to embark on the next stage of its journey, with its focus on the more complex Marafy city development in Jeddah and Roshn Stadium in Riyadh. However, the evidence suggests that from a procurement strategy perspective, it is well-positioned to also make this a success.


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 WEBINAR: End-of-Year Mena Market Review
13 November 2026
-
 Syntys breaks ground on 20MW Qatar data centre
13 November 2026
-
 Jereh wins $392m Bu Hasa oil field facilities project
13 November 2026
-
 PDO awards contract for Al-Ghubar oil field project
12 November 2026
-
 Laing O’Rourke joins the international exit list
12 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
WEBINAR: End-of-Year Mena Market Review
13 November 2026
Webinar: The big questions shaping the Gulf market. You decide what gets debated.
Tuesday 24 November 2026 | 11:00 AM GST | Register now
What makes this session particularly interesting is that the audience gets to decide the agenda. Registrants can vote for the topics they’d like Ed and Colin to debate, with the most popular questions forming the final shortlist for the live session.
Topics in the ballot:
- Is the Gulf trying to build too much, too quickly?
- Saudi Arabia or the UAE: where would you place your next big bet?
- Are gigaprojects the best use of public money?
- Who is really responsible when projects go wrong?
- Should the lowest-price tender become a thing of the past?
- Can private capital take over from the government in financing infrastructure and diversification?
- Is the Gulf’s AI and data centre boom a smart bet or the next overbuilding risk?
- Should the Gulf double down on hydrocarbons to fund diversification?
- Is localisation strengthening the economy or making delivery harder?
- Are Gulf countries building complementary economies or competing for the same customers?
The session will also feature live audience polling and Q&A, giving attendees an opportunity to share their views.
Hosted by:
Edward James, head of content and analysis at MEED
 A well-known and respected thought leader in Mena affairs, Edward James has been with MEED for more than 19 years, working as a researcher, consultant and content director. Today, he heads up all content and research produced by the MEED group. His specific areas of expertise are construction, hydrocarbons, power and water, and the petrochemicals market. He is considered one of the world’s foremost experts on the Mena projects market. He is a regular guest commentator on Middle East issues for news channels such as the BBC, CNN and ABC News and is a regular speaker at events in the region.
Colin Foreman, editor of MEED
 Colin Foreman is editor and a specialist construction journalist for news and analysis on MEED.com and the MEED Business Review magazine. He has been reporting on the region since 2003, specialising in the construction sector and its impact on the broader economy. He has reported exclusively on a wide range of projects across the region including Dubai Metro, the Burj Khalifa, Jeddah Airport, Doha Metro, Hamad International airport and Yas Island. Before joining MEED, Colin reported on the construction sector in Hong Kong.https://image.digitalinsightresearch.in/uploads/NewsArticle/21380319/main.gif
-
Syntys breaks ground on 20MW Qatar data centre
13 November 2026
Register for MEED’s 14-day trial access
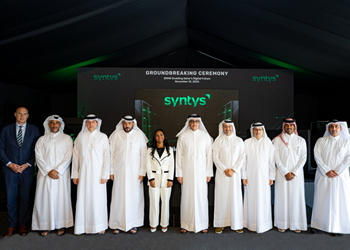
Qatari data centre developer Syntys has broken ground on a 20MW facility to support hyperscale, cloud, artificial intelligence (AI) and advanced computing deployments.
The groundbreaking ceremony took place on 12 November. It was attended by Qatar’s Communications & Information Technology Minister, Mohammed bin Ali bin Mohammed Al-Mannai, along with representatives from Ooredoo Group, Microsoft, Google, Kahramaa, the National Cyber Security Agency, Qatar Free Zones Authority and local banks.
Syntys said the facility is being developed on an existing company campus, where power, fibre connectivity and an operational team are already in place. The company has yet to disclose the project value or planned completion date.
The facility is designed to meet Tier 3 requirements and accommodate a range of rack densities, including higher-density configurations for graphics processing unit (GPU)-based AI and high-performance computing workloads.
It will operate as a carrier-neutral facility, allowing customers to select connectivity providers and establish network resilience in line with their own technical and operational requirements.
The project forms part of Syntys’ strategy to expand its Qatar platform through acquisitions and new development. Earlier this year, the company acquired QData QFZ, adding two operational, Tier 3-compliant, carrier-neutral facilities to its portfolio.
Syntys now owns and operates four campuses in Qatar, allowing customers to establish primary and disaster-recovery environments at separate in-country locations.
The company also designs and operates the facilities supporting Ooredoo’s sovereign AI cloud, which uses Nvidia Hopper GPUs.
The development comes as Qatar implements its Digital Agenda 2030, which identifies digital infrastructure as one of six strategic pillars and targets about QR40bn ($11bn) in economic impact by 2030.
The data centre is expected to support the growth of in-country digital services and enable sensitive workloads to remain within Qatar’s national borders.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21378257/main1028.png -
Jereh wins $392m Bu Hasa oil field facilities project
13 November 2026
Register for MEED’s 14-day trial access
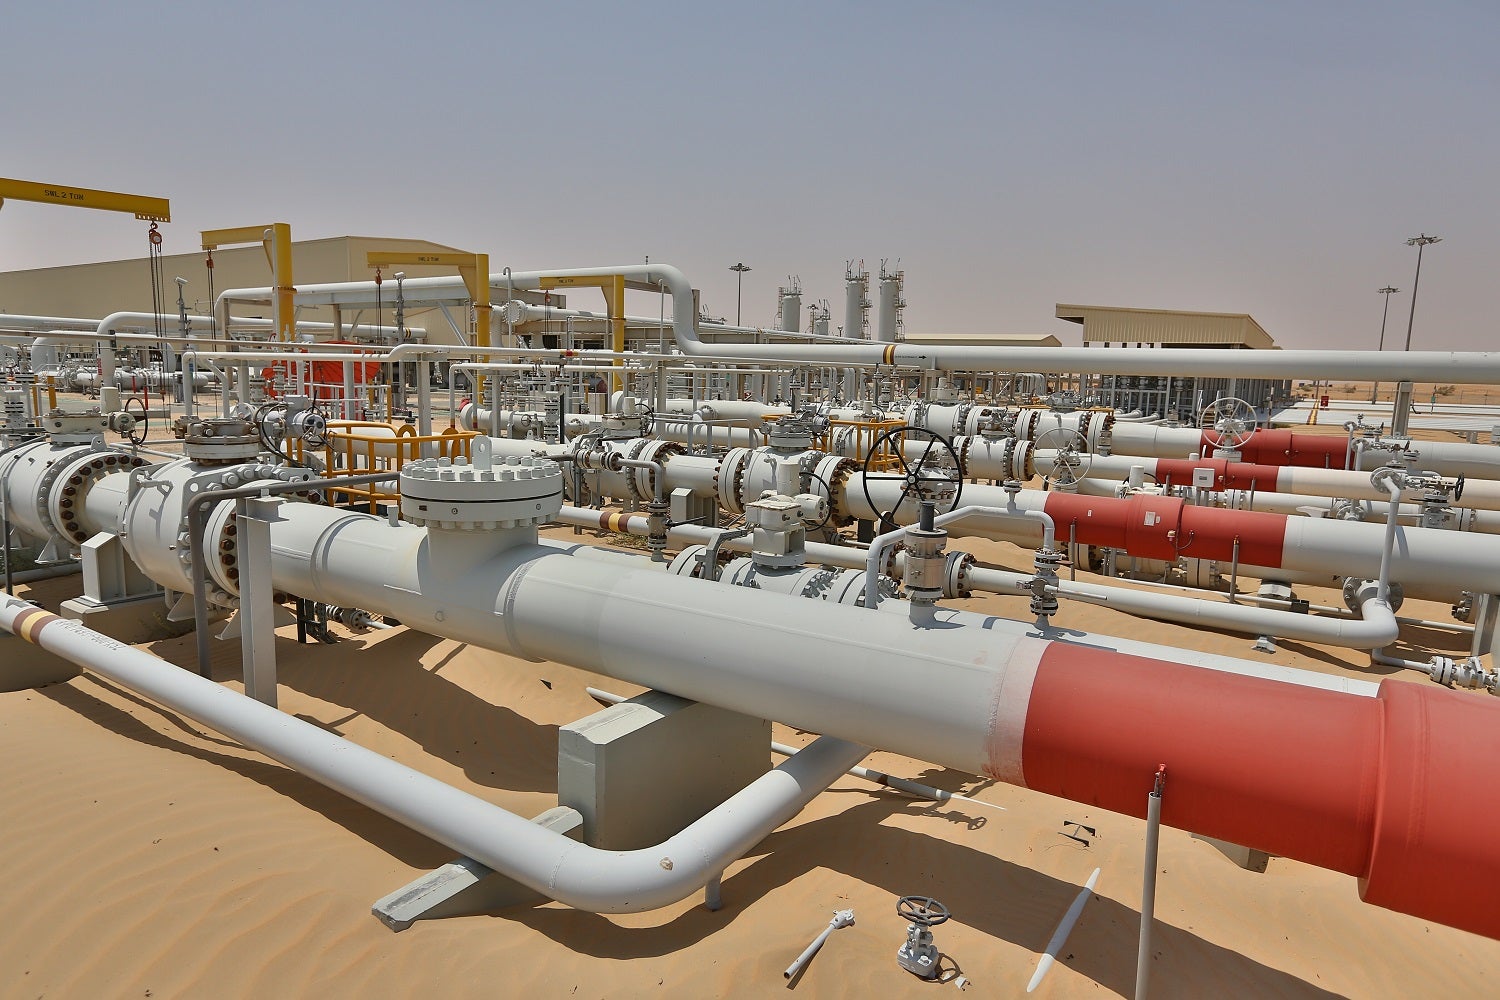
The onshore oil and gas business of Abu Dhabi National Oil Company (Adnoc Onshore) has awarded China’s Jereh Group a contract valued at AED1.44bn ($392.1m) for the engineering, procurement and construction (EPC) of wellhead surface facilities and flowlines at the Bu Hasa cluster of oil fields in Abu Dhabi.
The cluster includes the Bu Hasa, Bida Al-Qemzan and Huwaila fields. The objective of the project is to build wellhead surface facilities and lay gathering flowlines that will connect new wells to the existing production network.
The scope of work on the project also covers the design, fabrication and installation of:
- production well module skids
- gas lift skids, which inject gas into wells to help lift the oil
- skid-mounted wellhead control panels
- solar power units
The framework agreement awarded by Adnoc Onshore on a call-off basis has a duration of 36 months, with an extendable option of 24 months, Jereh said in a filing with China’s Shenzhen Stock Exchange, where it is listed.
Adnoc Onshore is Adnoc Group’s largest production subsidiary, accounting for about 2 million barrels a day (b/d) of crude and about 7 billion cubic feet a day of associated gas from four primary onshore asset clusters: Bab, Bu Hasa, North East Bab and South East.
Maintaining and enhancing oil output levels at the Bu Hasa asset is critical to Adnoc Onshore’s contribution to parent company Adnoc Group’s target of expanding crude oil production capacity to 5 million b/d by 2027, an initiative known as Accelerated Integrated Programme 5. The state energy company’s total production capacity currently stands at approximately 4.85 million b/d.
Prior to this contract, Adnoc Onshore selected Jereh Oil & Gas Engineering Company in 2024 for a project to digitally connect 2,443 wells at the Bab, Bu Hasa and South East cluster of onshore oil fields in Abu Dhabi for remote operations. The contract, formally awarded in 2025, was valued at $920m.
Abu Dhabi contracts
The contract for the Bu Hasa wellhead facilities and flowlines is among a trio of projects totalling approximately $2.7bn that has been awarded by Adnoc Group in recent weeks, Jereh announced in its stock market filing.
The largest of the three contracts, valued at $1.7bn, is for the Ruwais Diyab unconventional gas development in Abu Dhabi. Awarded to Jereh on a design, build and operate model, the contract has a duration of 29 months for construction works and 60 months of operations, with up to two five-year extensions available.
Adnoc achieved final investment decision on the Ruwais Diyab unconventional gas development project on 2 November, during the Abu Dhabi International Petroleum Exhibition and Conference 2026.
The project will deliver 345 million standard cubic feet a day (scf/d) of raw gas from 2029 over a 25-year period, with the potential to reach up to 1 billion scf/d in the future.
The scope of work on the Ruwais Diyab project covers:
- wellsite facilities
- a central processing facility
- gas gathering pipelines and product export pipelines
- utilities
The plant will treat the raw gas and recover the liquids produced with it. It will also treat produced water, which is the water that comes up from the wells with the gas, and recover sulphur. Finished products will be delivered to designated receiving facilities.
When the operation period ends, Jereh will either hand the facilities over to Adnoc or decommission them and restore the site, as the contract and the owner require.
The third contract covers Adnoc Onshore’s Bab and North East Bab 1 tie-in project, where the main scope of work involves tying in new oil producer wells and removing and modifying surface facilities at existing producer wells.
The project’s scope also covers supporting works for water supply wells, water injection wells, disposal wells and water-alternating-gas injection wells. Several existing wells will also be upgraded with digital systems.
Jereh said the value of its contract is $599m, with a duration of 60 months. Similar to the Bu Hasa project, this contract also uses a framework model wherein Adnoc Onshore will issue work orders in batches according to its execution plans.
MEED previously reported that Adnoc Onshore had divided the scope of work on the Bab and North East Bab 1 tie-in project into 18 EPC packages. Along with Jereh, Adnoc Onshore has picked Abu Dhabi-based Robt Stone Middle East for a portion of work on the project.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21355151/main3320.jpg -
PDO awards contract for Al-Ghubar oil field project
12 November 2026
Register for MEED’s 14-day trial access
Petroleum Development Oman (PDO) has awarded the main contract for a project to build a facility to handle additional oil production from the Al-Ghubar field in the sultanate.
The Al-Ghubar field is located in the Ghaba Salt Basin at Qarn Alam, within majority state-owned PDO’s Block 6 concession area.
The Al-Ghubar gas-oil gravity drainage (GOGD) facility will be designed as a sour (hydrogen sulphide) facility and is expected to handle a maximum oil production rate of 1,800 standard cubic metres a day (cm/d), a total water flow rate of up to 10,421 standard cm/d and gas lift of up to 256,934 standard cm/d. Production from the planned Al-Ghubar GOGD facility will be exported to PDO’s main oil line.
China-based Jereh Group has won the contract for the Al-Ghubar GOGD facility project, sources told MEED.
A project kick-off meeting between PDO and Jereh has also recently taken place, the sources said.
MEED previously reported that Jereh had emerged as the lowest bidder for the project.
The following contractors, among others, are understood to have been bidding for the Al-Ghubar GOGD facility project:
- Engineering for the Petroleum & Process Industries (Egypt) / Petrojet (Egypt)
- GS Engineering & Construction (South Korea)
- Jereh (China)
- Larsen & Toubro Energy Hydrocarbon (India)
PDO floated the tender for the Al-Ghubar GOGD facility project in March, setting an initial bid submission deadline of 4 May, MEED previously reported.
PDO later extended the deadlines for the submission of technical and commercial bids to 26 July and 7 August, respectively. Contractors submitted technical proposals by the revised deadline, according to sources.
After receiving the technical bids for the project in July, PDO granted contractors until 16 August to submit commercial bids. It eventually extended the deadline to 1 September, with contractors submitting commercial proposals by that date, as MEED reported.
The scope of work on the Al-Ghubar GOGD project covers the engineering, procurement and construction (EPC) of the following:
- On-plot scope, consisting of:
- Production separator
- Test separator
- Concentric wash tank
- Wet oil pump
- Water bath heater
- Surge tank
- Gas injection/gas lift compressor (centrifugal)
- Utilities (instrument air compressors, chemical injection skids, drain system, vent system)
- Suction scrubber
- Air coolers
- Discharge scrubbers
- Condensate flash drum
- Atmospheric pressure knock-out drum
- Flare system
- Gas heater
- Water disposal pump
- Oil shipping pump
- 132kV substation and plant substation (housing 6.6kV and 415-Volt switchboard)
- Control room
- Off-plot scope consisting of:
- Off-plot pipeline network (bulk header, test header, gathering infrastructure/ gathering line header, instrument air header, water disposal header)
- Two remote manifold stations
- Tie-in connection to main oil line
- Tie-in to gas network pipeline
PDO previously intended to tender the Al-Ghubar GOGD project under its framework structure with selected EPC contractors, but ultimately tendered it separately.
PDO is the operator of Oman’s Block 6 hydrocarbons concession, the sultanate’s largest and most prolific concession. Situated onshore and covering an area of 75,119 square kilometres, Block 6 contains 202 oil fields and 43 gas fields. PDO produces approximately 680,000 barrels a day of oil and condensates from the fields.
The Omani government holds a 60% stake in PDO through Energy Development Oman. The other shareholders are UK-based Shell (34%), France’s TotalEnergies (4%) and Thailand’s state-owned PTTEP (2%).
https://image.digitalinsightresearch.in/uploads/NewsArticle/21345337/main2647.jpg -
Laing O’Rourke joins the international exit list
12 November 2026
Commentary
Colin Foreman
EditorRegister for MEED’s 14-day trial access
Laing O’Rourke’s decision to seek a buyer for its Middle East business marks the end of an era for UAE construction.
In the early 2000s, the contractor was among the leading names in the market. Its work at Dubai International airport, the Atlantis hotel on the Palm Jumeirah and the ski slope at Mall of the Emirates made it arguably the UAE’s most prominent contractor during the pre-global financial crisis construction boom.
Its activities were not limited to Dubai. A partnering agreement with Aldar for Al-Raha Beach then made it the most active contractor in Abu Dhabi almost overnight.
The global financial crisis changed its fortunes. The Aldar Laing O’Rourke joint venture ended. Unsettled by payment problems and wider stress in the industry, the company took a more cautious approach to clients and projects in the region. One executive at the time told MEED: “You might see lots of tower cranes, but none of them are doing work that we would want to do.”
The contractor’s appetite partially returned in the late 2010s, when it won Al-Wasl Plaza at the Expo 2020 site in Dubai. It also became a leading player in the growing data centre market, delivering facilities for repeat clients, including Khazna and Equinix.
Data centres have since been its focus. These are significant projects, but they lack the public profile of the airport, Atlantis and Al-Wasl Plaza. As its profile faded, the company sold its UAE joinery arm to Dubai-based Arco Turnkey Solutions in 2025.
Laing O’Rourke now looks set to follow other international contractors that have, for various reasons, left the region, including Murray & Roberts, Balfour Beatty, Multiplex, Carillion and Bam. With a record £17.2bn order book anchored by UK and Australian infrastructure, the group’s priorities clearly lie elsewhere.
Whoever buys the business will inherit strong data centre credentials. For much of the market, however, Laing O’Rourke will be remembered for the landmark projects that defined the UAE’s boom years.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21344577/main.jpg