Aramco and DHL form joint logistics company
8 February 2024
Register for MEED's guest programme
Supply chains have become a key issue for businesses over the past three years as the global economy emerged from Covid-19 lockdowns and then faced disruptive events such as the grounding of the EverGiven in the Suez Canal and the war in Ukraine.
More recently, Houthi attacks on shipping passing through the Red Sea have forced many vessels to travel around Africa rather than through the Suez Canal. This has delayed deliveries and driven up costs.
These disruptions, together with technological advances such as AI and a growing emphasis on sustainability, are forcing logistics providers and their customers to rethink how their supply chains are managed.
Locally in Saudi Arabia, the supply chain challenge is of particular importance as the kingdom seeks to overhaul its economy with large-scale capital expenditure projects as part of Vision 2030.
Joint venture
Two of the world’s largest players in their respective fields, Saudi Aramco and DHL Supply Chain, are responding to these challenges and aim to revolutionise logistics for the energy, chemical and industrial sectors by joining forces to incorporate a new joint venture company known as Asmo.
Salem Al Huraish, chairman of Asmo, described the new company in a speech at its launch in Khobar on 5 February as “a national champion that will reform the supply chain industry for the energy, chemical and industrial sector in the region.”
The company involves two industry heavyweights combining their expertise. “Aramco is a massive procurement beast, and is very successful. DHL is a logistics company. Everybody does their respective pieces separately,” said Craig Roberts, CEO of Asmo.
“Bringing the two together in a separate entity is something that hasn’t been done before. We believe there are massive efficiencies for the industry from doing this.”
The company, which has been planned for three years, comes at an opportune time for Aramco and DHL, but also for Saudi Arabia and the global logistics sector.
“We are launching a company with an ambitious vision to become a market leader in the Mena region,” said Wail Al Jaafari, Aramco executive vice-president of technical services.
“Asmo can offer world-class end-to-end supply chain solutions, creating value for customers while enhancing the resilience of their supply chain.”
New technologies
As well as changes in Saudi Arabia, the nature of the logistics industry is being transformed by new technologies, notably artificial intelligence (AI).
“We stand at a defining junction of the logistics industry where global trends are dramatically reshaping the landscape,” said Oscar de Bok, CEO of DHL Supply Chain. “The world is grappling with supply chain disruption, rising costs and the urgent goal for sustainability.”
Asmo intends to take a smart approach to revolutionising supply chain logistics. “It’s a lot about being smart,” said De Bok. “We talk a lot about deploying technology, digital marketplaces and warehouse technology … there is a lot of cool stuff being deployed, but it is not always rocket science. Some of it is pretty basic stuff you need to do,” he said.
The journey for Asmo is just beginning. It is a long-term venture that aims to develop a significant presence in the kingdom over the coming years.
“We are in partnership together and at the start of that journey right now,” Roberts added. “We are looking at our supply chains, gaining insights and asking how we get smarter. When we build in new warehouses, the question is, where do you put them? What technology do we deploy? We are in that discovery phase right now.”
One of the critical aspects of Asmo’s strategy involves assessing physical infrastructure needs. “For physical infrastructure, Asmo is assessing its options. We are looking at that right now. Aramco has a number of facilities for itself and its affiliates. We are looking at the best places to put the warehouses,” Roberts said.
Saudi infrastructure
As well as Asmo’s dedicated infrastructure, the Saudi government is also building infrastructure to support the kingdom’s logistics industry. “They’re putting infrastructure in place. They’re making it quite easy for us to do this. I think the support of the government is vital,” he said.
Once established in the kingdom, Asmo aims to take its operations overseas. This is likely to involve expanding into other GCC markets first and then further afield. Both Aramco and DHL can support this strategy as both companies have significant operations outside Saudi Arabia. DHL is a global logistics player, and Aramco, while primarily being a Saudi company, has operations in many other markets worldwide, including the US.
If Asmo gets it right, the rewards are significant. “The supply chain and logistics market in the Mena region is worth around $100bn. Our goal is to have a major share of this. It is truly a new giant in the making,” said Al Jaafari.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 QatarEnergy gives North Field West topside bidders more time
2 October 2026
-
 Egypt implements oil and gas storage projects worth $1.1bn
2 October 2026
-
 Bankability key to Saudi PPP pipeline
2 October 2026
-
 Financing hinders progress at major Iraqi refinery project
2 October 2026
-
 Saudi pre-budget leans on borrowing to fund projects
2 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
QatarEnergy gives North Field West topside bidders more time
2 October 2026

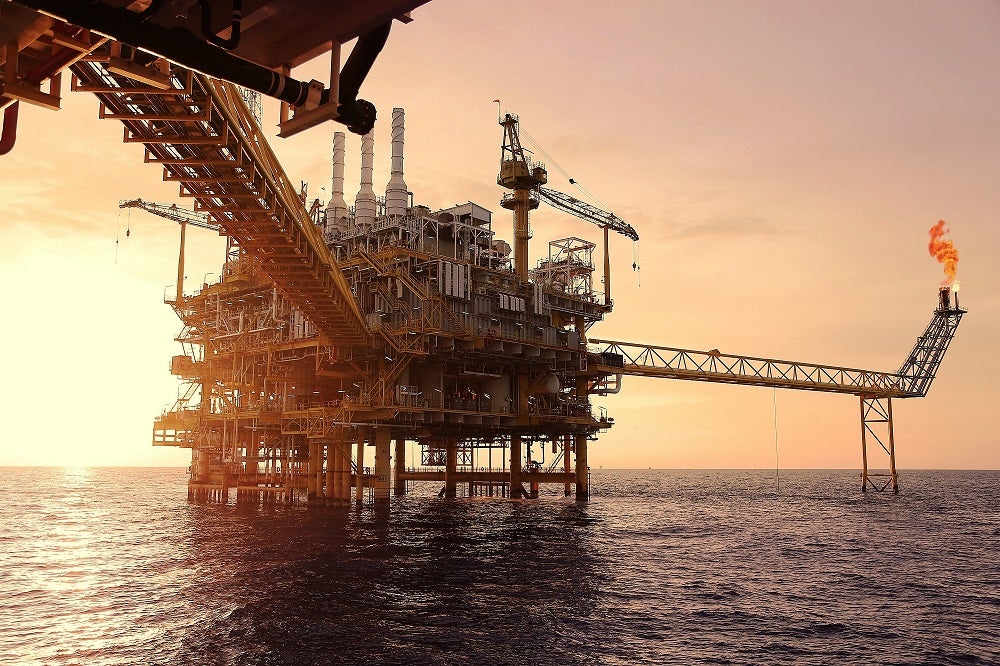
QatarEnergy has granted contractors more time to prepare bids for a tender covering the engineering, procurement, construction and installation (EPCI) of large platforms for the North Field gas field in Qatari waters.
Contractors now have until 12 October to submit technical bids for the project, according to sources. Commercial bids are currently due on 10 November.
The following contractors, among others, are understood to be bidding for the North Field West (NFW) production deck modules (PDMs) tender:
- China Offshore Oil Engineering Company (China)
- Larsen & Toubro Energy Hydrocarbon (India)
- McDermott (US)
- Saipem (Italy)
The core scope comprises the EPCI of four PDMs and associated structures. The PDMs will increase gas production from North Field reservoirs and provide additional gas feedstock for the NFW liquefied natural gas (LNG) development.
The tender, issued earlier this year, forms part of the wider NFW project, the third and final phase of the state enterprise’s North Field LNG expansion programme.
The previous deadlines for technical bids were 30 August, 15 September and 28 September, while commercial bids were previously due on 25 October, as MEED reported.
Before issuing the PDMs tender, QatarEnergy awarded US firm McDermott a contract for the EPCI of four offshore jackets that will also support gas feedstock supply for the NFW LNG project. The contract is estimated to be worth about $200m, MEED reported in January.
North Field LNG expansion
QatarEnergy is advancing the three phases of its estimated $40bn North Field LNG expansion project. EPC works on all three projects are progressing.
QatarEnergy is understood to have committed nearly $30bn to the first two phases – North Field East (NFE) and North Field South (NFS) – which will lift Qatar’s LNG production capacity from 77.5 million tonnes a year (t/y) to 126 million t/y by 2028.
QatarEnergy awarded the main EPC contracts for NFE in 2021. The project was intended to raise LNG output to 110 million t/y by 2025. The $13bn EPC package – covering the EPCI of four LNG trains, each with a capacity of 8 million t/y – was awarded in February 2021 to a consortium of Japan’s Chiyoda and France’s Technip Energies.
In May 2023, QatarEnergy awarded the $10bn main EPC contract for NFS to a consortium of Technip Energies and Consolidated Contractors Company (CCC). The contract includes two LNG trains, each with a capacity of 7.8 million t/y.
Once fully operational, the first two phases are expected to add 48 million t/y of LNG supply to the global market.
QatarEnergy took the final investment decision on NFW earlier this year, awarding an EPC contract estimated at $8bn to a joint venture comprising Technip Energies, CCC and Gulf Asia Contracting in February.
Chiyoda carried out the front-end engineering and design work for the NFW LNG project.
The NFW scope covers the EPC of two LNG trains with a combined capacity of 16 million t/y, as well as associated facilities for gas treatment, natural gas liquids recovery and helium extraction.
In addition to LNG, NFW is expected to produce about 175,000 barrels of oil equivalent a day of condensate, ethane and liquefied petroleum gas.
With all three phases under EPC execution – and NFE scheduled for commissioning later this year – QatarEnergy is positioning itself to remain one of the world’s largest LNG suppliers in the long term.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20208200/main.jpg -
Egypt implements oil and gas storage projects worth $1.1bn
2 October 2026
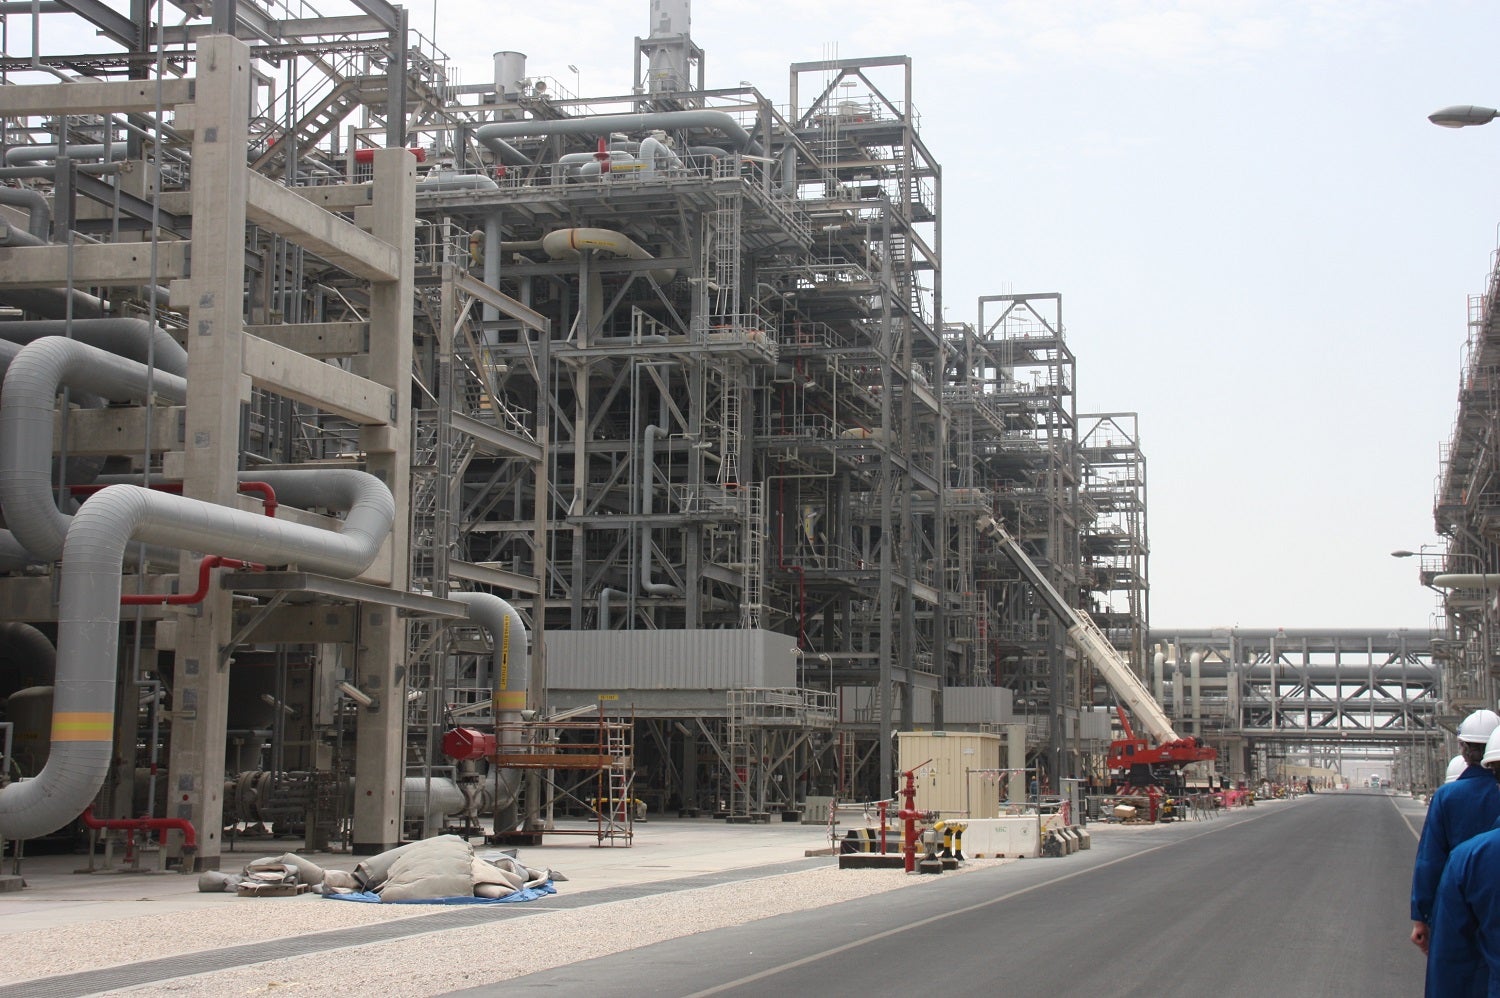
Egypt is implementing oil and gas storage projects worth a total of £E54bn ($1.1bn), according to a statement released by the country’s cabinet.
Active developments include expanding El-Hamra Petroleum Port in El-Alamein on the Mediterranean coast, as well as building a jet-fuel storage and transport hub at the Badr depot in Cairo.
Other projects include constructing new storage tanks at refinery complexes in Amreya, Alexandria; Assiut; and Cairo.
Over the past 12 years, Egypt has built 84 petroleum storage facilities with a total capacity of 5.2 million tonnes, the cabinet statement said.
Egypt has invested £E42.7bn ($880m) in developing these facilities, with the aim of bolstering domestic energy security.
Completed infrastructure projects include facilities in Sohag (Upper Egypt) and Alexandria.
They also include offshore terminal and storage facilities, a liquid bulk station in Ain Sokhna, and strategic crude oil storage tanks across the country.
Storage facilities have become a strategic priority for Egypt since the US and Israel attacked Iran on 28 February, triggering a regional war that has disrupted shipping through the Strait of Hormuz.
The disruption has made imports of hydrocarbon products into Egypt less predictable, increasing the importance of strategic stockpiles.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20208195/main.jpg -
Bankability key to Saudi PPP pipeline
2 October 2026
Saudi Arabia’s National Centre for Privatisation & PPP (NCP) holds structured talks with bidders and lenders before launching transactions to ensure projects in its pipeline are bankable, according to a senior official.
Speaking on a panel at MEED’s Shaping Mega Projects conference in Riyadh on 28 September, Tariq Alghaziri, executive vice-president at the NCP, said the centre carries out market sounding with potential bidders and debt providers, including commercial and Islamic banks, before announcing deals.
“Bankability is a key word for us,” he said. “You can structure the deal in the way you want. You can have whatever technicalities and technologies are required, but is it suitable for the private sector to deliver? That’s the big question.”
Alghaziri said the national privatisation strategy, approved at the end of 2025 and published at the start of 2026, sets the NCP’s targets up to 2030 and outlines its project pipeline. The strategy coincides with the third phase of Vision 2030, which he said is focused on measuring impact after earlier phases established the legal framework and enabled the private sector.
Public-private partnership (PPP) contracts typically run for 25 years and, in some cases, more than 40 years, he said, which makes early engagement essential. “When we launch it, all the bidders, suppliers, EPC contractors, banks and ECAs are on the same page, and then they just have to align on commercial points and not negotiate legal aspects.”
Risk transfer
Jonathan Looker, managing director for Saudi Arabia at UK consultancy Mott MacDonald, said the public and private sectors often perceive risk very differently.
"Can you put yourself in the shoes of the person you’re trying to transfer risk to?” he said. “There isn’t one single allocation model that is fit for every project.”
Looker said failure to agree on risk can prevent projects from reaching financial close. "I’ve unfortunately been involved in a number of projects where we just can’t get the deal done because there is not a meeting of minds around a specific aspect of risk.”
Alghaziri said Saudi regulations now state that the party with the capacity to manage a risk should take it, but that risk carries a cost. “You cannot just give the risk without pricing it,” he said. The NCP has trained more than 300 people over the past five or six years, including through a PPP professional certification it introduced in the kingdom.
Early planning
Hesham Ouf, senior director of finance at Roshn Group, the Public Investment Fund (PIF) subsidiary, said risk management begins at the feasibility stage. “You need to have the stage gates right from the beginning until the project is delivered,” he said.
Ali Al-Kuwari, senior manager of export development at Qatar Development Bank (QDB), said early disclosure of procurement needs allows lenders to assess project risk. “For me, the answer is very easy. I’ll ask for a sovereign guarantee,” he said.
Wesley Thomson, partner and head of environmental, social and governance (ESG) at UK property consultancy Knight Frank, said climate exposure is becoming a central risk for long-life assets. “Mitigation is not the right word any more. I prefer to say adaptation, because the truth is you need to adapt to what we’re seeing.”
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20207592/main.png -
Financing hinders progress at major Iraqi refinery project
2 October 2026
Financial problems are hindering progress at Iraq’s Al-Faw Investment Refinery project, according to industry sources.
Despite the main contract being signed more than two years ago, construction of the main refinery units has yet to begin because of ongoing financial issues, sources said.
In May 2024, a statement released by the Iraqi Prime Minister’s Office said that Iraq’s state-owned Southern Refineries Company and China National Chemical Engineering Company (CNCEC) had signed a contract to develop the project.
Iraq’s Oil Ministry previously said the project would be worth $7bn-$8bn.
The project has struggled to make progress even after direct intervention by Iraq’s previous prime minister.
On 6 August 2025, 15 months after the May 2024 contract signing with CNCEC, Mohammed Shia Al-Sudani, then prime minister, chaired a special meeting to resolve administrative and technical obstacles preventing the project from starting.
At the time, Al-Sudani said the refinery project would have significant financial returns and would be “a breakthrough in the oil industry”.
While the meeting in 2025 is believed to have solved some of the administrative issues blocking progress, financial problems with the project remain, sources said.
The Al-Faw project is part of the Iraqi government’s plan to increase Iraq’s refining capacity, attract foreign investment and increase domestic production of petroleum products.
Under existing plans, the refinery will have a capacity of 300,000 barrels a day and will produce oil derivatives for both domestic and international markets.
The project will be carried out in two stages.
The first phase will involve refining operations, while the second will involve constructing a petrochemicals complex with a capacity of 3 million tonnes a year.
The project also includes building a 2,000MW power plant and establishing the Al-Faw Academy for Refinery Technology to train 5,000 Iraqi workers who will eventually work at the facility.
Hualu, a subsidiary of CNCEC, signed a preliminary principles agreement for the project in December 2021.
Due to material price inflation since December 2021, some insiders believe the project value may now be significantly higher than the previously estimated $7bn-$8bn.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20207119/main.jpg -
Saudi pre-budget leans on borrowing to fund projects
2 October 2026
Saudi Arabia plans to spend SR1.39tn ($371.2bn) in 2027, according to the Finance Ministry’s pre-budget statement. That is 3% less than the estimated outturn for 2026, after regional conflict and the closure of the Strait of Hormuz pushed this year’s expenditure well past its allocation.
The ministry now expects 2026 spending to reach SR1.44tn, which is SR122bn or 9.3% above the SR1.31tn approved in the budget. Revenues are estimated at SR1.19tn, SR43bn above budget, leaving a deficit of SR245bn, equal to 4.9% of GDP. The original budget assumed a SR165bn deficit, or 3.3% of GDP.
For 2027, the statement projects revenues of SR1.2tn and a deficit of SR191bn, or 3.6% of GDP. Expenditure is forecast to rise to SR1.48tn in 2028 and SR1.54tn in 2029, with deficits of SR177bn and SR192bn projected for those years. On the ministry’s figures, the kingdom will run cumulative deficits of SR560bn ($149.3bn) between 2027 and 2029.
The economic backdrop has deteriorated sharply. The ministry expects real GDP to contract by 3.6% in 2026, driven by a 21.8% fall in oil activity, while non-oil activity grows by 3.2%. It forecasts a rebound to 12.8% real growth in 2027.
Capital spending
The statement does not publish a capital expenditure figure or a sector breakdown. Those will follow with the budget in Q4. It does signal that project spending will continue. As Vision 2030 enters what the statement calls its third phase, the government says efforts will focus on “accelerating the pace of delivery and capitalising on growth opportunities through continued government capital expenditure”. It also wants a stronger role for the Public Investment Fund (PIF) and the National Development Fund in stimulating domestic investment.
The ministry says it will “implement infrastructure-related programmes” and direct resources “towards priority programmes and projects”. It also commits to “maximise the utilisation of existing government assets and investments”. That wording points to a sharper focus on completing and monetising existing schemes rather than launching new ones.
The medium-term debt strategy is designed to ensure “the continuity of the implementation of priority projects without being linked to the fluctuations of the economic cycle”, according to the statement.
The government’s revenue scenarios hold expenditure at SR1.39tn in all three cases. Under the lowest revenue case of SR1.13tn, the deficit widens to SR259bn. The highest case of SR1.26tn narrows it to SR132bn. Any change falls on borrowing rather than on spending.
The ministry says debt will deliberately rise by the end of 2027, and the borrowing plan will be disclosed by the end of this year. Alongside bonds, sukuk and loans, the government plans to expand “alternative government financing, including financing of projects, infrastructure and export credit agencies” in 2027 and over the medium term.
Private capital
The statement presents private investment as a growing share of project delivery. Investment in privatisation and public-private partnership (PPP) projects reached about SR180bn by the end of 2025. The National Privatisation Strategy was approved in November 2025. Ten privatisation and PPP projects have been launched under it in the first half of 2026, including the Prince Naif Bin Abdulaziz International Airport PPP in Qassim. Contracts were signed for the Sabic Mental Health Hospital and the Jubail Container Terminal, taking the total to 83 partnership contracts. Private capital investment has exceeded SR56.2bn, against a target of SR240bn by 2030.
The National Infrastructure Fund has committed SR10.5bn since 2022 to projects with a combined value of about SR59.3bn, of which SR44.1bn is private investment. Projects it has backed include the Neom green hydrogen project, the Shuaibah solar photovoltaic plants, the Prince Mohammad Bin Abdulaziz Airport expansion, the Jubail-Buraidah independent water transmission pipeline and the Ezditek data centre. The fund plans to expand into healthcare, education, sports and artificial intelligence.
PIF’s domestic investments totalled about SR750bn between 2021 and 2025. The statement lists several recent contracts across its portfolio. Diriyah Company, the PIF-owned developer of the Diriyah gigaproject, awarded a SR1.8bn contract to a consortium of local companies to build the Saudi Museum of Contemporary Art. PIF-owned Soudah Development signed a SR1.3bn agreement with National Grid SA, the transmission subsidiary of Saudi Electricity Company, to deliver electricity infrastructure for the Soudah Peaks project. Saudi Entertainment Ventures, also owned by PIF, plans 14 destinations across 13 cities, with investment of more than SR45bn. The Saudi Export-Import Bank plans to provide SR41.6bn of financing and insurance to non-oil exporters in 2027.
Logistics investment has also become a priority since the disruption to Gulf shipping. The share of non-oil exports passing through Red Sea ports rose to 40.7% during the crisis, from 19.3% before it. In July, the General Ports Authority signed contracts worth up to SR1bn for seven logistics centres at Jeddah Islamic Port and Al-Khumrah. A separate logistics corridors initiative connects Gulf ports to the Red Sea by road and rail.
The final 2027 budget is due for approval in Q4.
MEED’s October 2026 report on Saudi Arabia includes:
> COMMENT: Saudi projects hold steady
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflict
> DATABANK: Saudi data indicates project spending shiftTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20206117/main.gif