Saudi water projects momentum holds steady
12 September 2023
 This package on Saudi Arabia’s water sector also includes:
> Riyadh holds water pipeline bid clarifications
> Red Sea awards Amaala utility package
> Five banks agree $545m Rabigh 4 financing
> Saudi Arabia extends desalination bid deadline
> Albawani joins Jafurah water developer team
> Saudi Arabia evaluates Al-Haer wastewater bids

The Saudi water market remains the region’s largest, with $30bn-worth of projects in varying planning and procurement stages.
The sector is expected to expand further with multibillion-dollar capital expenditures allocated by the potable water and wastewater collection and treatment firm, the National Water Company (NWC), and Saline Water Conversion Corporation (SWCC), the world’s largest producer of desalinated water.
This offers great opportunities for water asset developers and engineering, procurement and construction (EPC) contractors aiming to capture a share of the kingdom’s burgeoning water projects market.
SWCC, NWC and the principal buyer of water, Saudi Water Partnership Company (SWPC), awarded over $32bn of water infrastructure and utility projects between 2013 and 2022, according to MEED Projects data.
Driving investment within the sector is the need to improve water security, a key component of Saudi Vision 2030, along with rising demand due to population and economic expansion.
Reducing the carbon footprint of the kingdom's existing seawater desalination fleet, dominated by plants running on older technologies, is also contributing to the urgency to build more energy-efficient water infrastructure.
This is matched by moves to make potable and wastewater water transmission and distribution more efficient and to minimise leakage and non-revenue water. The kingdom also needs to expand its overall water storage capacity to improve its emergency response.
Simultaneously, like most of its groundwater-scarce neighbours, there is growing pressure to adopt treated sewage effluent for agricultural and industrial applications to reduce demand for seawater desalination and comply with the kingdom’s circular carbon economy approach.
“It is an interesting time for the Saudi water sector,” says a Dubai-based water expert.
“There are many projects in the tendering phase, but there is also some degree of uncertainty in terms of how the roles of the key stakeholders could shift [in the future].”
This stems from the years-long restructuring of the sector and last year's cabinet resolution approving the transfer of water production, transportation and storage assets owned directly or indirectly by SWCC to Water Solutions Company, a wholly-owned subsidiary of the Saudi sovereign vehicle, the Public Investment Fund (PIF).
There is widespread expectation that SWCC will focus on research and development following the transfer of its assets to the PIF subsidiary, although this has not been formally announced.
Diversified clients
The lengthy restructuring of the kingdom’s water sector and rapid advance of so-called gigaprojects have diversified the profile of clients in the kingdom.
Neom and its subsidiary Enowa, SWCC transmission arm Water Transmission & Technologies Company (WTTCo) and other gigaproject developers, such as the royal commissions for Riyadh City and Al-Ula, have joined the mainstream water utility companies and municipalities in tendering new water infrastructure contracts over the past year.
In terms of projects in the pre-execution phase, SWPC is the top client, with a pipeline of projects worth at least $7bn.
SWPC is mandated to procure all water infrastructure projects in the kingdom on a public-private partnership (PPP) basis, including water desalination, wastewater treatment, transmission and reservoirs.
Its latest Seven-Year Planning Statement covering 2022-28 stipulates the procurement of about 50 independent water infrastructure projects, including several in the bid stage.
SWPC’s future projects pipeline outperforms that of NWC and SWCC. Neom, Enowa, WTTCo and the Royal Commission for Al-Ula round out the top seven clients.
 Riyadh rides power projects surge
Independent projects
Following consecutive awards of independent water producer (IWP) and independent sewage treatment plant (ISTP) contracts between 2019 and 2021, SWPC has recently paced out the award of new contracts.
It has only awarded one contract, directly negotiated with Saudi utility developer Acwa Power for the Shuaiba 3 seawater reverse osmosis (SWRO) project in 2022. This year, it awarded another contract for the Rabigh 4 IWP scheme, in addition to the contract to develop the kingdom’s first independent water transmission pipeline, which connects Rayis and Rabigh.
SWPC is evaluating the bids it received for the contract to develop the Al-Haer independent sewage treatment plant (ISTP), the first of the round-three projects under its ISTP programme, and expects to receive bids in October for the 300,000 cubic-metre-a-day (cm/d) Ras Mohaisen IWP.
The contract to develop the kingdom’s first independent strategic water reservoir (ISWR) project is expected to be awarded this year. The Juranah ISWR has a capacity to store 2.5 million cubic metres of water. The project is anticipated to significantly boost water security, particularly in Mecca and Medina, which host several million pilgrims annually.
EPC works
Despite moves to transfer its assets to the PIF subsidiary, SWCC cemented its reputation as the world’s largest producer of desalinated water when its fleet of 30 desalination plants reached a total combined capacity of 6.6 million cm/d in 2022.
The company is not resting on its past success, having issued successive tenders for SWRO plants using an EPC model over the past 12-18 months.
In July this year, it invited bids for the contract to build a 200,000 cm/d SWRO facility in Ras al-Khair.
This came three months after it received two bids for the contract to build the second phase of the Shuaibah water desalination plant, which has an even higher capacity of 545,000 cm/d.
Around the same time in March, SWCC tendered a contract to construct a greenfield SWRO plant in Yanbu with a design capacity of 500,000 cm/d.
SWPC last awarded a major SWRO contract in mid-2021. The giant 1 million cm/d Jubail SWRO plant is being built by a team of Metito and local firm Saudi Services for Electromechanic Works.
Before this, in late 2019, it awarded a contract to construct a 400,000 cm/d SWRO plant in Shuqaiq to a team of Spain’s Acciona and Al-Rashid Trading & Contracting Company.
SWCC, though WTTCo, has also tendered multiple water transmission projects, including pipelines around Riyadh and connecting Riyadh and Ras al-Khair, Shuqaiq and Jizan and Al-Duwadimi and Atif.
In its 2022 annual report, SWCC stated that it had achieved exceptional results in supporting the Saudi Green Initiative, reducing carbon emissions, increasing operational efficiency to above 99 per cent and saving SR1.6bn ($427m) in operational costs.
The company also “increased local content in its operational efficiency by 61 per cent and demonstrated noteworthy patent accomplishments, innovations, studies and scientific publications”.
Innovation
New tourism-related developments, the expansion of industrial complexes and the need to limit carbon emissions are driving capacity-building and innovation.
The Red Sea development is completing the kingdom’s first private sector multi-utility project, which includes developing and operating a solar photovoltaic power plant, battery energy storage system, water desalination and treatment and waste recycling plants in one contract.
In addition to tendering major water transmission and distribution networks, Neom is also finalising the design for a zero-liquid discharge SWRO plant catering to the development. Enowa, Japan’s Itochu and France’s Veolia are expected to tender the project's EPC package soon.
The proposed state-of-the-art desalination plant will be powered 100 per cent by renewable energy and use advanced membrane technology to produce separate brine streams.
This will enable the production of brine-derived products, which will be developed and monetised downstream. The bigger plan includes establishing a brine processing complex in Oxagon, which could require an investment of between $15bn and $20bn.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 UAE economy shows resilience
4 November 2026
-
 Kuwait appoints KPMG for ports strategic plan
4 November 2026
-
 Combined Group signs Kuwait upstream contract
4 November 2026
-
 Qiddiya seeks interest for water infrastructure packages
4 November 2026
-
 Riyadh plans multibillion northern roads network overhaul
4 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
UAE economy shows resilience
4 November 2026
 Commentary
Colin Foreman
EditorState-backed capital is carrying the UAE projects market through the economic shock of the Iran conflict. Government and government-related entities have accounted for $22.4bn of the $34.6bn of contracts awarded in Dubai so far this year, almost two-thirds of the total, according to regional project tracker MEED Projects. Private developers have deferred new launches, and off-plan residential sales in the emirate fell from $9bn in February to $4bn in August.
In Abu Dhabi, state-affiliated developers and cultural agencies are accelerating destination projects on Yas and Saadiyat islands, including the $1.7bn Sphere Abu Dhabi venue.
The energy sector is adding momentum. The UAE’s exit from Opec in May has freed Abu Dhabi National Oil Company (Adnoc) to make greater use of its spare crude capacity, and the company is on course to exceed its 2024 upstream project spending this year. Adnoc Gas has awarded $8.2bn of contracts for the second and third phases of its rich gas development programme.
The $3bn Taweelah C combined-cycle gas turbine plant accounted for most of the $4.17bn of power contracts awarded by early September, while Dubai’s AED30bn ($8.1bn) Tasreef stormwater programme is driving water sector activity.
MEED Projects tracks $103bn of transport schemes at pre-execution stages, including rail links that would give exporters routes that avoid the Strait of Hormuz.
Non-oil activity is also holding up. The UAE purchasing managers’ index compiled by financial information and analytics provider S&P Global reached a 20-month high of 55.3 in September. Net profits at the 10 biggest UAE banks rose 7% to AED47.8bn ($13bn) in the first half, supported by loan growth of 21%.
Meanwhile, Abu Dhabi is repairing relations with Riyadh after a year of friction over Yemen and Sudan. On 8 October, the two countries signed a memorandum of understanding covering power grid interconnection and freight rail.
Risks remain. The Washington-based IMF expects the GCC economy to contract by 3.8% this year, with recovery dependent on shipping through Hormuz returning to normal. US scrutiny of Iran-linked transactions is also tightening compliance demands on UAE banks. That said, there are reasons to be hopeful. The IMF expects the economy to rebound in 2027 with 7.7% GDP growth.
MEED’s November 2026 report on the UAE includes:
> GOVERNMENT: Abu Dhabi mends fences with Riyadh
> ECONOMY: UAE growth holds up as regional risks persist
> BANKING: UAE banks profit as credit growth surges
> UPSTREAM: Adnoc steps up crude expansion
> DOWNSTREAM: Adnoc funnels billions into boosting gas processing
> POWER: Gas-fired projects drive resilience in UAE power sector
> WATER: Tasreef scheme drives UAE water investment
> CONSTRUCTION: State-backed spending cushions UAE construction slowdown
> TRANSPORT: Infrastructure drives UAE growth agenda
> MANUFACTURING: UAE vehicle manufacturing push moves into productionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20947110/main.gif -
Kuwait appoints KPMG for ports strategic plan
4 November 2026
Register for MEED’s 14-day trial access
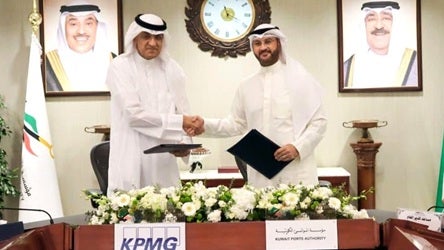
Kuwait Ports Authority (KPA) has appointed the local office of UK-headquartered KPMG to develop its ports strategic plan, which aims to improve the competitiveness, connectivity and performance of Kuwait’s commercial ports.
KPMG will act as lead consultant on the strategic consultancy engagement, with Netherlands-based Haskoning Nederland and local engineering firm Dar Gulf Consult providing engineering consultancy support.
KPMG will consolidate the three consultants’ work into a single strategic plan. It will lead the market, commercial and organisational analysis, as well as develop and implement the strategy.
The scope is split into two workstreams. The first covers strategy development, planning and an implementation framework, including an assessment of KPA’s current market position and performance.
The resulting strategic options and roadmap will be developed into detailed functional plans, supported by key performance indicators, a risk framework and a monitoring plan.
Under the second workstream, KPMG will set up and lead a strategic technical support office for 36 months. The office will provide KPA with strategic oversight, technical advisory services and integrated project management support.
KPA operates Kuwait’s three main commercial ports: Shuwaikh Port, Shuaiba Port and Doha Port.
In line with the New Kuwait Vision 2035 development strategy, KPA is transitioning its operations into high-efficiency smart ports by investing heavily in automated machinery, deeper navigational channels and significant berth capacity expansions.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21106611/main.jpg -
Combined Group signs Kuwait upstream contract
4 November 2026
Register for MEED’s 14-day trial access
Kuwait-headquartered Combined Group Contracting Company has signed a contract to repair and revamp production facilities in West Kuwait, according to a company statement.
State-owned upstream operator Kuwait Oil Company (KOC) awarded the contract, valued at KD9.7m ($31.4m).
The contract has a five-year term.
KOC issued the invitation to bid on 5 October 2025. The initial bid deadline was 4 January 2026, and a pre-tender meeting was scheduled for 4 November 2025.
The contract award to Combined Group was approved on 13 September 2026.
Kuwait’s oil and gas sector is currently in the midst of a major crisis, as disruptions to shipping through the Strait of Hormuz have dramatically reduced exported crude oil volumes.
The disruptions are the result of a regional war that started on 28 February when the US and Israel attacked Iran.
The disruptions to shipping in the Strait of Hormuz are also creating significant challenges for oil and gas construction projects, which normally import equipment and materials through the waterway.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21120792/main.png -
Qiddiya seeks interest for water infrastructure packages
4 November 2026
Register for MEED’s 14-day trial access
Qiddiya Investment Company (QIC) has issued an expression of interest for two water infrastructure packages at Qiddiya City, southwest of Riyadh.
According to a source, the first package covers a wastewater treatment plant with a capacity of 60,000 cubic metres a day (cm/d).
The second package involves a wastewater treatment plant with a capacity of 9,000 cm/d. It will also include a “sizeable” reverse osmosis (RO) facility, a source close to the project told MEED.
The deadline for submissions of interest is 8 November.
The infrastructure package will cater to Saudi Arabia’s 360-square-kilometre Qiddiya entertainment city.
QIC, which is owned by Saudi Arabia’s Public Investment Fund (PIF), is overseeing the development of Qiddiya City, including its supporting utilities infrastructure.
In October 2024, MEED reported exclusively that QIC planned to tender its utilities packages individually under an engineering, procurement and construction model.
QIC had previously planned to procure the infrastructure through a public-private partnership (PPP). However, it cancelled this approach despite receiving two bids for a multi-utility package in 2020.
The original utilities package covered power generation, water desalination, sewage treatment and water transmission networks.
In September 2023, QIC signed infrastructure contracts worth SR2.29bn ($611m) with a joint venture of Saudi Real Estate Infrastructure Company (Binyah) and InfraRoad Contracting.
The contracts covered a wider infrastructure package at Qiddiya’s Resort Core, including roads, utility networks, water storage facilities and pumping stations, as well as the construction of a sewage treatment plant (STP).
Two other major PIF-backed developments, the Red Sea project and Amaala, have each awarded multi-utility packages using a PPP model, while contractors are preparing to bid for two separate wastewater treatment plants for Oxagon, Neom’s industrial cluster.
In September, the utilities system serving Saudi Arabia’s Red Sea tourism destination reached commercial operation, marking the start of a 25-year concession for one of the world’s largest integrated off-grid utilities projects.
The project, known as the Marafiq Red Sea Project or Red Sea Utilities Multi-Utilities Project, includes three seawater RO plants, an STP, a waste management centre and 32,500 refrigeration tonnes of district cooling capacity.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21111446/main.jpg -
Riyadh plans multibillion northern roads network overhaul
4 November 2026
Register for MEED’s 14-day trial access
Saudi Arabia’s Royal Commission for Riyadh City (RCRC) is preparing to implement a 189-kilometre (km) programme of road upgrades and extensions in the north of the capital as part of a comprehensive restructuring of the capital’s northern transport infrastructure.
The programme comprises 19 road projects and 33 interchanges serving the airport and 16 surrounding developments, including the Expo 2030 site, Roshn’s Sedra and Plot 1 communities and King Salman Stadium.
Once complete, the upgraded network will have the capacity for 4.2 million daily trips.
Fifteen of the links, totalling 162km, will be funded from the Riyadh City Strategy budget and procured across three waves and five packages.
The remaining four links, covering 27km of roads within and around the airport campus, will be developed by King Salman International Airport (KSIA).
Wave one
Wave one is the most immediate phase, covering seven links totalling 49km around the airport terminals, Expo 2030 and Roshn’s developments.
Fast-tracked for design completion in August 2026, Wave 1 comprises critical primary conduits split across two packages:
Package 1: Covers 11km, comprising an initial 8km stretch of Sheikh Jaber Al-Ahmad Al-Sabah Road and the first extension phase of King Salman Road.
RCRC has already begun implementing the Sheikh Jaber Al-Ahmad Al-Sabah Road scheme, awarding multimillion-dollar contracts for the project this year.
The centrepiece of this wave is the extension of King Salman Road, which will be realigned south along the boundary between KSIA and Roshn.
The new road will have six main lanes and three service-road lanes in each direction, with three full interchanges where Airport Road, a Roshn Sedra link and Sheikh Jaber Road cross it on bridges.
The interchanges will also give separate access to the airport support facilities and terminals, and are each forecast to handle 300,000-400,000 vehicles a day by 2040.
Sheikh Jaber Al-Ahmad Al-Sabah Road will be upgraded along an 8km section and extended by a further 5km. Three grade-separated T-intersections will provide access to Roshn Sedra.
The existing 6km section of King Salman Road will be widened to six main lanes in each direction, with tunnels beneath it at the Prince Saud Bin Jalawi interchange and between Expo 2030 and Roshn Plot 1.
Package 2: Covers 28km of core alignment updates across King Salman Road, the Expo South link, Airport Road, Prince Badr Bin Abdulmohsen Road and Anas Bin Malik Road.
A new 6km road south of the Expo site will extend Prince Saud Bin Jalawi Road through three grade-separated junctions, relieving King Salman Road of Expo and Roshn traffic.
The 8km Airport Road upgrade will add five main lanes and four service-road lanes in each direction, an underpass interchange at Expo Road, a bridge linking Expo with Roshn Sedra and new elevated ramps serving Princess Nourah Bint Abdulrahman University.
Prince Badr Bin Abdulmohsen Bin Abdulaziz Road will be widened from three to four lanes in each direction for 5km, with an underpass to King Salman Stadium.
A tunnel-and-bridge junction will carry it beneath the upgraded 3km Anas Bin Malik Road.
Wave one also includes a main bridge over Riyadh Metro Line 4.
Wave two
Wave two comprises two further packages totalling 72km that extend the network west and south of the airport.
Package 3: Covers 38km and includes the 33km upgrade of Al-Janadriyah Road, the longest single link in the programme, together with the 5km western section of Mohammed Bin Faraj Road. Its design submission is due in November 2026.
Package 4: Covers 34km and comprises the extension of King Salman Road to Al-Janadriyah Road, the 10km upgrade of the Airport Extension Road serving the airport support functions and the 16km upgrade of Prince Saud Bin Abdullah Bin Jalawi Road.
Design is scheduled for submission in March 2027.
Wave three
Wave three is a single 52km package covering the outer northern and eastern corridors. It comprises the 11km upgrade of Al-Thumamah Road, the 17km upgrade of Khuzam Road and the 19km extension of Jabal Azid Road, with design due for submission in August 2027.
Alongside the RCRC-led schemes, KSIA will deliver four links totalling 27km on its own campus. These are the 10km upgrade of the Airport Extension Road adjacent to the terminals, a 6km upgrade of Mohammed Bin Faraj Road, a 5km road to the cargo and aviation services area and a 6km road to the Iconic Terminal.
All three waves are scheduled to reach tender by 2028.
Programme rationale
Designed by Lebanon-headquartered engineering firm Dar Al-Handasah, Taiwan’s Wiecon Consulting Engineers and Germany’s Bodeker, the programme responds to the concentration of Riyadh’s flagship schemes on the city’s northern edge.
Riyadh is planning major developments in the north, with most due for completion by 2030. Daily trips in the area are forecast to rise from about 775,000 today to 1.7 million by 2030 and 3.7 million by 2050.
Roshn’s projects account for 37% of that demand, with Roshn Sedra alone generating more than 520,000 daily trips by 2030.
The sequencing is driven by Riyadh’s event timetable. Wave one targets the links that unlock KSIA’s new terminals, the Expo 2030 site and King Salman Stadium, a venue for the 2034 Fifa World Cup.
The later waves then build capacity for the housing, logistics and mixed-use districts expected to drive traffic growth after 2030, sustaining a pipeline of road contracts in the capital well into the next decade.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21109126/main.jpg