Saudi Arabia under project pressure
28 March 2023

Saudi Arabia’s projects market is overheating. The volume of projects announced in the past six years vastly exceeds the resources that are available to work in the kingdom.
Combined with tight deadlines to complete projects as part of Vision 2030, the pressure on the construction industry to deliver is ratcheting up and turning the tables on the supply chain as the shift from a buyer’s to a seller’s market accelerates.
For the five years from 2016 to 2020, there was an average of about $14bn-worth of contract awards a year in Saudi Arabia for the construction and transport sectors. After rising to $21bn in 2021, the total rose to $32bn in 2022 – the second-best year on record.
The near doubling of the total annual value of contract awards by the end of 2022 has required a significant scale-up of resources in the kingdom, and the ramp-up is set to continue.
Much of this pressure is due to the five official gigaprojects, which are major programmes of work that will involve a sustained flow of contract awards for years to come.
Gigaproject focus
The project most recently classified as a gigaproject by the Saudi authorities is the Diriyah Gate development on the western outskirts of Riyadh. It joins the $500bn Neom development in the northwest of the kingdom, Qiddiya entertainment city outside Riyadh, Red Sea Global’s projects on the Red Sea coast and Roshn’s housing developments across the kingdom.
These projects are relatively new. They began to be launched in 2017 and spent much of the following three years in the design phase.
After a start that was hampered by the work and travel restrictions required to manage the Covid-19 pandemic, construction activity on these projects has accelerated sharply since the start of 2022.
According to regional project tracker MEED Projects, there have been $36bn-worth of contract awards across these official gigaprojects since 2017. Compared to the entire Saudi projects market over the same period that represents 14.5 per cent of contract awards.
The percentage rises to 20 per cent if a more recent time frame is used and only contract awards since the start of 2022 are included. As work gathers pace on the gigaprojects, their significance is expected to grow even further.
 More major projects
Saudi Arabia’s ambitions are not limited to the five gigaprojects. In January, Crown Prince Mohammed bin Salman al-Saud launched the world’s largest modern downtown in Riyadh.
Known as the New Murabba project, it involves the development of 19 square kilometres of land to the northwest of the capital. The centrepiece of the project is the Mukaab, which is a 400-metre-cubed structure with a tower standing inside it.
New Murabba is part of a plan announced in January 2021 to double the size of Riyadh from 7.5 million residents to 15-20 million residents in 2030. Other major projects in the capital include King Salman International airport, King Salman Park, Sports Boulevard and Mohammed bin Salman Non-Profit City.
Beyond the capital there are development projects planned in all major urban centres by Saudi Downtown Company, as well as entertainment centres being developed by Saudi Entertainment Ventures (Seven).
Connecting these cities and projects will be railways, roads, ports and airports that form part of the National Transport & Logistics strategy, which aims to turn the kingdom into a global hub for travel and trade by 2030.
 World’s largest piling project shifts to The Line’s marina
Resourcing challenges
One of the key challenges for the development firms and government agencies responsible for delivering these projects is securing the resources they need.
As client bodies attempt to make their projects more attractive for companies to work on, the industry is changing. The first signs of this change can be seen in the consultancy market.
After years of searching for project opportunities, the big consultancy businesses are now only selectively bidding for projects in the kingdom. This is because their orderbooks are already full, and for many international firms there is a concern that they could become over-exposed to the Saudi market.
On contracts that have already been won there are also challenges. Staffing projects is proving difficult as the kingdom remains a hard sell for many project professionals, despite significant social reforms that have taken place in recent years.
Then, once staff have been recruited and deployed on projects, there is the prospect of losing them to competitors or clients that require the same human resources.

Securing contractors
As activity on site accelerates, the bigger concern is contracting resources. As things stand, there are not enough contractors working in Saudi Arabia to deliver all of the planned projects.
The first way to deal with this problem is to increase the capacity of contractors in the kingdom. In February this year, the Public Investment Fund (PIF) invested $1.3bn in four local construction firms: Al-Bawani Holding Company, Almabani General Contractors Company, El-Seif Engineering Contracting Company and Nesma & Partners Contracting Company.
This investment will allow the companies to scale up their capacity, adopt advanced technologies and improve local supply chains.
As these firms grow, the hope is that it will encourage other local companies to also expand.
International or regional companies can also help, and over the past two years foreign players have become active in the kingdom again. Firms such as Bouygues, Samsung C&T, Hyundai Engineering Construction, China State, Webuild, FCC, Alec, Consolidated Contractors Company and Urbacon Trading Contracting Company have all secured major orders.
In some cases, these contract awards have been supported with foreign finance, which gives the contractor an additional level of comfort when it comes to potential payment for projects. For others, the contract awards reflect growing assurance in the Saudi market.
Boosting appeal
Confidence has been lifted by measures to make the Saudi market more attractive. Payment terms are improving and many of the frustrations typically faced by contractors are being addressed.
One example is the use of performance guarantees. Red Sea Global, which is developing the Red Sea Project and Amaala gigaprojects on the Red Sea coast, no longer requires contractors to submit bid bonds and returns performance bonds on completion of the project, along with half of the retention.
Alternative procurement methods and contract types are also being used, notably early contractor involvement and design and build.
These different approaches reduce risk for the contractor and allow the client to lock in resources at a much earlier stage of the procurement process.
Red Sea Global has adopted a different approach and is self-delivering the bulk of its projects. By acting as its own management contractor, it engages with subcontractors itself. While this means it does not need to secure the services of a main contractor, it still requires engaging with the supply chain, which – like the main contractor market – has finite resources in Saudi Arabia.
Payment terms are improving and many of the frustrations typically faced by contractors are being addressed
Driving efficiency
On the other side of the equation, making construction more efficient could also help to limit the resources required.
Client bodies are exploring modern methods of construction to increase the speed of delivery, reduce costs and cut the amount of resources needed on site.
The market could also be self-limiting. Decision-making in the kingdom remains centralised, which means key project decisions can be slow. While this is changing as development companies are left to run their own projects, bureaucracy can impact the speed of delivery, which ultimately reduces the immediate demand for resources on a project.
While slow decision-making could impact progress on some projects, the overriding story for 2023 will be one of sustained pressure on the kingdom’s construction sector as it becomes a seller’s market.
With that, there is the likelihood that contractor margins will start to creep up, just as they did in the UAE when its construction market overheated in 2003 and 2008.
So far, that does not appear to have happened, as clients in Saudi Arabia have managed to find sufficient resources. For that to remain the case will be a major challenge, however, as on-site activity for most projects in the kingdom is still several years away from peaking.
|
International contractors continue to see a level of risk in the Saudi market “There is a lot of opportunity. A large volume of work is being planned, designed and rolled out. With that, there is significant pressure right now on the market in terms of resources and supply chain. “On the consultancy side, the market is tremendously difficult. “Even with the best incentives and best set of practices, retaining staff is a challenge. People are being attracted elsewhere and the competition is fierce. “For the contractors, there are a lot of tenders being let. The perception that the market has risk remains, however. That is certainly the perception for international contractors, and they are still looking at the Saudi market with some level of risk appreciation in terms of how quickly they are going to be paid and what the margins really are. “That approach will likely prevail for the short to medium term, until clients’ practices change in terms of contractual frameworks and payment practices. “Varied procurement practices are coming into play to guarantee supply chain. It might be early contractor involvement or partnering, but the main purpose is to guarantee the right level of contractors.” |
 Daniel King, director, Currie & Brown
|
To prevent resource shortages, supply chain and procurement must be carefully considered “It is imperative to consider alternative methods of procurement during boom times, and the current boom in Saudi Arabia is unprecedented considering the types, size, nature and complexity of projects that have been announced in line with Vision 2030. “This necessitates giving due consideration to the supply chain and type of procurement. “It is not enough to look for resources locally or even regionally to cope with such projects. One needs to reach out to where such resources are available globally, either due to slowdowns in certain regions or the completion of other major projects. “Cost-plus contracts were used previously in many projects in Saudi Arabia. However, the risk for such contracts rests with the client and sometimes the cost ends up much more than expected. That is why financiers prefer the lump-sum type of contracts. “Nonetheless, I can see this type of contract being used for fast-track projects with very tight schedules, for instance to meet deadlines for facilities required for international or regional sporting events. “In any case, the evaluation and selection of contractors needs to be done with extreme diligence.” |
 Adel Karem Jemah, senior vice-president, Hill International
MEED's April 2023 special report on Saudi Arabia includes:
> ECONOMY: Riyadh steps up the Vision 2030 tempo
> CONSTRUCTION: Saudi construction project ramp-up accelerates
> UPSTREAM: Aramco slated to escalate upstream spending
> DOWNSTREAM: Petchems ambitions define Saudi downstream
> POWER: Saudi Arabia reinvigorates power sector
> WATER: Saudi water begins next growth phase
> BANKING: Saudi banks bid to keep ahead of the pack


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 US DFC approves $1.8bn financing for Jordan National Water Carrier
24 September 2026
-
 Hitachi wins Al-Mashaer Al-Muqadasah metro revamp
24 September 2026
-
 Contractor wins 6GW data centre campus infrastructure
24 September 2026
-
 Algeria officially launches major phosphate project
24 September 2026
-
 Design review nearly complete for Libya upstream project
24 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
US DFC approves $1.8bn financing for Jordan National Water Carrier
24 September 2026
The US International Development Finance Corporation (DFC) has approved a loan of up to $1bn and political-risk insurance of up to $800m for Jordan’s National Water Carrier Project.
The $1bn loan will be provided to National Carrier Project Company (NCPC) to finance the design, development, construction, operation and maintenance of the project’s seawater desalination plant, water conveyance system and dedicated solar generation plant.
The $800m of political-risk insurance will be provided to Paris-based investment and utility firms Meridiam and Suez, which are developing the project.
The National Water Carrier, also known as the Aqaba-Amman Water Desalination and Conveyance Project, is being developed under a public-private partnership between Jordan’s Ministry of Water & Irrigation and NCPC, a special-purpose vehicle owned by Meridiam (90%) and Suez (10%).
The project involves the design, development, construction, operation and maintenance of a seawater desalination plant, a water transmission system and dedicated renewable power generation facilities under a build-operate-transfer model.
Jordan signed the project’s final technical and legal agreement with Meridiam in April, following months of negotiations.
The project’s capital cost was put at about $4.3bn, with total costs including financing estimated at $5.8bn.
Financial close has not yet been completed. The project’s technical director said in July that the final agreements required for financial close were still being prepared, with construction expected to start in the fourth quarter of 2026. Water pumping is scheduled to begin in the fourth quarter of 2030.
Jordan’s cabinet approved a $97m financing agreement with the French Development Agency in July as the government continued to complete the project’s financing arrangements.
The cabinet also approved a package of facilities and exemptions for the National Water Carrier Project on 17 September to help finalise start-up procedures for the project in the Aqaba Special Economic Zone.
Jordan’s water needs
The Aqaba-Amman water desalination and conveyance project will desalinate 300 million cubic metres of seawater annually. It will also include a 450-kilometre pipeline and pumping systems reaching elevations of up to 1,100 metres.
The project is intended to help address Jordan’s severe water scarcity. As one of the world’s most water-stressed countries, Jordan consumes nearly 1 billion cubic metres of water a year.
The domestic sector consumes approximately 50% of this, with only 61 cubic metres of water available per person a year, far below the global absolute water scarcity level of 500 cubic metres of water per capita.
According to the government, the scheme will increase overall water supply by 40%, with per capita availability expected to rise to 110 cubic metres annually.
Annual output from the Water Carrier Project will be nearly equivalent to the total storage capacity of all dams in the kingdom and almost three times the output of the Disi Water Project.
The project is expected to supply about 40% of Jordan’s drinking water needs, with operations scheduled to begin in 2030. It will also include a 280MW solar photovoltaic plant in Al-Quweira covering roughly 30% of the project’s energy needs.
Financing
The government previously said the project had secured about $663m in grants from international partners, including the US, the European Union, Germany, the Netherlands, the UK, France, Italy, Japan and the Green Climate Fund.
The Jordanian government is contributing $722m.
Meridiam is arranging about $2.9bn in private sector financing from international financial institutions. The financing package includes support from institutions including the World Bank Group, European Investment Bank, European Bank for Reconstruction & Development, Islamic Development Bank, Proparco, Japan International Cooperation Agency and the Opec Fund for International Development.
A consortium of Jordanian banks led by Housing Bank is providing up to $1.1bn in local financing, with the Social Security Investment Fund also taking an equity stake alongside Meridiam.
Local manufacturing
The project is also beginning to generate associated industrial investment.
On 30 August, Jordan’s cabinet approved the establishment of a steel pipe manufacturing and coating plant in Aqaba with investment of up to JD120m ($169m). The plant is expected to allocate 50% of its production to the National Water Carrier and create about 420 jobs. Its output will also be available for future water, gas transmission and pumping projects.
The Aqaba Special Economic Zone Authority and the Ministry of Water & Irrigation also launched a dedicated single-window platform in August to streamline licensing and permitting for the National Water Carrier project.
Once operational, the project is expected to remain under the PPP structure for 26 years before ownership transfers to the Jordanian government.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19943001/main.jpg -
Hitachi wins Al-Mashaer Al-Muqadasah metro revamp
24 September 2026
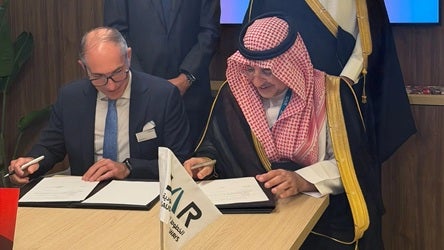
Saudi Arabia Railways (SAR) has signed a contract with Japan’s Hitachi Rail to revamp the Al-Mashaer Al-Muqadasah metro project in Mecca.
The 18-kilometre line includes nine stations and has a design capacity of about 72,000 passengers an hour in each direction.
The scope includes upgrades to improve reliability, operational performance and long-term maintainability.
SAR chief executive Bashar Al-Malik and Hitachi Rail’s Middle East and Africa signalling and rail solutions vice-president, Carlo Piacenza, signed the contract.
The rail line operates during the Hajj period and transports pilgrims between Mina, Muzdalifah and Arafat.
It was developed to reduce reliance on buses, ease congestion on pilgrimage routes, and improve safety and crowd management during Hajj.
The Saudi authorities procured the project on a fast-track basis to meet a fixed operational deadline for Hajj. It entered initial operation in 2010, with China Railway Construction Corporation acting as the main contractor for civil works and overall delivery.
Hitachi Rail supplied key rail systems, including signalling and telecommunications. SAR subsequently assumed responsibility for the asset and has led later improvement and upgrade programmes.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19941437/main.jpg -
Contractor wins 6GW data centre campus infrastructure
24 September 2026
Dammam-based construction firm Alyamama Company has won a contract to develop infrastructure for a planned 6GW hyperscale artificial intelligence (AI) data centre campus in Riyadh.
The project will be delivered on an early contractor involvement (ECI) basis. Under the ECI process, selected contractors are required to submit methodologies and design proposals, after which one team will be selected to deliver the construction works.
Saudi Arabia’s AI company Humain, owned by the Public Investment Fund (PIF), tendered the contract in May, as MEED reported.
The scope of infrastructure work covers:
- Construction of 380kV/132kV/33kV electrical distribution network, two substations with a capacity of 500MVA and 200MVA, bulk supply point (2,000MVA)
- Water network and fire protection systems
- Sewage treatment plant and wastewater network
- Stormwater systems
- Roads
- Underground cable and fibre optic networks
- Landscaping works
The client is being supported by Canadian engineering firm Hatch, France’s Egis and US-based firm JLL.
The development will be built on a 24-square-kilometre site in the Al-Saad area in east Riyadh. It will be delivered in two phases across six plots, each with a capacity of 1GW.
Humain was launched in May last year to operate and invest across the AI value chain.
Humain is building full-stack AI capabilities across four core areas: next-generation data centres, hyper-performance infrastructure and cloud platforms, and advanced AI models, including Allam.
Also in May 2025, Humain signed preliminary deals with US chipmakers AMD and Nvidia to build multibillion-dollar advanced digital infrastructure in the kingdom.
AMD said it will invest up to $10bn to deploy 500MW of AI compute capacity in Saudi Arabia over the next five years.
In October 2025, PIF and Saudi Aramco signed a non-binding term sheet setting out key terms under which Aramco would acquire a minority stake in Humain, with PIF retaining majority ownership.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19940798/main.jpg -
Algeria officially launches major phosphate project
24 September 2026
Algeria’s Minister of State and Minister of Hydrocarbons, Mohamed Arkab, has officially launched the construction of the country’s Integrated Phosphate Project (IPP) during a visit to the province of Annaba.
This major phosphate project spans the provinces of Annaba, Souk Ahras, Tebessa and Bir El-Ater.
The scope of the IPP includes:
- A raw phosphate extraction and beneficiation complex at the Bled El-Hadba site (Bir El-Ater): designed for 5.5 million tonnes a year (t/y) of ore extraction and 3.2 million t/y of phosphate concentrate production
- An industrial complex at the Oued Keberit site: to include several production units, with the capacity to produce 2.4 million t/y of phosphate fertilisers as well as 570,000 t/y of nitrogen fertilisers
- Port facilities at the port of Annaba: for exporting surplus fertiliser production
- Utilities and auxiliary infrastructure
In a statement, the Ministry of Hydrocarbons said that Arkab’s official visit was taking place “within the framework of periodic field monitoring of the project’s implementation stages”.
It said: “The project stands as one of the most significant strategic and structural initiatives for the national economy; it aims to develop and exploit national mineral resources and to process and add value to phosphate locally, thereby boosting value-added output and increasing non-hydrocarbon exports.”
It added: “The integrated phosphate project is part of a comprehensive vision to valorise national mineral resources and develop associated downstream industries.
“This initiative aims to boost national production of fertilisers and high-value-added chemical products, support food security, create jobs, and contribute to diversifying the national economy and increasing non-hydrocarbon exports.”
On 12 August, Algeria’s national oil and gas company Sonatrach and the Algerian Chinese Fertilisers Company (ACFC) signed two engineering, procurement and construction (EPC) contracts for the project.
The contracts were part of the Bled El-Hadba phosphate development project, which is expected to be worth $7bn.
The contracts were signed by Italy’s Saipem and China Harbour Engineering Company (CHEC) as part of the first phase of the integrated phosphate project.
Saipem’s contract was worth about €500m ($577m), according to a statement from the Italian company.
It focuses on constructing fertiliser processing and production facilities.
The contract with CHEC focuses on constructing port facilities at the Port of Annaba.
ACFC was created in March 2022 by Algerian companies Asmidal and Manadjim El-Djazair (Manal), which own 56% of the company, and Chinese groups Wuhuan and Tianan, which own the remaining 44% stake.
Manal and Asmidal are both subsidiaries of Sonatrach.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19927744/main.jpg -
Design review nearly complete for Libya upstream project
24 September 2026
US-headquartered KBR is nearing completion of its re-evaluation of the design for the project to develop the J6 North Gialo field in Libya, according to industry sources.
In June, MEED reported that Libya’s Waha Oil Company (WOC), a subsidiary of state-owned National Oil Corporation (NOC), had launched a review into the tender process for the J6 North Gialo oil field development project, and that this would include re-evaluating the front-end engineering and design (feed).
The Waha concessions are held by a consortium of Libya’s NOC (59.16%), TotalEnergies (20.42%) and US-based ConocoPhillips (20.42%).
They are operated by WOC, which is 100% owned by NOC.
WOC is planning to tender the main contract for the project to develop the J6 field before the end of this year, although it may be tendered in the first quarter of 2027 if there are delays.
KBR in Libya
KBR has previously provided engineering services for major national projects in Libya, such as the Great Man-Made River project, which is widely recognised as the largest irrigation project in the world.
In March, KBR was awarded a contract by Zallaf Exploration, Production & Refining of Oil & Gas Company to provide project management and technical services for the South Refinery project in Libya’s southern city of Ubari.
Under the terms of the contract, KBR will provide contract management, project management and supporting technical services throughout the engineering, procurement and construction (EPC) phases of the project.
The EPC work is expected to be executed over a 50-month period.
In its statement, KBR said the project aligns with its “long-standing commitment to advancing vital oil and gas infrastructure in Libya”.
Upstream development
In March, MEED reported that South Korea’s Daewoo had pulled out of the tender process for Libya’s J6 North Gialo oil field development project.
Daewoo had formed a partnership with Egypt’s Petrojet to participate in the tender process.
The only other company to submit a bid for the project was UK-based Petrofac, which filed for administration in October last year.
In January, TotalEnergies signed an agreement extending the Waha concessions agreement up to 31 December 2050.
This agreement set new fiscal terms, allowing an increase in the production of these concessions that were, at the time, producing about 370,000 barrels of oil equivalent a day (boe/d).
In January, TotalEnergies said that the deal paved the way for “a new phase of investments, including the development of the North Gialo field, which is expected to add 100,000 boe/d of production”.
The J6 North Gialo project is the first of three field development projects that WOC has prioritised.
The other two are known as NC98 and Gialo 3.
Together, the three projects are expected to double Waha’s production from about 300,000 barrels a day (b/d) of oil to 600,000 b/d.
The Waha concession covers 13 million acres.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19927052/main.jpg