What foreign companies still get wrong about Iraq
5 August 2026

Improved security, political stability and stronger oil revenues have brought Iraq back into investor conversations in recent years. Higher oil prices restored state finances, revived public spending and reinforced the narrative that Iraq was once again open for business. Relative calm strengthened that sentiment among regional and international firms.
Yet Iraq’s investment narrative has improved faster than its operating reality. A common mistake among foreign investors has been to view operations in Iraq primarily through the lens of security. While physical security remains important – particularly in the current regional climate – some of the most persistent risks are structural. These include opaque counterparties with hidden political backing, fragmented authority and overlapping power centres, exposure to sanctions-linked networks, and weak and often corrupt law enforcement and judicial institutions.
For most firms, the real test begins after market entry: when choosing a partner, bidding for contracts, moving funds, securing government approvals or attempting to enforce a contract or court judgment.
The current conflict has not changed these risks; rather, it has made them harder to ignore.
Basic due diligence and document checks are often insufficient to mitigate risks in a market as complex as Iraq
Counterparty risks and how to mitigate them
For many foreign investors operating in Iraq, one of the most significant risks lies in dealing with local counterparties – business partners, contractors, suppliers, clients and customers. Companies may appear conventional on paper, but ownership and control are often obscured through proxies.
One challenge is identifying who ultimately controls or benefits from a business and whether it has links to politically exposed persons, armed groups or sanctioned networks. Another is examining its business practices for signs of corruption or other illicit activity.
Every so often, we encounter seemingly well-established and reputable Iraqi business groups with extensive foreign partnerships that, following in-depth investigation, appear to be ultimately controlled by or linked to politicians, militia leaders, sanctioned individuals or Iran-aligned armed groups. Such connections often indicate a history of corrupt practices, ranging from bribery and the use of high-placed connections to secure government contracts to involvement in sophisticated money-laundering schemes or smuggling and diversion operations benefiting the Iranian state.
Foreign firms engaging with local counterparties may enter what appears to be a routine commercial arrangement, only to discover later that they are doing business with a highly sensitive or controversial political actor. The consequences extend beyond commercial risk. Regulatory, legal and reputational repercussions can follow, particularly where sanctions or criminal exposure exists.
Basic due diligence and document checks are often insufficient to mitigate risks in a market as complex as Iraq. Obtaining a deeper understanding of a potential counterparty’s ownership, control and track record is often constrained by the limited availability of credible information.
One of Iraq’s paradoxes is that it is not a data-poor jurisdiction. It generates abundant media reporting, leaks and social-media narratives. The challenge lies in judging what information matters, who is driving it, and what is missing.
The government also maintains a publicly accessible corporate register – Tasjeel – which contains basic information on the ownership of Iraq-registered private companies. The details, however, can be incomplete or out of date, and names on official filings often do not reflect actual control. There is also a notable lack of transparency when it comes to legal searches in Iraq: neither criminal nor civil litigation records are publicly available.
The availability of information also varies across the country. Iraq is not a single commercial jurisdiction. In practice, overlapping and sometimes competing systems of authority exist, particularly between federal Iraq and the Kurdistan Region. Licensing, customs procedures, taxation, political sponsorship and legal recourse can differ significantly, as can the accessibility of official records, with the Kurdistan Region generally offering less transparency.
For all these reasons, source-based enquiries remain central to any serious risk assessment in Iraq. Human intelligence gathered on the ground through a network of knowledgeable sources often fills critical information gaps, providing context and insights that cannot be obtained from public records alone.
The impact of regional war and political changes on structural weaknesses
The recent deterioration in the regional security environment has renewed attention on Iraq. Investors are once again weighing insurance costs, movement restrictions, supply-chain exposure and the risk of disruption from armed escalation.
The implications, however, extend well beyond immediate security concerns. Regional conflict often strengthens informal power structures, elevates the influence of armed factions, increases exposure to pro-Iran networks and complicates sanctions assessments. Institutions may slow decision‑making, while border friction, diversion risk and financial scrutiny intensify.
As a result, the risk categories familiar to foreign investors – political, compliance, legal and operational – often become intertwined in Iraq. A politically exposed counterparty can become a sanctions issue; a regulatory delay can turn political; and a commercial dispute may prove unenforceable where the other party operates within a stronger network of influence.
There is also a new variable in play. Iraq’s new prime minister, Ali Al-Zaidi, is a seasoned businessman with significant interests in banking, the food industry and other sectors. For foreign investors, this background may be viewed as a positive signal, suggesting a greater emphasis on deal-making, investor outreach and easing market entry. However, a businessman at the top can help only up to a point. Iraq’s core business risks are rooted in institutions, networks and entrenched political structures that even a pro‑business leader must navigate.
Counterparty risk assessment should sit at the centre of any market-entry strategy
What serious investors should do differently
None of this means Iraq should be written off. It remains a market with scale, unmet demand and clear areas of opportunity. But it does mean foreign companies need a more disciplined approach.
Counterparty risk assessment should sit at the centre of any market-entry strategy. That means identifying beneficial ownership, mapping political exposure, screening for sanctions links and understanding the broader network surrounding a local counterparty rather than relying solely on a basic corporate registry check.
Iraq should also be treated as a market that requires continuous monitoring, not one-off screening. Ownership, influence and compliance exposure can change quickly. A clean partner at onboarding is not guaranteed to remain a low risk a year later.
About the authors
Dr Anastasia Nosova is associate managing director at K2 Integrity, a prominent global risk advisory, compliance and corporate investigations firm. Renwar Ahmed is an associate at the company’s Investigations & Disputes practice.
MEED’s June 2026 report on Iraq includes:
> COMMENT: Iraq’s reform window narrows
> GOVERNMENT: Al-Zaidi takes Iraq’s premiership under US shadow
> BANKING: Financial challenge tests Iraq’s resolve
> ECONOMY: Iraq enters era of resilience, reform and rising risks
> OIL & GAS: Iraqi oil and gas sector in crisis
> POWER & WATER: Focus shifts to delivery of Iraq utilities expansion
> CONSTRUCTION: Momentum builds in Iraq’s post-war construction sector

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Oxagon takes centre stage at Neom
29 September 2026
-
 Contractors submit bids for Oxagon Highway 55 upgrade
29 September 2026
-
 Contractors express interest in sixth Jafurah expansion phase
29 September 2026
-
 Delivery unlocks gigaproject investment
29 September 2026
-
 Giga developers absorb supply chain shocks
29 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
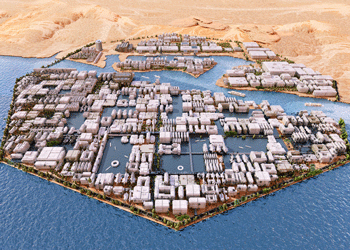
Oxagon takes centre stage at Neom
29 September 2026
For all the talk of cancellations, Neom completed its biggest project yet in August, commissioning the $8.5bn Neom Green Hydrogen project.
The project reflects Neom’s reprioritisation, which has seen the $500bn gigaproject shift from a speculative vision towards a delivery-focused industrial development.
This shift was clearly signalled in April, when Public Investment Fund (PIF) governor Yasir Al-Rumayyan publicly backed Oxagon, Neom’s planned industrial and manufacturing hub on the Red Sea coast. Since then, there have been increasing signs that the development is taking precedence over the rest of the giga-portfolio.
Announced strategy
 Al-Rumayyan’s remarks, delivered as PIF unveiled its 2026-30 strategy, were the clearest public articulation yet of where the fund’s priorities lie. Asked whether The Line needed to be delivered, he was blunt: it would be good to have, but it was not essential.
Oxagon, on the other hand, was described as “the fundamental part of Neom”.
The comment reframed two years of speculation about scaled-back ambitions at Neom into something closer to a strategic decision, with capital following the assets capable of generating revenue, and the industrial city sitting at the top of that list.
The shift in language also matters, since PIF has been at pains to stress that no Neom projects have been formally cancelled, even as billions of dollars of contracts have been terminated or re-scoped over the past two years.
Under the new strategy, Neom has effectively been reclassified as its own reporting line within PIF’s portfolio, separated from the fund’s other domestic holdings. That separation gives Oxagon room to be judged on its own commercial merits, while distancing it from the reputational weight still carried by more conceptual elements of the wider development.
There have been increasing signs that Oxagon is taking precedence over the rest of the giga-portfolio
Conflict acceleration
The reprioritisation was already under way before the region’s latest conflict began. PIF has spent the past two years pushing Neom to identify which elements of the gigaproject were fundamental and which were aspirational, a process that has as much to do with capital discipline as geopolitics.
With the fund committing to direct roughly 80% of its $925bn portfolio towards domestic investment, while simultaneously funding Expo 2030 and the 2034 World Cup, Riyadh needed its flagship projects to start showing commercial returns rather than absorbing capital indefinitely.
Oxagon, with a port, an export-ready hydrogen plant and land that could be leased to industrial tenants, was always the part of Neom best placed to answer that requirement, and the regional conflict that began in late February only accelerated the shift. The closure of the Strait of Hormuz to a fraction of its normal commercial throughput has hit Saudi Arabia’s oil export capacity hard and pushed the kingdom into a sizeable quarterly fiscal deficit.
Riyadh has also had to contend with direct disruption to its own energy infrastructure, including the temporary closure of the East-West oil pipeline following drone strikes. Against that backdrop, an industrial city with its own deep-water port on the Red Sea, outside the Strait of Hormuz chokepoint, has taken on added strategic weight.
Oxagon offers the kingdom a second maritime gateway, one that is not exposed to the same geopolitical risks as the Gulf coast terminals that have historically carried Saudi trade. For a government having to defend every riyal of committed capital spending, a project that can plausibly generate port fees, hydrogen export revenue and data-centre hosting income within the current decade is a far easier sell than a 170-kilometre linear city that is still taking shape.
Construction ramps up
The clearest evidence of that pivot is what has actually broken ground at Oxagon recently. At a time when Neom’s recent news flow has been about contract terminations, Oxagon’s has been about starts.
The most visible of these is the artificial intelligence (AI) data-centre campus being developed by Humain, the PIF-owned AI company, in partnership with digital infrastructure developer DataVolt.
Construction on the first 100MW of a planned 360MW first phase began this year, as part of a wider 1.5GW campus that builds on the companies’ original 2025 agreement, backed by roughly $5bn of investment. The facility is designed to draw on Oxagon’s pre-zoned industrial land, renewable power and subsea cable links to Europe and Africa, with the first 100MW targeted for service in 2028.
For Neom, the project answers a question that has dogged the gigaproject for years: namely, what, beyond real estate and tourism, Oxagon actually sells.
Connectivity is following the same pattern. Neom issued an expression of interest in September for consultancy services to plan a freight rail line of more than 400km linking the Port of Neom at Oxagon to Saudi Arabia Railways’ North-South Railway at the Al-Baseeta junction.
The North-South network currently serves the kingdom’s phosphate and bauxite mining sector, running from Al-Jalamid and Baitha to the Gulf coast industrial cluster around Ras Al-Khair, Jubail and Dammam, with branches to Riyadh and the Jordanian border.
A connection to Oxagon would give that network a second maritime outlet on the Red Sea and would finally give the Port of Neom a direct rail link into the kingdom’s interior, something it has lacked since operations began in 2022.
Cargo currently depends on road transport or an additional sea leg, a constraint that has limited the port’s usefulness beyond a regional hub.
Utilities work is quietly keeping pace with the more visible projects. Neom has tendered an industrial wastewater treatment plant at Oxagon, with proposals due in early October. The scheme has an initial capacity of 35,000 cubic metres a day, (cm/d) expandable to a maximum of 45,000 cm/d as demand grows.
The plant is expected to cater to the wider industrial developments planned at Oxagon and points towards it developing into a full-fledged industrial cluster rather than a single-phase development.
Road infrastructure has moved in parallel. A design-and-build tender is currently out for the permanent upgrade of Oxagon’s Highway 55, which connects the Red Sea coast with the mainland in northwestern Saudi Arabia.
It currently serves as the only road providing north-south connectivity between Duba and the Neom region. The project is expected to support the anticipated increase in construction activity at Oxagon and facilitate the movement of cargo vehicles from Duba Port to other parts of the country and the wider region.
These construction packages represent the unglamorous groundwork needed before an industrial city can function at scale, and that foundational build-out is already being mirrored in Neom’s external connectivity. In April, a new multimodal logistics corridor linking Europe, Egypt, Neom and the GCC was enabled, offering a faster and more flexible route for European cargo entering the region.
The most advanced element of the build-out remains the port itself. Dutch marine contractor Boskalis has completed the deepening and widening of the main access channel, and Belgian contractor Besix has finished more than 4.6km of quay wall across seven berths, some with draughts of up to 18.5 metres.
The Terminal 1 development, a 900-metre, fully automated container facility designed to be one of the first ports in the kingdom to use automated ship-to-shore cranes, is being phased in through 2026. This will take capacity from the port’s current 250,000 twenty-foot equivalent units (TEUs) towards a 2030 target of 1.5 million TEUs, and an eventual ambition of 12 million TEUs once fully built out. The facility has been described as an accelerator for the kind of integrated, end-to-end supply chain the wider Oxagon concept was built around.
A development this capital-intensive will require continued private and foreign investment
Project rationale
Set against the rest of Neom’s portfolio, Oxagon’s advantage stands out. It has the potential to produce things that can be sold, shipped or leased within a timeframe investors and government auditors can underwrite.
Green hydrogen converted into green ammonia for export; port capacity sold by the container; data-centre capacity sold by the megawatt; industrial land leased by the hectare. These are conventional infrastructure economics, not the largely unprecedented urban-planning bet represented by The Line or other components of the wider Neom masterplan.
There is also a coherence to Oxagon’s individual pieces that is harder to find elsewhere in the Neom story. A port needs rail and road connections to move cargo inland. An AI data-centre campus needs power, land and subsea connectivity – things an industrial port city is well placed to provide. A green hydrogen plant needs an export terminal close by. Each project reinforces the case for the others, in a way that an industrial city announced in 2021 as one vision among several has arguably never quite managed to replicate.
Oxagon is not without risk. Schedules have already slipped once, and a development this capital-intensive will require continued private and foreign investment if its backers are serious about reducing direct funding exposure.
The direction of travel this year has been positive. With the green hydrogen plant entering commissioning, a hyperscale AI campus breaking ground, a new rail corridor being planned and a port moving towards its next phase, Oxagon is reinforcing its position as one of the kingdom’s flagship projects for the future.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20095152/main.gif -
Contractors submit bids for Oxagon Highway 55 upgrade
29 September 2026
Contractors submitted bids on 28 September for a design-and-build contract to upgrade Highway 55 in Saudi Arabia’s Oxagon region.
The first phase of the project includes the construction of 14 kilometres of road with two lanes in each direction, as well as one bridge and three interchanges.
The project duration is 22 months.
Highway 55 connects the Red Sea coast with the mainland in northwestern Saudi Arabia. It is currently the only road providing north-south connectivity between Duba and the Neom region.
MEED reported exclusively in August last year that contractors had submitted responses to an expression of interest notice that Neom issued earlier that month.
The project is expected to support cargo movement from Duba Port to other parts of the kingdom and the wider region.
Last year, Neom tested a pilot initiative by handling a shipment that travelled from Cairo via the Port of Safaga, across the Red Sea to the Port of Neom, and then inland to Erbil, Iraq.
In a statement, Neom said: “The shipment travelled through an intermodal corridor spanning over 900 kilometres, marking a significant milestone in the kingdom’s transformation into a regional and global logistics hub.”
The Port of Neom is located on the Red Sea near the Arar border, a key entry point into Iraq.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20093715/main.jpg -
Contractors express interest in sixth Jafurah expansion phase
29 September 2026
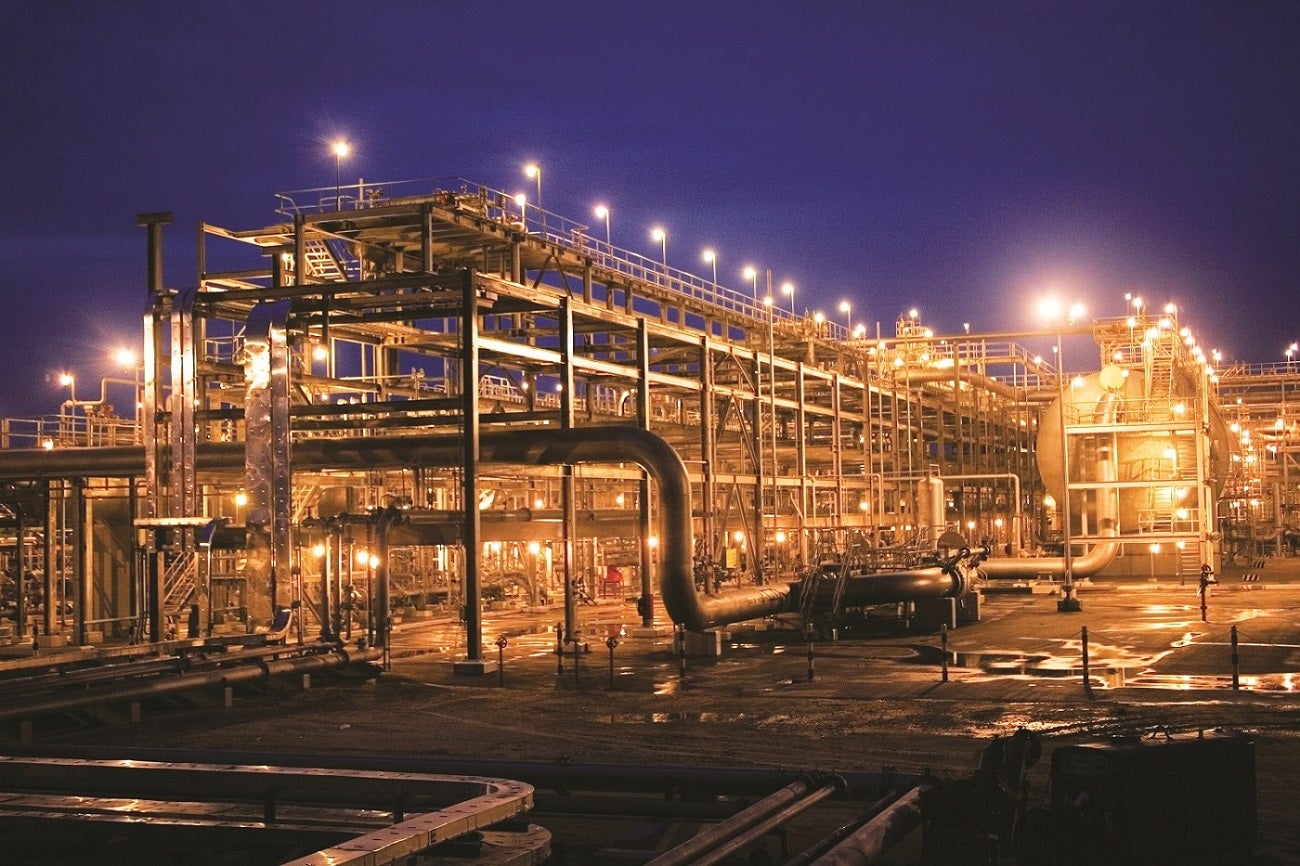
Contractors have expressed interest to Saudi Aramco in the next major expansion phase of the Jafurah unconventional gas development programme in Saudi Arabia.
According to sources, the main scope of work for the sixth expansion phase of Jafurah involves the engineering, procurement and construction (EPC) of three gas compression plants at the gas basin in the kingdom’s Eastern Province. Each plant will be capable of processing up to 200 million cubic feet a day (cf/d).
Aramco is said to have issued a solicitation of interest for the project in August, with contractors submitting responses within the same month, sources told MEED.
The Jafurah basin is the largest liquid-rich shale gas play in the Middle East, spanning about 17,000 square kilometres. The reserve is estimated to contain 229 trillion cubic feet of gas and 75 billion stock-tank barrels of condensate.
In December last year, Aramco brought the greenfield Jafurah gas processing plant online, with a production capacity of 450 million cf/d, marking the commissioning of the first phase of its $100bn capital expenditure programme to produce gas from the unconventional resource base.
The company had previously stated it expected to start gas production at Jafurah in 2025, with the intention of progressively ramping up to 2 billion cf/d of sales gas, 420 million cf/d of ethane and 630,000 barrels a day (b/d) of high-value liquids by 2030.
Aramco has said that its unconventional gas programme, at peak production, is expected to generate electricity equivalent to displacing 500,000 b/d of oil.
In February 2020, Aramco received a capital expenditure grant of $110bn from the Saudi government for the long-term phased development of the Jafurah unconventional gas resource base. Since then, the Saudi energy giant has moved at pace and scale through subsequent expansion phases of the Jafurah unconventional gas development programme.
Jafurah gas development phases
As Aramco prepares to issue the main EPC tender for the Jafurah sixth expansion phase, it is also at an advanced bid evaluation stage for the programme’s fifth phase.
MEED reported in August that China Petroleum Engineering & Construction Company (CPECC) had emerged as a frontrunner to win the main contract for the Jafurah fifth expansion phase, based on Aramco’s initial evaluation of proposals.
The main scope of work for the fifth expansion phase also involves the EPC of three gas compression plants at the Jafurah gas basin, with each plant having a gas processing capacity of 200 million cf/d.
Aramco had set 19 July as the final deadline for proposals, and contractors submitted their bids by that date, MEED previously reported.
The Saudi energy giant is understood to have issued the main EPC tender for the project in the first quarter of this year.
Aramco issued a solicitation of interest for the Jafurah fifth expansion phase in mid-November, with contractors submitting responses by 30 November, MEED previously reported.
UK-headquartered Wood Group has carried out the front-end engineering and design for the project.
ALSO READ: Aramco moves apace with Jafurah unconventional gas campaign
Along with evaluating bids for EPC works on the fifth expansion phase project at Jafurah, Aramco has also recently kicked off EPC works on the fourth expansion phase.
MEED reported in April that Aramco had selected Indian contractor Larsen & Toubro Energy Hydrocarbon (L&TEH) as the main contractor for the fourth phase, which sources estimate could be valued at about $1.5bn.
The main scope of work on Jafurah’s fourth expansion phase involves the EPC of two gas compression trains at the gas basin. Each plant will process up to 200 million cf/d.
Aramco has issued only a draft letter of award for the project to L&TEH; however, based on this, the contractor has started EPC works. The official contract award and final investment decision are pending, according to sources.
EPC work on the third phase of the Jafurah unconventional gas development programme is also advancing.
In July 2024, Aramco issued a non-binding letter of intent to a consortium of Tecnicas Reunidas and Sinopec Group for the EPC contract for phase three. The value of the contract is estimated at $2.24bn.
The objective of the third expansion phase is similar to that of the fourth phase. The main scope of work involves the EPC of three gas compression plants, each with a capacity of 200 million cf/d.
The third phase scope of work also includes building a 230kV substation to power the new gas compression plants, and installing other utility units, piping systems and safety equipment.
The selection of contractors for the third expansion phase came within weeks of Aramco officially awarding EPC contracts for the second phase, which aims to raise the field’s processing potential to up to 2 billion cf/d of raw gas.
Aramco awarded 16 contracts, worth a combined total of about $12.4bn, for the second expansion phase on 30 June 2024.
The EPC scope of work on that project involves the construction of gas compression facilities and associated pipelines, and the expansion of the Jafurah gas plant, including the construction of gas processing trains, utilities, sulphur and export facilities, Aramco said in a statement.
The main EPC packages of the Jafurah second expansion phase project, their estimated values and the selected contractors are:
- Package 1 – gas processing plant and main process units – $2.9bn: Larsen & Toubro Energy Hydrocarbon (India)
- Package 2 – utilities and offsites – $2.4bn: Hyundai Engineering (South Korea)
- Package 3 – gas compression units – $1bn: Larsen & Toubro Energy Hydrocarbon
- Riyas natural gas liquids (NGL) package 1 – NGL fractionation trains – $1bn: Tecnicas Reunidas / Refining & Chemical Engineering Group (part of China’s Sinopec Group)
- Riyas NGL package 2 – utilities, storage and export facilities – $2.2bn: Tecnicas Reunidas/Refining & Chemical Engineering Group
- Riyas NGL package 6 – site preparation works – $107m: Mofarreh Alharbi & Partners (Saudi Arabia)
- Riyas NGL package 9 – temporary construction facilities – $80m: Mofarreh Alharbi & Partners
Aramco kickstarted EPC works on the first phase of the programme in November 2021 by awarding $10bn-worth of subsurface and EPC contracts.
The Jafurah programme is central to Aramco’s goal of increasing gas production capacity. The target has recently been raised to 80%, with 2021 as the baseline, up from 60%, to meet rising domestic and global demand. The company expects life-cycle investment in Jafurah to exceed $100bn.
Aramco completed an $11bn lease-and-leaseback deal in late October 2025 for gas processing facilities at the Jafurah unconventional gas reserve with a consortium led by funds managed by Global Infrastructure Partners (GIP), part of US asset manager BlackRock.
Under the transaction, a newly formed subsidiary, Jafurah Midstream Gas Company (JMGC), will lease development and usage rights to the Jafurah field gas processing plant and the Riyas natural gas liquids fractionation facility.
After 20 years, JMGC will lease the assets back to Aramco. JMGC will collect a tariff payable by Aramco in exchange for granting Aramco the exclusive right to receive, process and treat raw gas from the Jafurah resource base.
Aramco will hold a 51% majority stake in JMGC, while the GIP-led consortium will hold the remaining 49%. Investors participating in the GIP-led consortium include Hassana Investment Company, the Arab Energy Fund and Aberdeen Investcorp Infrastructure Partners, as well as other institutional investors from North and Southeast Asia and the Middle East.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20090894/main5646.jpg -
Delivery unlocks gigaproject investment
29 September 2026
Register for MEED’s 14-day trial access
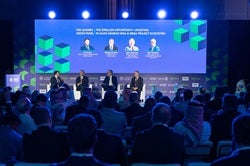
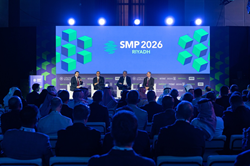
Completed infrastructure and open assets are making it easier to attract private developers and foreign investors to Saudi Arabia’s gigaprojects, said speakers at MEED’s Shaping Mega Projects conference in Riyadh on 28 September.
Dale Chadwick, acting CEO of King Salman Park Foundation, said investor appetite had grown as construction advanced. The foundation has received 23 expressions of interest from private developers, and Chadwick said that number was increasing.
“What the private sector is looking for in terms of investment is surety of what we’re doing,” he said. “As soon as a private developer comes in and sees what we’re doing, they’re blown away. The closer we get to completion, the greater the appetite.”
He said interest from foreign direct investors was also rising, and that a deal the foundation expects to award soon involves foreign investment.
The foundation times its private asset awards to follow infrastructure and landscaping works. “They don’t have to take the leap of faith that we are going to execute on our side of the equation,” said Chadwick. “They can see it.”
Partnership model
Mohamed Saad, president of DevCo at Diriyah Company, said investors wanted a relationship rather than a transaction.
“The first thing they’re looking for is partners,” he said. "They’re looking for master developers who act as true partners to them.”
Saad said master developers acted as the catalyst, investing in infrastructure and anchor assets before the private sector joins. He said investors also wanted healthy supply and demand, and a market able to absorb commercial assets in phases.
He said Diriyah had prioritised delivery over publicity. “People want to see to believe,” said Saad. “We are delivering on the ground, and when people come and visit, they’re pleasantly surprised.”
Chadwick said developers also wanted flexibility, with some seeking more height or a different mix of uses. “We ourselves have a plan, but in order to make that more attractive, we have to be prepared to make adjustments as well,” he said.
Ben Edwards, group head of cost, commercial and procurement at Red Sea Global, said the operating track record of The Red Sea and Amaala was now its strongest pitch to investors.
"We’ve gone past the field of dreams approach of ‘if you build it, they will come',” he said. "We’ve built it now. The tourists are coming.”
Edwards said Red Sea Global was at various stages of negotiation on several joint venture opportunities for future projects.
The developer’s utilities public-private partnership (PPP) at The Red Sea is fully operational. Its Amaala equivalent is in final testing and commissioning and is due to be operational before the end of the year. Edwards expects the model to spread.
"I’m sure the PPP market will continue to expand into the different infrastructure sectors here, and then lead into other sectors, from schools to hospitals,” he said.
He added that Red Sea Global’s environmental credentials were a selling point for investors.
Don’t miss MEED’s SMP 2026.
Secure your place as an attendee by clicking here, or email us at meedevents@meed.com
https://image.digitalinsightresearch.in/uploads/NewsArticle/20084647/main.jpeg -
 KBR seeks renewable energy contracts in Libya
29 September 2026
The US-headquartered technology and engineering company KBR is seeking renewable energy project contracts in Libya.
Representatives from KBR met with Abdussalam Elansari, chairman of the Renewable Energy Authority of Libya, earlier this month to discuss project opportunities, sources said.
The meeting with Elansari followed KBR’s opening of a new branch in Libya and its securing of several contract awards in the oil and gas sector.
In March, KBR announced that it had been awarded a contract by Zallaf Exploration, Production & Refining of Oil & Gas Company to provide project management and technical services for the South Refinery Project in Libya’s southern city of Ubari.
Under the terms of the contract, KBR will provide contract management, project management and supporting technical services throughout the engineering, procurement and construction (EPC) phases of the project, according to a company statement.
The EPC work is expected to be executed over a 50-month period.
KBR is also carrying out work to re-evaluate the front-end engineering and design (feed) for the project to develop Libya’s J6 North Gialo field.
In January, KBR signed a memorandum of understanding (MoU) with the state-owned Libyan Post, Telecommunications & Information Technology Company.
Under the MoU, KBR agreed to support efforts to develop and improve Libya’s communications infrastructure and enhance fifth-generation (5G) mobile networks in the country.
KBR has previously provided engineering services for major national projects in Libya, but was forced to shut down its office in the country several times amid political instability and security issues.
When the company was known as Brown & Root, it worked on the Great Man-Made River Project in Libya, which is widely recognised as the largest irrigation project in the world.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20081880/main.jpg