
Middle East stocks recover unevenly
1 June 2026

The combined market capitalisation of the MEED Top 100 largest listed companies in the Middle East and North Africa rose to $3.73tn in mid-May 2026, against $3.48tn a year earlier – a 7.2% gain that recovers most of the value lost in the prior two years’ editions. The aggregate is not the story.
Saudi Aramco recovered by $181bn, rising from $1.64tn to $1.82tn and providing substantial support to the aggregate Top 100 valuation. The broader movements in the list differentiated along sectoral lines, with key trends including the continued growth of regional banks, the upward repricing for fertiliser and logistics names amid the Hormuz crisis, and the correction of Saudi mid-tier stocks as valuation peaks have failed to hold.
Oil and gas reweights
Aramco’s share price recovered from about SR25 to SR30, lifting the company’s market cap by 11% and raising the oil and gas sector’s share of the list back to 54.5%.
The company reported first-quarter 2026 net profit of $32.5bn, up 25%, on revenue of $115.5bn – giving it a price-to-earnings ratio of about 18, in line with the Saudi market average as of April.
Aramco’s diversion of crude to Yanbu through its 7 million-barrels-a-day West-to-East pipeline has supported a higher volume of sales at the now elevated prices compared to its Gulf peers, the exports of which have been more seriously affected by the blockade of the Strait of Hormuz.
Other Saudi names also benefiting from this combination of ongoing access through Yanbu and energy repricing produced the cleanest gains, with Rabigh Refining more than doubling in value to $11.7bn despite a $1.1bn loss, Ades Holding rising 40% to $5.8bn, Luberef rising 28% to $5.8bn and Yansab also seeing double-digit returns.
In the UAE, by contrast, Adnoc Gas has remained broadly flat at $66.7bn, with its Q1 2026 net income dropping 15% and conflict damage estimates indicating that full capacity will not be restored until 2027. Borouge meanwhile held, while Adnoc Drilling and Adnoc Distribution gained by 14% and 8%, respectively.
There was some slippage in the petrochemicals sub-cluster, with Saudi Basic Industries Corporation (Sabic) posting a net loss of $6.96bn and sliding 3%, alongside a 2% slide for the energy sector-adjacent Industries Qatar.
Banking and industry
The banking sector, which accounts for 33 of the 100 entries and 18% of the list by value, expanded by an aggregate 6.3% in absolute terms. Al-Rajhi Bank, the largest banking entry at $107.9bn, reported FY2025 net profit up 26% to SR24.8bn ($6.6bn); total assets passed SR1tn for the first time and Q1 2026 net profit rose a further 14%.
Emirates NBD, up 23% year-on-year to $47.1bn, reported FY2025 record profit before tax of AED29.8bn ($8.1bn) and likewise crossed AED1tn in total assets.
Kuwait Finance House also rose by 19%, Abu Dhabi Commercial Bank 19% to $28.7bn and Saudi National Bank 11%. Qatar National Bank stalled and slid 1%, while several smaller banks saw gains. Egypt’s Commercial International Bank rose 74% to $8.4bn off a depressed base, Jordan’s Arab Bank meanwhile rose 55%, Oman’s Bank Muscat by 52% and RakBank by 32%.
Several sectors have gained significantly owing to their direct exposure to the Iran conflict’s supply-chain repricing, including logistics, fertilisers and mining.
Logistics firms in the list gained 44% in absolute terms, with Saudi Arabia’s Bahri reporting Q1 2026 net profits up 303% year and revenue up 129%.
Marsa Maroc, the Casablanca-listed port operator, also entered the list at $6.6bn, up 85% on an African expansion that spans 34 terminals across 20 ports following a Liberia management deal signed in February.
Adnoc Logistics rose 32% to $11.6bn, while Air Arabia, the Sharjah-based low-cost carrier, joined the list at $6.1bn as it absorbed redirected long-haul flows. Nakilat, the Qatari liquefied natural gas shipping operator, was the sector’s sole softener, down 12% on slower throughput.
Mining and fertiliser entries sit alongside the logistics gainers. Jordan Phosphate Mines is the cleanest single expression of the post-Hormuz repricing visible on the list – up 127% year on year to $13.2bn, as the World Bank’s April 2026 Commodity Markets Outlook projects fertiliser prices to rise nearly 31% in 2026.
Maaden rose 23% to $65.3bn after FY2025 net profit jumped 156%, backed by record phosphate production; high aluminium output; and rising silver, copper and aluminium prices linked to artificial intelligence, data centre, solar and electric vehicle demand.
Morocco’s Managem also entered the list at $19.7bn, having almost tripled in value in the past two years on cobalt, silver and copper prices and African expansion.
Sabic Agri-Nutrients rose 44% on a 30% 2025 net profit increase, while Fertiglobe rose by 40% – both potentially anticipating a 60% forecasted rise in urea prices.
Property and other trends
The direction of the property and real estate sector has been uniformly downward. The Iran conflict has driven both a slump in UAE property sales and prices and a similar tourism-adjacent correction in Saudi Arabia. Both the Mecca-focused Umm Al-Qura and Jabal Omar development firms have seen their valuations slashed by more than a third, while Makkah Construction & Development slid by 15%.
The UAE’s Emaar Properties and Dar Al-Arkan and Qatar’s Ezdan Holding have also all seen slides of more than 15%. Kuwait’s Mabanee, which rose by 22%, is the one exception in the sector.
In Saudi Arabia’s mid-tier, Acwa Power shed 29% in value even as its revenue rose 18% and its net income 5.4%. Elm Company likewise shed 33%, Dr Sulaiman Al-Habib 19% and the Saudi Tadawul Group 21%.
Mouwasat Medical Services, MBC Group, Nahdi Medical and Saudi Logistics Services fell out of the list entirely on the same trajectory. Each had reported FY2025 earnings rises before the decline. What corrected was the valuation, not the operations.
Acwa Power’s trailing four-quarter average price-to-earnings ratio was 166x, and even after this year’s decline sits at 88x against the Saudi market average of 17.8x. Elm sits at 26x, Al-Habib at 33x, Saudi Tadawul Group at 42x – all rich by any comparable benchmark.
Many of these entries have fallen away from their peak valuations as the cooling of the gigaproject programme since early 2025 has undermined sentiment.
One example that sits on the same axis from the UAE side is Abu Dhabi National Energy Company (Taqa), which fell by 28% from $95.3bn to $69.0bn despite a 6% net income rise, even as capital expenditure also expanded by 50%.
There are now nine entries from Morocco’s Casablanca bourse against six a year ago, with an aggregate value of $74.7bn, up from $50.8bn. Industrial contractor Societe Generale des Travaux du Maroc,entered via a December 2025 initial public offering (IPO). Several Moroccan stocks have also slipped, however, including Taqa Morocco, down 42%; Maroc Telecom, down 18%; Banque Populaire, down 13%; and Bank of Africa, down 10%.
There has been a similarly divergent trend among 2024 IPO entrants. While OQ Exploration & Production rose 68% to $10.1bn and is now the largest stock on the Muscat Securities Market, the UAE’s Talabat – 2024’s second-largest IPO at $9.2bn – has corrected 33% to $6.1bn.
The Multiply Group has been replaced on the list through its November 2025 merger into 2PointZero Group, which now sits in the top 30 entries at $19.6bn.
Regional repricing
Four trends underpin the list’s 7.2% recovery. The conflict has repriced specific cohorts sharply higher – logistics up 44%, mining and fertilisers up 43%, the Yanbu refiners returning, and Aramco recovering to $181bn – with gains contingent on the Strait of Hormuz remaining closed.
Regional banks have maintained last year’s momentum, with assets crossing trillion-unit thresholds and loan books supported by project activity. Six names have posted double-digit gains that are unlikely to reverse if conditions normalise.
Saudi mid-tier stocks have corrected largely on valuation rather than operations, despite many reporting earnings growth through 2025, as confidence in gigaproject-driven growth has weakened. Property has also softened in the region as conflict has reduced routine and religious tourism.
The 12-month outlook depends on whether Hormuz reopens, whether Saudi mid-tier valuations stabilise, and whether banking expansion holds under broader repricing.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Algeria tenders 310km Tamanrasset railway
16 October 2026
-
 Joint venture wins $246m RCRC bridges contract
16 October 2026
-
 Humain tenders 100MW Riyadh AI data centre
16 October 2026
-
 Adnoc Onshore seeks bids for Bu Hasa field EOR project
16 October 2026
-
 OTTCO issues tender for Oman oil storage park expansion
16 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends

Related Articles
-
Algeria tenders 310km Tamanrasset railway
16 October 2026
Algeria’s state railway project developer, Agence Nationale d’Etudes et de Suivi de la Realisation des Investissements Ferroviaires (Anesrif), has invited national and international contractors to bid for the construction of a 310-kilometre (km) railway line between Hotel Station and Moulay Lahcen Station.
The planned line is a key segment of the proposed railway corridor connecting El-Menea, In-Salah and Tamanrasset across the southern wilayas of In-Salah and Tamanrasset.
The tender notice was issued on 12 October, with bids due by 10 November.
The tender is open to single contractors and consortiums. To qualify, single firms must have executed at least 200km of new railway lines or track-doubling works since 2010, with accepted project certificates covering sections of at least 100km, along with a cumulative 800 metres of railway bridges with individual spans exceeding 30 metres.
Bidders must also provide at least two rail-tamping machines, two ballast regulators, and a project director with an engineering degree and at least five years of railway construction management experience.
From a commercial and classification perspective, single bidders and consortium leaders must hold a category-nine (IX) professional qualification in public works.
Bidders must also demonstrate an average annual turnover in construction of at least DZ260bn ($1.96bn) across the 2023-2025 financial period.
For joint ventures, the cumulative turnover of all members must meet the $1.96bn threshold, with the consortium leader accounting for at least $1.3bn.
Offers must be accompanied by a bid bond exceeding 1% of the total bid value for submissions exceeding $7.4m, with proposals remaining valid for 90 days beyond the submission date.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20665591/main.jpg -
Joint venture wins $246m RCRC bridges contract
16 October 2026
A joint venture of local contractor Mofarreh Group and Turkey-based Gulsan Holding has won an estimated SR923m ($246m) contract from the Royal Commission for Riyadh City (RCRC) to construct a series of grade-separated steel flyovers across the capital.
The contract, known as Package 2 (Groups 2 and 3), is part of RCRC’s urgent bridges programme under the wider project to build steel bridges at 10 junctions across Riyadh.
The works have a 12-month execution timeline to fast-track traffic decongestion across major arterial corridors.
The joint venture’s scope covers the engineering and construction of grade-separated steel bridge interchanges across seven key intersections:
- IC04: Al-Khair Road and King Salman Bin Abdulaziz Road
- IC05: Prince Turki Road and Imam Saud Road
- IC06: Al-Takhassosi Road and Saeed Al-Sulami Road
- IC07: Khurais Road and Al-Hareth Bin Abdullah Road
- IC08: Khurais Road and Ash-Sharq Road
- IC09: Khurais Road and Marmar Road
- IC10: Al-Kharj Road and Al-Hilla Road
The total length of the flyovers is 8.86 kilometres, excluding Junction IC10.
In addition to the structural steel superstructures, concrete bridge foundations, decks and approach ramps, the contract includes retaining walls, utility diversions, temporary phased traffic arrangements, associated roadworks, drainage networks, roadway lighting, intelligent transportation systems and landscaping.
The client received commercial proposals from several local and international contractors. Other bidders included:
- Masco
- Nesma & Partners
- Al-Omaier Trading & Contracting Company
- Yuksel Saudia
- Batco
- Modern Building Leaders
- Sapac
The urgent bridges initiative is part of Riyadh’s rapid transport infrastructure programme to improve traffic throughput, enhance safety and ease vehicular congestion across central and ring-road corridors ahead of major events, including Expo 2030 and the 2034 Fifa World Cup.
In July, Mofarreh Group and Turkiye’s Gulsan Holding formed a joint venture to bid for and deliver transport infrastructure projects in Riyadh for RCRC.
The joint venture said it will target road, bridge, viaduct and interchange projects.
Mofarreh will provide local market access and operational capacity, while Gulsan will contribute international experience in large-scale transport projects.
The companies said the new venture will support knowledge transfer and localisation, and promote the use of international engineering and construction standards aligned with Saudi Arabia’s Vision 2030 infrastructure and sustainability goals.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20663255/main.png -
Humain tenders 100MW Riyadh AI data centre
16 October 2026
Register for MEED’s 14-day trial access
Saudi artificial intelligence infrastructure developer Humain has issued a request for proposals for an engineering, procurement and construction (EPC) contract to deliver a 100MW artificial intelligence (AI) data centre facility in Riyadh’s Al-Saad area.
The tender was issued on 17 September, with bids due by 8 November.
The contract includes core-and-shell works; civil works; mechanical, electrical and plumbing installation; testing and commissioning; and site infrastructure across a 350,200-square-metre plot.
The project also includes an optional expansion phase that could raise total site capacity to 200MW.
The initial 100MW development is split into two equal 50MW phases, structured across two single-storey IT buildings housing four 25MW data halls.
Phase one targets a ready-for-service date by October 2028, followed by phase two in January 2029.
Under the optional phase three, an additional 100MW facility would be brought online by July 2029.
The data centre will be designed to support high-density graphics processing unit clusters and AI-compute workloads, with rack densities of 240kW to 250kW.
The facility will be built to Uptime Institute Tier III topology and LEED Silver standards as a baseline, targeting LEED Gold.
The operational design targets an annualised power usage effectiveness below 1.35.
Power will be delivered through four 33kV connections supplied by Saudi Electricity Company from two separate high-voltage/medium-voltage primary substations. The scope requires 15 transformers, 15 static 2,250kW IT uninterruptible power supply (UPS) units, and 450kW mechanical UPS systems with lithium-ion battery storage for each 25MW block.
Backup emergency diesel generators will be provided on an owner-furnished, contractor-installed basis, with the EPC contractor handling their installation, connection and testing. Fuel storage will provide 24 hours of autonomous run-time, split between on-site underground bulk tanks and generator belly tanks.
Thermal management combines air and liquid cooling. High-density server racks will be equipped with direct-to-chip liquid cooling loops using coolant distribution units and technical water distribution, paired with air-cooled chillers operating in dual high- and low-temperature loops, alongside fan-wall units.
The total construction timeline is capped at 25 months from site handover or contract signing, with pre-execution early mobilisation scheduled to start in January 2027.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20661045/main.jpg -
Adnoc Onshore seeks bids for Bu Hasa field EOR project
16 October 2026
Register for MEED’s 14-day trial access
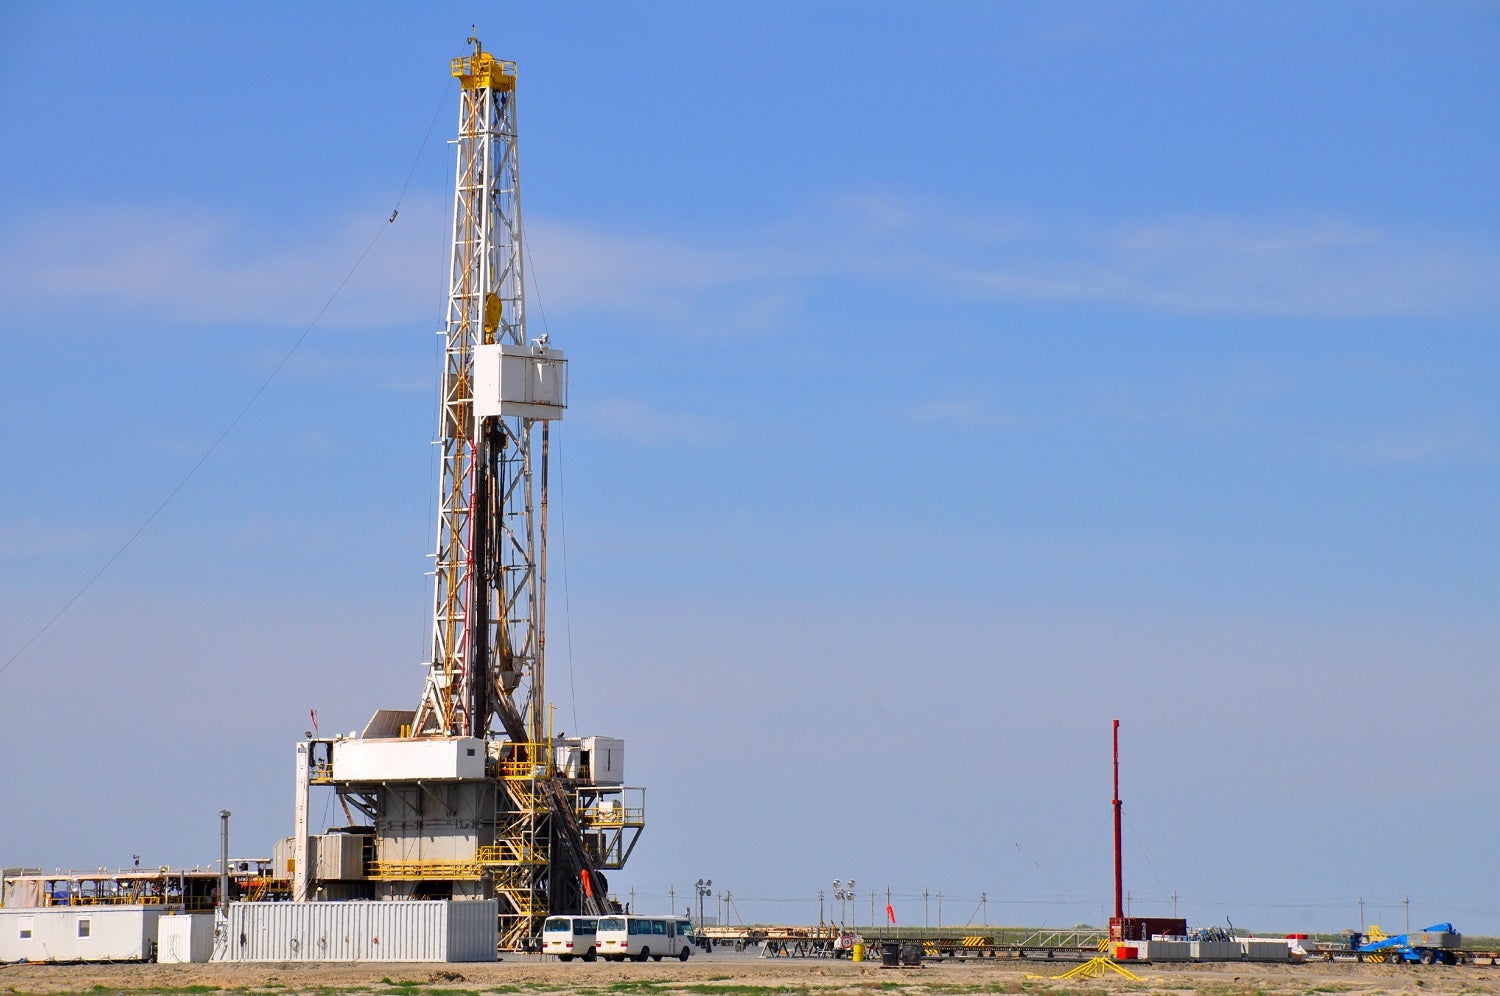
The onshore oil and gas business of Abu Dhabi National Oil Company (Adnoc Onshore) has sought bids from contractors for a key project to increase the oil production capacity of the Bu Hasa oil field, primarily through enhanced oil recovery (EOR) techniques.
The main objective of the Bu Hasa-Shuaiba EOR Unit 1 (Phase 1) project is to achieve a targeted 70% increase in oil production, extend the Bu Hasa field development’s production plateau and maximise the field’s potential in an economical manner.
The project aims to confirm and validate the optimum EOR technology for the top-ranked reservoirs/units; assess incremental recovery on top of the improved oil recovery (IOR) wedge; extend the field plateau for as long as is economically feasible; and achieve an ultimate recovery factor of 70% from the Shuaiba reservoir. It will evaluate and execute the recommended EOR option through pattern phasing for any technology proven by Adnoc.
Adnoc Onshore is understood to have issued the tender for the project on 20 September, with an initial technical bid submission deadline of 8 October, according to sources. The client later extended the technical bid submission deadline to 17 October, sources told MEED.
The chosen contractor will execute the project under a hybrid contracting strategy comprising:
- A lump sum (turnkey) EPC scope covering the complete pipeline system from East Hub to the separation plant
- A call-out-based scope for execution of all WAG injector and WSW tie-in works
Unless otherwise specified, all activities defined under the contractor’s scope will be deemed included within the lump-sum contract price. This will cover engineering, procurement, construction, testing, pre-commissioning and support to commissioning for a complete and operable system.
At the Bu Hasa field development, three remote degassing stations (RDS-1/2/3) and two satellite stations, Bida Al-Qemzan and Huwaila, are currently in operation. Production from oil wells completed in Shuaiba, Thamama B, Thamama F, Bida Al-Qemzan and Huwaila is routed via individual flowlines to the three remote degassing stations and the Bida Al-Qemzan and Huwaila stations across different parts of the field.
Combined production from the wells at each of these stations is routed to the central degassing stations (CDS) via transfer lines ranging from 16 inches to 24 inches in diameter. In addition, some wells in the central part of the field are connected directly to the CDS.
Previous studies have identified carbon dioxide (CO2) flooding as a promising tertiary recovery mechanism in the Shuaiba reservoir, delivering incremental recovery on top of the IOR wedge (P5 project), extending the field plateau as long as economically feasible, and achieving an ultimate recovery factor of 70% from the Bu Hasa Shuaiba units.
Located 200 kilometres south of Abu Dhabi city, Bu Hasa is Adnoc Onshore’s westernmost producing field. It is one of Abu Dhabi's biggest onshore assets, with crude oil production capacity of 650,000 b/d. It is also one of the Adnoc Group’s oldest oil fields, having been discovered in 1962 and in production since May 1965.
As part of the ongoing Bu Hasa Integrated Field Development Project (BUIFDP), 13 new well pads and two pad hubs have been added to the field. Oil, gas and water produced at these sites will be collected at a central gathering facility, then sent through production headers and transfer lines to the CDS for processing.
Adnoc Onshore is the Adnoc Group’s largest oil-producing subsidiary, accounting for 2 million b/d of oil and about 7 billion cubic feet a day of associated gas production from four main onshore field developments in Abu Dhabi: Bab, Bu Hasa, North East Bab and South East.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20639750/main0548.jpg -
OTTCO issues tender for Oman oil storage park expansion
16 October 2026
Register for MEED’s 14-day trial access
Oman Tank Terminal Company (OTTCO) has issued the main tender for a major project related to the expansion of the Ras Markaz crude oil storage complex at Duqm, on the sultanate’s Arabian Sea coast.
The project, titled Trade Bridge, involves the engineering, procurement and construction (EPC) of eight large storage tanks, each with a capacity of 650,000 barrels. This will increase the Ras Markaz terminal’s total storage capacity by 5.2 million barrels.
The project represents the next expansion phase (phase 1.4) of the Ras Markaz oil storage terminal within the Special Economic Zone at Duqm (Sezad).
State-owned OTTCO issued the prequalification notice for the project on 28 July, with contractors submitting initial responses by 4 August and final responses by 19 August, MEED previously reported.
According to sources, OTTCO issued the main tender for EPC works on Project Trade Bridge in the weeks following completion of the prequalification exercise.
The following contractors, among others, are understood to have been prequalified by OTTCO to bid for Project Trade Bridge:
- China Petroleum Pipeline Engineering Company (China)
- China Tianchen Engineering Corporation (China)
- Daqing Oilfield Construction Group Company (China)
- Enppi Muscat (local branch of Egypt-based Enppi)
- Gulf Petrochemical Services & Trading (Oman)
- Hualu Engineering & Technology Company (China)
- Rotary Engineering (Singapore)
- Sinopec Ningbo Engineering Company (China)
OTTCO commissioned the first phase of the Ras Markaz crude oil storage park, covering 10 square kilometres and with a capacity of 26.7 million barrels, in December 2022.
The storage facility has two parts. The first is a marine services area, which includes a floating station for crude imports and exports. This zone is about 7 kilometres offshore and is connected via two 42-inch pipelines and associated facilities.
In water depths of up to 42 metres, the floating station can accommodate very large crude carriers. It is linked to four main pumps that transfer crude oil to the storage area, which is located more than 120 metres above sea level. OTTCO could add pumps at a later stage to keep pace with future demand for oil storage.
The second part of the storage facility features oil pumping systems, water treatment facilities, reservoirs, power station networks and other associated systems.
Region’s largest oil storage park
OTTCO will build the Ras Markaz oil storage facility in five phases over several years across an area of about 40 square kilometres, for which it signed a land agreement with Sezad in July 2017.
It will be able to hold 200 million barrels of crude a year. Total investment in the scheme is understood to be $5.2bn.
The storage terminal in the first phase of the Ras Markaz facility is connected to the estimated $7bn Duqm refinery and other oil-derivatives production plants at Sezad via a pipeline that will supply crude feedstock to the refinery when required.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20638090/main0749.jpg