The region’s most ambitious causeway projects
8 February 2023

The submission of feedback questionnaires and meetings with contractors for the planned second causeway connecting Saudi Arabia and Bahrain is the latest sign of potential progress on one of the region’s largest infrastructure projects.
Causeways have a chequered history in the region. The first causeway connecting Saudi Arabia and Bahrain was completed during the 1980s, and since then, it has had a transformative impact on the Bahraini economy.
The project’s success has inspired other causeways. But while these schemes remain ambitions for many in the region, construction progress has been limited. The hope is that a successful second causeway linking Saudi Arabia and Bahrain will foster the delivery of other longstanding causeway plans.
These are the most ambitious causeway schemes that the region has planned:
| Second Saudi Arabia-Bahrain causeway |
The second causeway between Saudi Arabia and Bahrain is the most likely to proceed. Planned by the King Fahd Causeway Authority, the $3.5bn project, which has been called the King Hamad Causeway project, is moving towards construction.
In 2021, senior government officials in Bahrain told MEED that the project was progressing towards tendering as financial studies had been completed.
The project was included in Bahrain’s $30bn Strategic Projects Plan that was announced later in 2021. As well as the causeway, the plan includes building new urban areas on five reclaimed islands to increase the country’s total land area by 60 per cent. It also comprises plans for a new airport.
The second causeway involves building a 25-kilometre road and rail crossing linking Saudi Arabia and Bahrain. It will follow the same alignment as the existing King Fahd Causeway.
It has been earmarked for delivery on a public-private partnership (PPP) basis. The King Fahd Causeway Authority appointed a consortium to provide transaction advisory services in late 2019.
The $8.9m consultancy agreement was signed with a consortium of Netherlands-headquartered KPMG, US-based Aecom and UK-based CMS. The team was tasked with working on developing the financing model, the required engineering specifications and design, as well as helping with the assessment and selection of the project’s developers.
Canada-based SNC Lavalin and UK-based consultancy firm PwC conducted the project due diligence study in 2017.
The existing King Fahd Causeway is operating at capacity. About 11.5 million cars cross the causeway every year, and the growth has been 6 per cent per annum over the past 10 years.

| Qatar-Bahrain causeway |
There have also been suggestions that the proposed causeway bridging Bahrain and Qatar may be revived. In March 2022, Manama called for work to restart on the causeway joining the two countries.
“We in the Kingdom of Bahrain renew the call for the start of bilateral talks between the two sides in accordance with the mechanisms agreed upon in the Al-Ula statement,” said Bahrain’s undersecretary for land transportation and post in an official statement published by the official Bahrain News Agency.
The estimated $4bn Qatar-Bahrain causeway project was put on hold and the contracting consortium demobilised in 2010.
A joint venture of state-owned developer Qatari Diar Real Estate Investment Company and French contractor Vinci Construction Grand Projets led the consortium. The other consortium members were Germany’s Hochtief, Athens-based Consolidated Contractors Company (CCC), Dredging International from Belgium and the local Middle East Dredging Company (Medco).
The planned 40km bridge includes a four-lane motor crossing scheduled for completion in 2013 and two railway lines forming part of the GCC rail network.
The project also comprises 22km of bridges and viaducts, 18km of embankments and two 400-metre cable-stayed bridges. The causeway connects Ras Ashairij on the west coast of Qatar to Askar on the east coast of Bahrain.
The project was also known as the Friendship Bridge and was to be jointly funded by the Qatari and Bahraini governments, which intended to recover some of the construction costs by implementing a toll system on the bridge.
The crossing would cut the journey time between the two countries, which currently involves a detour through Saudi Arabia, from five hours to just 30 minutes.
| Saudi Arabia-Egypt causeway |
The prospects for the causeway connecting the $500bn Neom project in Saudi Arabia and Egypt’s Sinai Peninsula across the Straits of Tiran improved last year after US President Joe Biden’s visit to Saudi Arabia.
After the visit, a joint communique issued by Washington and Riyadh referred to the development of Tiran Island.
“President Biden welcomed the arrangements by Saudi Arabia to remove the Multinational Force & Observers (MFO) from the Island of Tiran, including the removal of US troops there as part of the MFO mission, while preserving and continuing all existing commitments and procedures in the area,” it said.
“This area of the Red Sea will now be developed for tourism and economic purposes, contributing to a more secure, peaceful and prosperous region.”
The US-Egyptian-Israeli-backed MFO was founded in 1981 to oversee the terms of the 1978 Camp David Accords, which included the full Israeli withdrawal from the Sinai Peninsula.
In 2016, Egypt and Saudi Arabia agreed during a state visit to Cairo by King Salman bin Abdulaziz al-Saud to develop a causeway linking the two countries across the Red Sea.
The agreement was made as part of a broader deal that would also involve Egypt ceding the sovereignty of the two Tiran islands to Saudi Arabia.
While details of the proposed crossing were never revealed at the time, it was understood to be a revival of a $4bn project announced in 2011. That scheme involved building a 32km crossing stretching over the Straits of Tiran from Ras Humaid in Tabuk, in the northern region of Saudi Arabia, to Ras Nasrani, close to the Egyptian resort of Sharm el-Sheikh.
Plans to link Saudi Arabia and Egypt are far from new. The development of a causeway was first mooted as far back as 1988. However, the idea has received additional focus in recent years following the launch of the Neom development in northwestern Saudi Arabia, which includes Ras Humaid. Part of the Neom scheme, the 170km-long linear city known as The Line, will extend from the promontory inland to the city of Tabuk.
UK-based Arup was reported to have been selected in 2019 for the next stage of the feasibility study for the causeway.
Saudi Arabia was understood to be considering using a public-private partnership (PPP) model for the scheme, similar to other transport projects planned in and around the kingdom.
| Yemen-Djibouti causeway |
A 28.5km causeway was planned to connect Yemen and Djibouti before the scheme was put on hold in 2010 until the governments of both countries signed the framework agreement for the project. The civil war in Yemen means it is unlikely the scheme will make any progress soon.
The estimated $20bn first phase involved building the link between the Yemeni mainland to the island of Perim in the Red Sea. Phase two would have then connected Perim with Djibouti.
The wider project also involves building two cities at each end of the link. The total investment required to construct the cities and the bridge is $200bn.
Dubai-based Al-Noor Holding Investment Company was developing the project.
In 2009, the company said it expected to award a build-operate-transfer contract for the first phase of the bridge and that three companies had expressed interest in funding and building the road and rail link. Denmark’s Cowi prepared the preliminary design for the crossing.
| UAE-Qatar causeway |
In 2005, Abu Dhabi and Doha were reported to have been setting up a joint company to oversee the implementation of the proposed UAE/Qatar causeway.
The 40km causeway was expected to start near Sila in Abu Dhabi emirate and extend to the south of Doha.
The estimated $13bn crossing would have significantly cut journey times. At present, traffic between Qatar and the UAE has to pass through 125km of Saudi Arabian territory.
The scheme stalled shortly afterwards. Problems included difficulties with the route, which ran through Saudi Arabian territorial waters.


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 WEBINAR: End-of-Year Mena Market Review
13 November 2026
-
 PDO awards contract for Al-Ghubar oil field project
12 November 2026
-
 Laing O’Rourke joins the international exit list
12 November 2026
-
 Poland’s Orlen terminates QatarEnergy LNG supply deal
11 November 2026
-
 Riyadh shifts bid deadline for King Salman Stadium works
11 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
WEBINAR: End-of-Year Mena Market Review
13 November 2026
Webinar: The big questions shaping the Gulf market. You decide what gets debated.
Tuesday 24 November 2026 | 11:00 AM GST | Register now
What makes this session particularly interesting is that the audience gets to decide the agenda. Registrants can vote for the topics they’d like Ed and Colin to debate, with the most popular questions forming the final shortlist for the live session.
Topics in the ballot:
- Is the Gulf trying to build too much, too quickly?
- Saudi Arabia or the UAE: where would you place your next big bet?
- Are gigaprojects the best use of public money?
- Who is really responsible when projects go wrong?
- Should the lowest-price tender become a thing of the past?
- Can private capital take over from the government in financing infrastructure and diversification?
- Is the Gulf’s AI and data centre boom a smart bet or the next overbuilding risk?
- Should the Gulf double down on hydrocarbons to fund diversification?
- Is localisation strengthening the economy or making delivery harder?
- Are Gulf countries building complementary economies or competing for the same customers?
The session will also feature live audience polling and Q&A, giving attendees an opportunity to share their views.
Hosted by:
Edward James, head of content and analysis at MEED
 A well-known and respected thought leader in Mena affairs, Edward James has been with MEED for more than 19 years, working as a researcher, consultant and content director. Today, he heads up all content and research produced by the MEED group. His specific areas of expertise are construction, hydrocarbons, power and water, and the petrochemicals market. He is considered one of the world’s foremost experts on the Mena projects market. He is a regular guest commentator on Middle East issues for news channels such as the BBC, CNN and ABC News and is a regular speaker at events in the region.
Colin Foreman, editor of MEED
 Colin Foreman is editor and a specialist construction journalist for news and analysis on MEED.com and the MEED Business Review magazine. He has been reporting on the region since 2003, specialising in the construction sector and its impact on the broader economy. He has reported exclusively on a wide range of projects across the region including Dubai Metro, the Burj Khalifa, Jeddah Airport, Doha Metro, Hamad International airport and Yas Island. Before joining MEED, Colin reported on the construction sector in Hong Kong.https://image.digitalinsightresearch.in/uploads/NewsArticle/21380319/main.gif
-
PDO awards contract for Al-Ghubar oil field project
12 November 2026
Register for MEED’s 14-day trial access
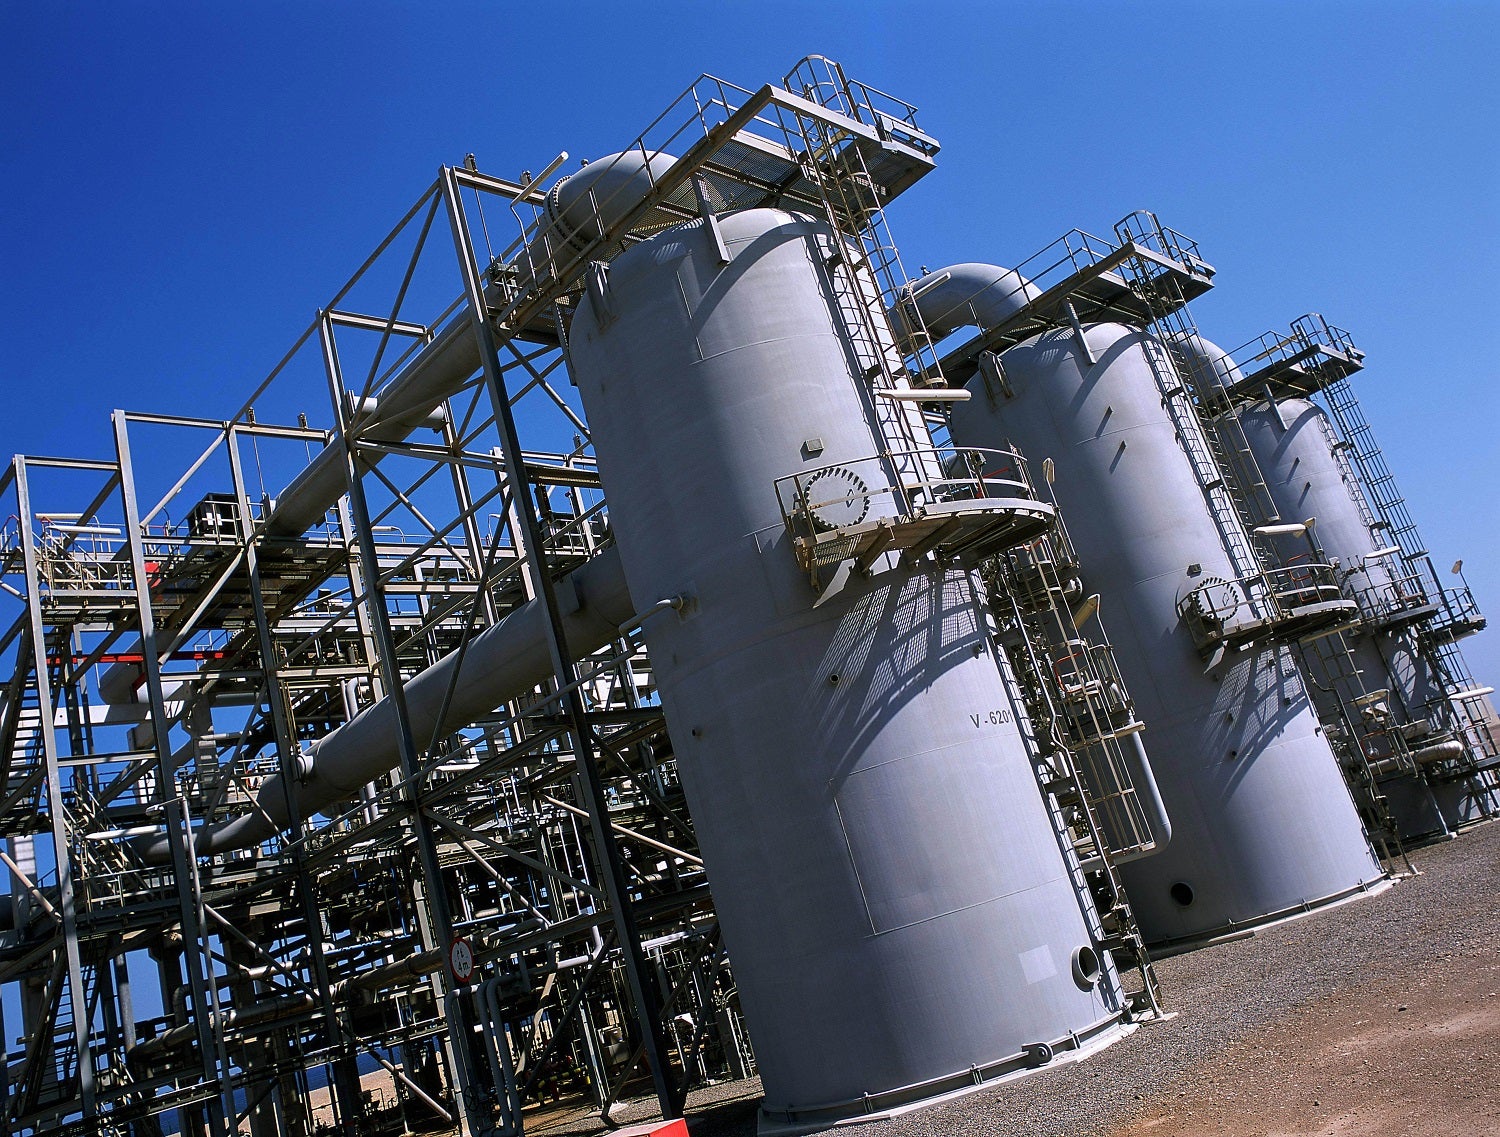
Petroleum Development Oman (PDO) has awarded the main contract for a project to build a facility to handle additional oil production from the Al-Ghubar field in the sultanate.
The Al-Ghubar field is located in the Ghaba Salt Basin at Qarn Alam, within majority state-owned PDO’s Block 6 concession area.
The Al-Ghubar gas-oil gravity drainage (GOGD) facility will be designed as a sour (hydrogen sulphide) facility and is expected to handle a maximum oil production rate of 1,800 standard cubic metres a day (cm/d), a total water flow rate of up to 10,421 standard cm/d and gas lift of up to 256,934 standard cm/d. Production from the planned Al-Ghubar GOGD facility will be exported to PDO’s main oil line.
China-based Jereh Group has won the contract for the Al-Ghubar GOGD facility project, sources told MEED.
A project kick-off meeting between PDO and Jereh has also recently taken place, the sources said.
MEED previously reported that Jereh had emerged as the lowest bidder for the project.
The following contractors, among others, are understood to have been bidding for the Al-Ghubar GOGD facility project:
- Engineering for the Petroleum & Process Industries (Egypt) / Petrojet (Egypt)
- GS Engineering & Construction (South Korea)
- Jereh (China)
- Larsen & Toubro Energy Hydrocarbon (India)
PDO floated the tender for the Al-Ghubar GOGD facility project in March, setting an initial bid submission deadline of 4 May, MEED previously reported.
PDO later extended the deadlines for the submission of technical and commercial bids to 26 July and 7 August, respectively. Contractors submitted technical proposals by the revised deadline, according to sources.
After receiving the technical bids for the project in July, PDO granted contractors until 16 August to submit commercial bids. It eventually extended the deadline to 1 September, with contractors submitting commercial proposals by that date, as MEED reported.
The scope of work on the Al-Ghubar GOGD project covers the engineering, procurement and construction (EPC) of the following:
- On-plot scope, consisting of:
- Production separator
- Test separator
- Concentric wash tank
- Wet oil pump
- Water bath heater
- Surge tank
- Gas injection/gas lift compressor (centrifugal)
- Utilities (instrument air compressors, chemical injection skids, drain system, vent system)
- Suction scrubber
- Air coolers
- Discharge scrubbers
- Condensate flash drum
- Atmospheric pressure knock-out drum
- Flare system
- Gas heater
- Water disposal pump
- Oil shipping pump
- 132kV substation and plant substation (housing 6.6kV and 415-Volt switchboard)
- Control room
- Off-plot scope consisting of:
- Off-plot pipeline network (bulk header, test header, gathering infrastructure/ gathering line header, instrument air header, water disposal header)
- Two remote manifold stations
- Tie-in connection to main oil line
- Tie-in to gas network pipeline
PDO previously intended to tender the Al-Ghubar GOGD project under its framework structure with selected EPC contractors, but ultimately tendered it separately.
PDO is the operator of Oman’s Block 6 hydrocarbons concession, the sultanate’s largest and most prolific concession. Situated onshore and covering an area of 75,119 square kilometres, Block 6 contains 202 oil fields and 43 gas fields. PDO produces approximately 680,000 barrels a day of oil and condensates from the fields.
The Omani government holds a 60% stake in PDO through Energy Development Oman. The other shareholders are UK-based Shell (34%), France’s TotalEnergies (4%) and Thailand’s state-owned PTTEP (2%).
https://image.digitalinsightresearch.in/uploads/NewsArticle/21345337/main2647.jpg -
Laing O’Rourke joins the international exit list
12 November 2026
Commentary
Colin Foreman
EditorRegister for MEED’s 14-day trial access
Laing O’Rourke’s decision to seek a buyer for its Middle East business marks the end of an era for UAE construction.
In the early 2000s, the contractor was among the leading names in the market. Its work at Dubai International airport, the Atlantis hotel on the Palm Jumeirah and the ski slope at Mall of the Emirates made it arguably the UAE’s most prominent contractor during the pre-global financial crisis construction boom.
Its activities were not limited to Dubai. A partnering agreement with Aldar for Al-Raha Beach then made it the most active contractor in Abu Dhabi almost overnight.
The global financial crisis changed its fortunes. The Aldar Laing O’Rourke joint venture ended. Unsettled by payment problems and wider stress in the industry, the company took a more cautious approach to clients and projects in the region. One executive at the time told MEED: “You might see lots of tower cranes, but none of them are doing work that we would want to do.”
The contractor’s appetite partially returned in the late 2010s, when it won Al-Wasl Plaza at the Expo 2020 site in Dubai. It also became a leading player in the growing data centre market, delivering facilities for repeat clients, including Khazna and Equinix.
Data centres have since been its focus. These are significant projects, but they lack the public profile of the airport, Atlantis and Al-Wasl Plaza. As its profile faded, the company sold its UAE joinery arm to Dubai-based Arco Turnkey Solutions in 2025.
Laing O’Rourke now looks set to follow other international contractors that have, for various reasons, left the region, including Murray & Roberts, Balfour Beatty, Multiplex, Carillion and Bam. With a record £17.2bn order book anchored by UK and Australian infrastructure, the group’s priorities clearly lie elsewhere.
Whoever buys the business will inherit strong data centre credentials. For much of the market, however, Laing O’Rourke will be remembered for the landmark projects that defined the UAE’s boom years.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21344577/main.jpg -
Poland’s Orlen terminates QatarEnergy LNG supply deal
11 November 2026
Register for MEED’s 14-day trial access
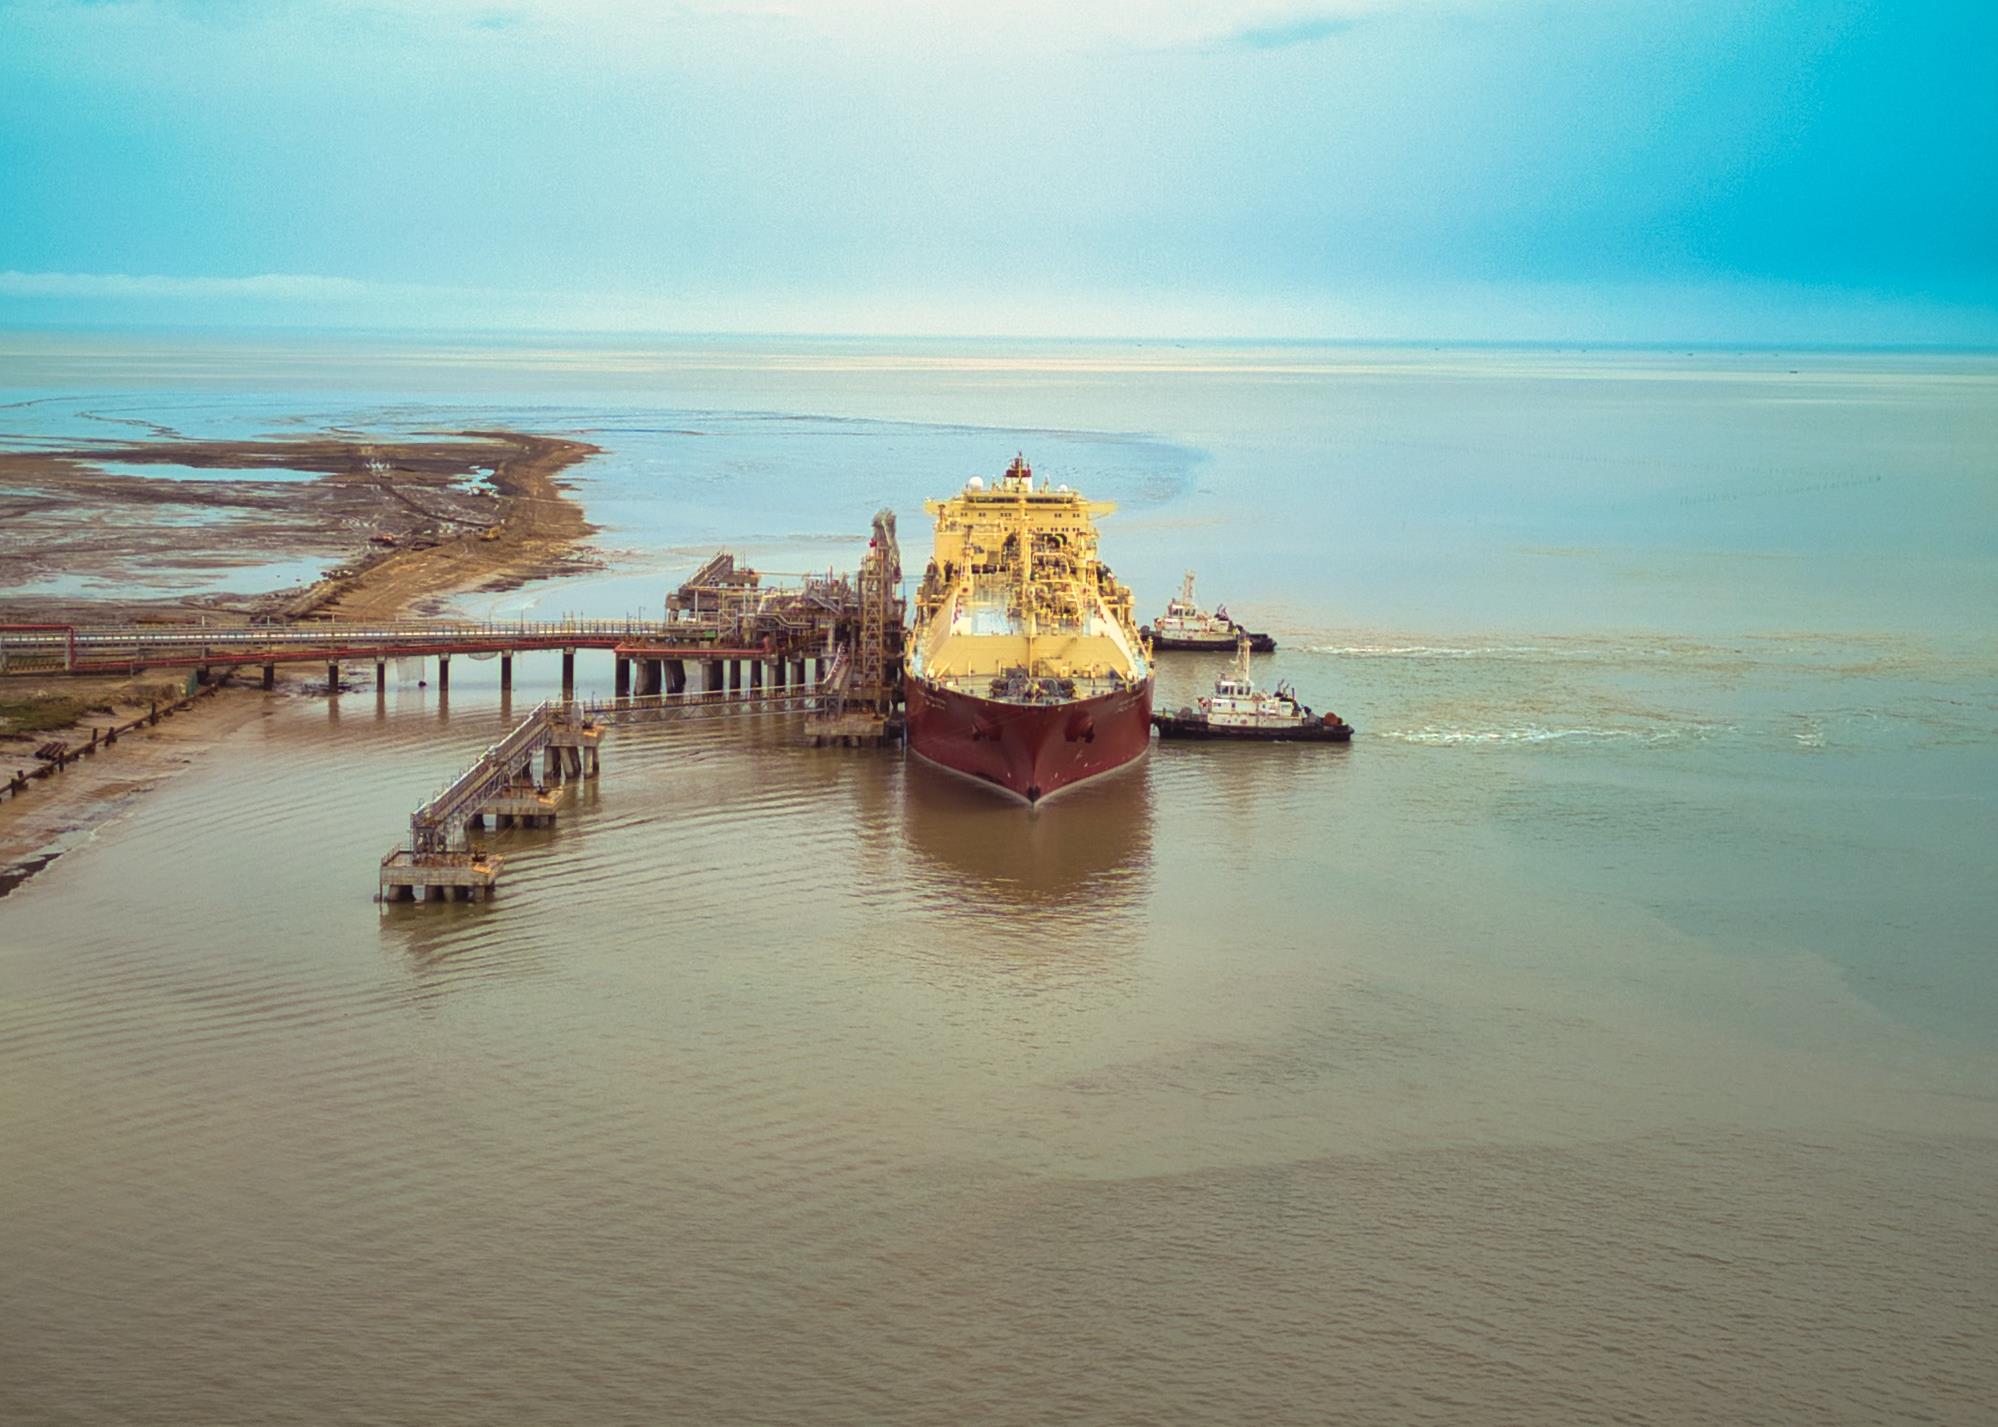
Poland’s Orlen has announced it has terminated one of two long-term contracts for the supply of liquefied natural gas (LNG) by QatarEnergy LNG, a subsidiary of state enterprise QatarEnergy. The termination follows an ongoing force majeure event “resulting in an inability to meet contractual delivery obligations”.
The agreement covered the supply of 1 million tonnes a year (t/y) of LNG, equivalent to approximately 15.3 terawatt-hours, with pricing linked to crude oil quotations. The estimated value of the agreement for 2026 is approximately €570m ($634.9m), Orlen said in a statement on 10 November.
The terminated agreement was originally signed by Polskie Gornictwo Naftowe i Gazownictwo and QatarEnergy on 29 June 2009. Deliveries under the agreement commenced in 2016 and were due to remain in force until 2034, the Polish energy company said.
The agreement will remain in force for a further 60 days following the notice of termination, Orlen said in its statement.
Orlen continues to honour its second agreement with QatarEnergy, which covers deliveries of up to 1 million t/y of LNG until 2034, under a pricing formula linked to gas price quotations.
“The decision to terminate the agreement does not affect the security of gas supplies. Gas production from the company’s own fields, together with its long-term gas supply agreements, ensures full coverage of Orlen Group’s gas requirements,” the company concluded.
It is not clear whether Orlen’s termination of one of its long-term LNG supply agreements with QatarEnergy is related to the Qatari energy giant declaring force majeure on two instances in March this year, when its energy infrastructure was hit in Iranian drone and missile attacks.
Force majeure episodes
On 4 March, QatarEnergy issued force majeure to customers that were affected by its decision to stop production and shipments of LNG and associated products after military attacks on the company’s operating facilities in Ras Laffan Industrial City and Mesaieed Industrial City in Qatar on 2 March.
Later that month, Qatar said Iranian missiles had caused extensive damage at Ras Laffan Industrial City on 18 March, with Saad Sherida Al-Kaabi, QatarEnergy’s CEO and Minister of State for Energy Affairs, saying that the Iranian strikes had knocked out about 17% of its LNG export capacity, causing an estimated $20bn in lost annual revenue.
At least two of Qatar’s 14 LNG trains and one of its two gas-to-liquids facilities were damaged in the Iranian strikes, Al-Kaabi told news agency Reuters at the time.
Repairing damaged assets will sideline 12.8 million t/y of LNG for three to five years, threatening supplies to European and Asian nations, including China and India, according to Al-Kaabi.
As a result, QatarEnergy said it would have to declare force majeure on long-term contracts for up to five years for LNG supplies bound for Italy, Belgium, South Korea and China. Poland was not specifically mentioned at the time.
“These are long-term contracts that we have to declare force majeure. We already declared, but that was a shorter term. Now it is whatever the period is,” Al-Kaabi said in March.
QatarEnergy currently has a nameplate LNG production capacity of 77.5 million t/y, with all its processing trains and export infrastructure located in Ras Laffan Industrial City, which lies about 90 kilometres to the north of Doha and is home to the largest LNG production and export facility in the world.
QatarEnergy’s LNG production capacity is on course to rise to 142 million t/y when the three phases of its $40bn North Field LNG expansion programme are commissioned by the end of the decade. Engineering, procurement and construction works on its North Field East, North Field South and North Field West projects are progressing, with the first phase expected to be operational by the end of this year.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21333808/main2615.jpg -
Riyadh shifts bid deadline for King Salman Stadium works
11 November 2026
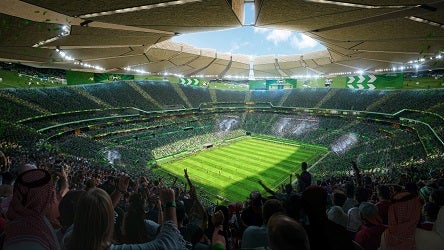
Saudi Arabia’s Sports Ministry has set a deadline of 1 December for a contract covering early works at the King Salman International Stadium in Riyadh.
The tender scope encompasses enabling works, site preparation and initial construction activities. The tender was issued on 11 October, carrying an initial submission deadline of 19 November. Contractors previously submitted prequalification statements for the main design-and-build contract in February.
Designed by US-based architectural firm Populous, the stadium will cover approximately 660,000 square metres (sq m), seat 92,000 spectators and stand adjacent to King Abdulaziz Park. Facilities will feature a 150-seat royal suite, 120 hospitality suites, 300 VIP seats and 2,200 dignitary seats.
The broader masterplan encompasses more than 360,000 sq m of ancillary facilities, featuring two training fields, fan zones, a closed sports hall, an Olympic-sized swimming pool, an athletics track, and outdoor courts for volleyball, basketball and padel.
Scheduled for completion by 2029, the venue will serve as the home base for the Saudi national football team and host the opening match and final of the 2034 Fifa World Cup.
Saudi stadium plans
In August 2024, MEED reported that Saudi Arabia plans to build 11 new stadiums and refurbish four existing venues for the 2034 tournament. Eight venues will be located in Riyadh, four in Jeddah, and one each in Al-Khobar, Abha and Neom.
An additional 10 cities will host team base camps: Al-Baha, Jazan, Taif, Medina, AlUla, Umluj, Tabuk, Hail, Al-Ahsa and Buraidah. Across the kingdom, organisers plan to deploy 134 training sites, comprising 61 existing facilities and 73 new builds.
Saudi Arabia was officially selected to host the 2034 Fifa World Cup during an online convention of member associations at the Fifa Congress on 11 December 2024.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21325461/main.jpg