
Qatar banks search for growth
13 January 2026

Compared to the explosive loan growth witnessed in some other Gulf states, Qatar’s banking sector remains stuck in a lower gear, as a product of both a tougher interest rate environment and rising operating expenses and loan-loss provisioning charges. This resulted in flat profits in H1 2025, when the aggregate net income of banks rated by Moody’s stood at QR14.2bn ($8.9bn) – just 1% higher than the previous year.
The largest Qatari lender, Qatar National Bank (QNB), reported net profits of QR12.8bn ($3.5bn) for the first nine months of 2025, a 1% increase compared to the same period in 2024. Commercial Bank of Qatar (CBQ), another large Qatari lender, reported a 16.5% decline in profits over the same period, to QR1.96bn, with loan impairments and lower interest income squeezing margins.
Provisioning and risk-linked costs
Unlike Saudi Arabia’s booming mortgage market, Qatar has not offered income-fattening lending opportunities. Instead, provision levels are elevated: the ratio of loan loss provisions to gross loans stood at 4.2% in October 2025, up from 3.9% at the end of 2024. According to QNB Financial Services, provisions increased by 14.5% in the first 10 months of 2025.
And analysts see overall provisioning costs remaining elevated this year. Though sector-wide provisioning fell to around 9% at the end of Q3 2025, down from 12% a couple of years ago, it remains at a level that is weighing on the banking sector’s profitability.
The ratio of underperforming loans with increased credit risk is also elevated. “The sector is starting to see a gradual, though modest, decline in Stage 2 loan ratios among the banks most impacted, but levels remain above those of Saudi Arabian and UAE banks,” says Amin Sakhri, director, Financial Institutions for Fitch Ratings.
Analysts also see other banking metrics remaining challenged.
“We expect the cost of risk to remain at the recent high level, especially at banks which are more exposed to real estate and contracting sectors,” says Francesca Paolino, assistant VP-analyst at Moody’s Ratings.
“This is because we still foresee asset quality pressure at such banks largely reflecting overcapacity in the real estate sector and payment delays in the contracting sector.”
Nonetheless, says Paolino, Qatari banks still benefit from significant lending to the low-risk Qatari government and public sector organisations, while personal loans are largely to Qatari nationals with high job security and creditworthiness.
Steady, but static profitability
Profitability metrics are likely to be broadly stable for the full year 2025, predicts Fitch’s Sakhri, despite the US-tracking rate cuts, as Qatari banks are more neutral to these than other banks in the GCC because their costs of funding tend to benefit more.
“We’re not anticipating a significant uptick in terms of profitability metrics for 2026 and any uptick could be coming from some reduction, albeit modest, in loan impairment charges. We’re seeing some further stabilisation in terms of the domestic operating environment, with asset quality deterioration being more contained,” says Sakhri.
Loan growth is picking up, which may provide some uplift to profits this year – even if it is unlikely to prove spectacular.
Alongside the reducing cost of risk, another factor that will support profits this year is growth in key economic sectors. Fitch anticipates a credit growth of about 6% for the sector in 2026, with demand coming from key economic sectors.
Wider economic improvements will also feed through into the banking sector.
Moody’s expects non-oil growth in the single digits, at 4.0% in 2026 – down slightly on 4.5% in 2025, but still up from 3.4% in 2024 and 2.1% in 2023. This is being spurred by sporting events, business exhibitions and related economic activities, as well as projects associated with the expansion of Qatar’s liquefied natural gas production capacity. “As a result, we expect private sector credit growth to be around 5% in 2026,” says Moody’s Paolino.
Higher fee and commission income, driven by growing non-funded income-related activities, will offset a potential drop in net interest income in 2026 even as interest rate cuts constrain margins. The net effect will be to keep operating income broadly stable.
“We expect cuts in interest rates to temporarily squeeze NIMs [net interest margins] because loan interest rates are likely to decline faster than the rates paid on deposits and other funding costs,” says Paolino.
“However, this will also be mitigated by the banks’ skew towards short-term funding, which enables them to respond quickly to lower interest rates.”
Digital-driven efficiency
Another core strength of Qatari banks is their GCC-leading operating efficiency levels. According to Moody’s, the cost-to-income ratio remains around 25% – a level it does not expect to drastically change.
In the short term, Qatari bank investments in digital tools and technology are expected to keep expenses on a rising trend. Longer term, however, the hard-wiring of digital services into lenders’ offerings is liable to yield dividends.
For example, QNB last year signed three memorandums of understanding with Qatar Financial Centre (QFC), Qatar Development Bank (QDB) and Rasmal Ventures, aimed at strengthening Qatar’s role as a hub for fintech and digital transformation. The QFC agreement involves QNB facilitating the growth of fintech firms by providing access to banking infrastructure and supporting innovation in digital assets, tokenisation and embedded finance.
Such moves, along with customer-facing measures designed for ease of use, will inevitably enhance performance levels. That in turn will help Doha’s banks soften the blow of the other headwinds in effect in Qatar, including higher taxes.
As Paolino explains: “Another aspect we expect to impact profitability, compared to the past, is the higher tax expenses because of the accrual of Pillar Two Taxes, effective from 1 January 2025, under the Global Anti-Base Erosion (GloBE) rules, known as the Global Minimum Tax.”
As of June 2025, notes Moody’s CBQ and QNB’s net profit reflected a higher tax expense of QR2.3bn ($630m), compared with QR1.5bn ($410m) in H1 2024.
Qatar is not alone in the Gulf in applying these rules, but it does suggest that reversing the flat profit trend will not be a simple affair for banks in 2026.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Brent hits $112 a barrel following Saudi oil field attack
22 October 2026
-
 Nebius agrees Neom AI data centre capacity deal
22 October 2026
-
 Riyadh awards $301m Sheikh Jaber Road contract
22 October 2026
-
 Dewa International signs energy and infrastructure MoUs
22 October 2026
-
 EGA’s Al-Taweelah restoration reaches 50% completion
22 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends

Related Articles
-
Brent hits $112 a barrel following Saudi oil field attack
22 October 2026
Register for MEED’s 14-day trial access
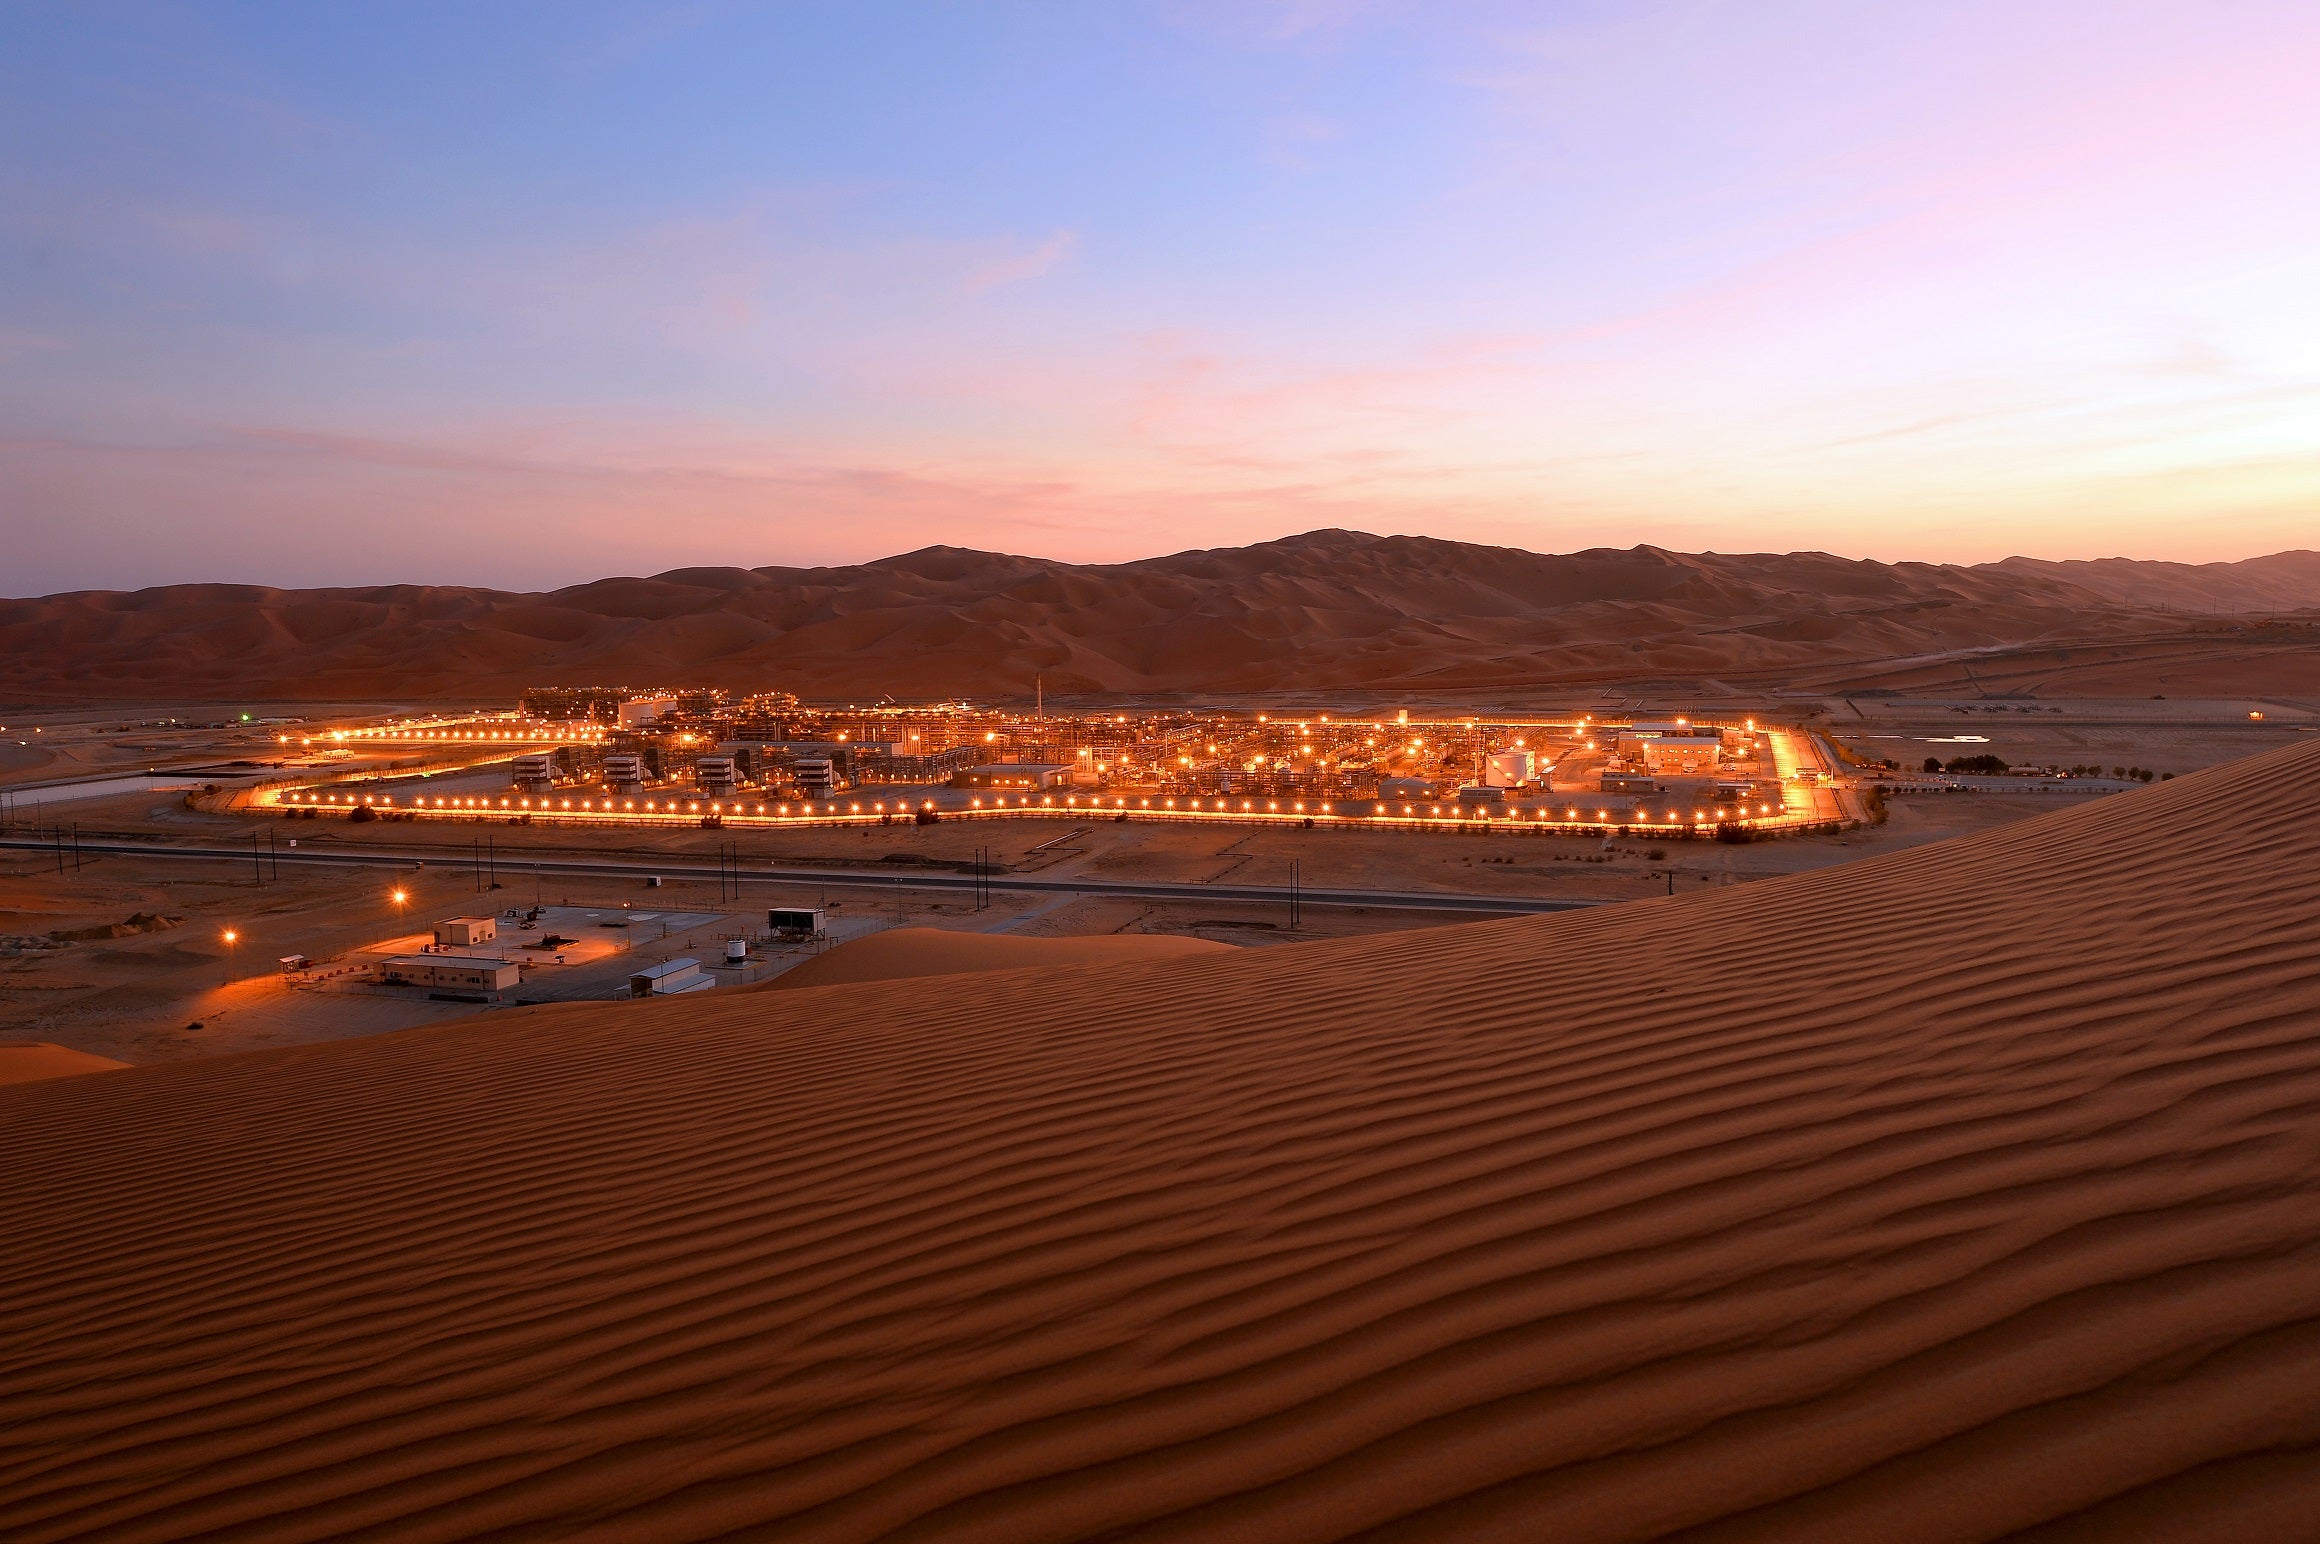
Oil prices climbed more than 3% on 22 October after a drone targeting Saudi Aramco’s Shaybah oil field development killed two people and injured two others a day earlier, adding to concerns over energy supplies as attacks on Saudi energy infrastructure intensified.
Global benchmark Brent crude hit $112.30 in early trading on 22 October, but later pared gains and was trading at $111.52 a barrel as of 11am GST.
Three residents and a Saudi citizen were killed in two separate incidents in Saudi Arabia’s Eastern Province on 21 October, authorities said, as attacks on the kingdom accelerated following an escalation of hostilities with the Iran-backed Houthi group in neighbouring Yemen.
Overnight, the Saudi-led coalition fighting the Houthis in Yemen announced that it had intercepted and destroyed four drones in the Eastern Province.
Saudi air defences intercepted a drone attempting to target a processing facility at Saudi Aramco’s Shaybah oil field development on the morning of 21 October, the Saudi Ministry of Energy said.
The official Saudi Press Agency (SPA) carried a statement quoting an energy ministry official as saying the attempted attack resulted in the deaths of two residents – a Filipino and a Nepali – and injuries to two others – an Indian and a Pakistani – after debris fell due to the interception.
Following the interception, a fire broke out in a vehicle belonging to a contractor at the Shaybah oil field, outside the facility’s perimeter, with no impact on operations.
Dammam airport attack
Separately, a Houthi attack on King Fahd International airport in Dammam on the evening of 21 October killed an Indian resident and a Saudi citizen.
Eight people were also injured in the attack, including a Saudi national, a Nepali, and two nationals each from India, Yemen and Bangladesh. Injuries ranged from minor to critical, the Saudi General Authority of Civil Aviation (Gaca) said the next day.
“The attack also caused property damage, the extent of which is currently being assessed. Further updates will be provided,” Gaca said, adding that operations had since resumed at Dammam airport.
Saudi Arabia has come under sustained attack from the Iran-aligned Houthi rebel group in October, including strikes on Riyadh’s international airport in what authorities described as the kingdom’s deadliest incidents in years, as the war with the group escalates.
The Houthi militias also struck an administrative building at Aramco’s headquarters in Dhahran, in the Eastern Province, on 13 October, resulting in a limited fire.
The Houthi rebels opened a new front in the regional war between Iran and the US in mid-July, when they breached a four-year truce with Saudi Arabia in Yemen’s civil war, which began in 2014, and started attacking Saudi vessels and Aramco energy assets along the Red Sea, including repeated strikes on the Jizan refinery.
The 1,200-kilometre East-West pipeline operated by Aramco was also hit by Houthi missiles in September, and once directly by Iran in April.
The East-West pipeline transports crude from Saudi Arabia’s Eastern Province oil fields to the Red Sea port city of Yanbu on the kingdom’s west coast. It has a pumping capacity of 7 million barrels a day.
Saudi Arabia relies heavily on the East-West pipeline to bypass the volatile Strait of Hormuz maritime chokepoint and ship crude from its Red Sea coast. Riyadh has increasingly used the line to route exports away from Hormuz since the US-Iran conflict began on 28 February – a tactical advantage most of its Gulf neighbours lack.
Aramco resumed crude exports via the pipeline at the start of October.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20841984/main.jpg -
Nebius agrees Neom AI data centre capacity deal
22 October 2026
Register for MEED’s 14-day trial access
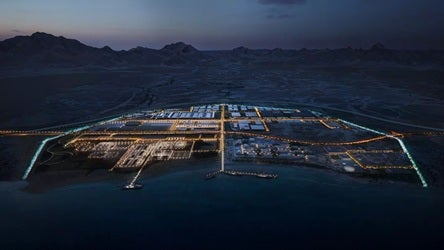
Saudi artificial intelligence (AI) company Humain and data centre developer DataVolt have signed a preliminary framework agreement with Netherlands-based AI cloud company Nebius for up to 50MW of data centre capacity at Oxagon, Neom’s industrial city on the kingdom's Red Sea coast.
Under the proposed agreement, Nebius will become an anchor customer at the planned AI data centre campus.
The contemplated capacity represents half of the initial 100MW currently under construction, which forms part of a planned 360MW first phase.
The capacity is expected to be commissioned in stages from the fourth quarter of 2027.
Humain, which is owned by Saudi sovereign wealth vehicle the Public Investment Fund, and DataVolt began construction on the initial 100MW facility at Oxagon in September. The wider campus is planned to reach 1.5GW of capacity.
The agreement was signed during Nvidia’s GTC event in Berlin, held on 20-22 October. The US graphics processing unit (GPU) designer hosts the GPU Technology Conference (GTC) to showcase advances in AI and accelerated computing.
Nebius is expected to deploy Nvidia-powered computing infrastructure at the Oxagon campus to support its AI cloud business and international customer base.
The project combines Humain’s AI capabilities with DataVolt’s experience in developing, financing and operating digital infrastructure. It is intended to support large-scale AI and cloud workloads for Saudi and international customers.
Oxagon is seeking to position itself as a location for energy-intensive digital infrastructure, supported by pre-zoned industrial land, power resources and subsea cable connectivity to Europe and Africa. The development is also expected to incorporate renewable energy and advanced cooling systems.
The Oxagon campus builds on an agreement signed in February 2025 by Neom and DataVolt to develop data centre infrastructure at the site. That deal involved an investment of about $5bn and envisaged a 1.5GW development.
In September 2025, DataVolt signed a memorandum of understanding with South Korea’s LG Electronics covering cooling systems for the Oxagon data centre project.
DataVolt was founded in 2023 and is a wholly owned subsidiary of Saudi infrastructure developer Vision Invest. Humain was launched in May 2025 to develop capabilities across the AI value chain, including data centres, high-performance computing infrastructure, cloud platforms and AI models.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20837696/main.jpg -
Riyadh awards $301m Sheikh Jaber Road contract
22 October 2026
Register for MEED’s 14-day trial access
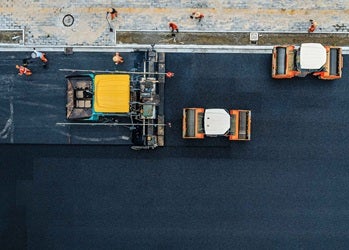
The Royal Commission for Riyadh City (RCRC) has awarded an estimated SR1.13bn ($301m) contract to local firm Alomaier Trading & Contracting Company to upgrade a section of Sheikh Jaber Al-Ahmad Al-Sabah Road in the capital.
The project covers the construction of an urban road about 3 kilometres (km) long, with a right-of-way width of about 120 metres.
The scope of work includes the delivery of three interchanges featuring post-tensioned, voided-slab concrete bridges; a cut-and-cover tunnel; and three box culverts designated IC02, IC03 and IC04.
The contract also encompasses pumping and lifting stations, stormwater drainage and irrigation networks, earthworks, asphalt paving, roadway lighting, power distribution systems, mechanically stabilised earth retaining walls and landscaping works.
The award forms part of RCRC’s wider programme to upgrade Riyadh’s arterial road network, decongest critical bottlenecks and expand transportation capacity in the city ahead of Expo 2030 and the 2034 Fifa World Cup.
The contract award follows RCRC’s appointment in May of a joint venture of Riyadh-based Al-Rashid Trading & Contracting Company and Turkiye’s IC Ictas for an estimated SR5bn ($1.3bn) contract to construct another section of Sheikh Jaber Al-Sabah Road.
That project covers 12km from Khurais Road to Al-Thumama Road and is a component of Riyadh’s Second Eastern Ring Road scheme.
Alomaier Trading & Contracting Company has secured several contracts in recent months.
In August, Saudi Arabian Railways awarded the contractor an estimated SR4bn-plus ($1.1bn) contract to add a second track to the first section of the existing phosphate railway in the kingdom’s Eastern Province.
The railway package covers about 100km between AZ1/Nariyah Yard and Ras Al-Khair. Works include track doubling, alignment modifications, utility bridges, culvert widening, hydrological structures, conversion of the AZ1 siding into a mainline track, and enabling works for signalling and telecommunications systems.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20833960/main.jpg -
Dewa International signs energy and infrastructure MoUs
22 October 2026
Dubai Electricity & Water Authority’s (Dewa) new development arm, Dewa International, has signed four memorandums of understanding (MoUs) with international partners to explore investment and project development opportunities in the energy, water and infrastructure sectors.
The agreements, signed during Dubai’s Water, Energy, Technology and Environment Exhibition (Wetex 2026), follow the launch of the wholly owned subsidiary in June, as reported by MEED.
At the time, the utility said the arm would be used to export Dubai’s energy and water infrastructure model, with a focus on developing conventional and clean energy projects for global markets.
At Wetex, Dewa International signed an MoU with France’s EDF Power Solutions to explore potential joint participation in solar, wind, battery energy storage and pumped-storage hydropower projects.
A separate agreement with China Energy International Group explores the company’s potential role as an engineering, procurement and construction (EPC) partner for major energy, water and infrastructure projects. The MoU also covers cooperation in project development and EPC services.
A further agreement with UK-based Capital Dynamics focuses on potential joint investments in operational clean energy assets in Europe. The parties will also explore establishing an investment vehicle for future clean energy infrastructure investments.
Dewa International also signed a fourth agreement with Mumbai-Headquartered Tata Consultancy Services, exploring the company’s potential role as a technical consultancy partner. The scope covers technology strategy, information technology and operational technology integration, and asset performance management solutions.
Dewa currently has almost $7bn-worth of power and water projects under execution across the UAE, according to regional projects tracker MEED Projects.
Its flagship Mohammed Bin Rashid Al-Maktoum Solar Park is the largest single-site solar park in the world. The utility is currently advancing the project’s seventh phase, with Abu Dhabi Future Energy Company (Masdar) recently submitting the lowest bid for the project, as exclusively reported by MEED.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20828111/main0128.jpg -
EGA’s Al-Taweelah restoration reaches 50% completion
22 October 2026
Register for MEED’s 14-day trial access
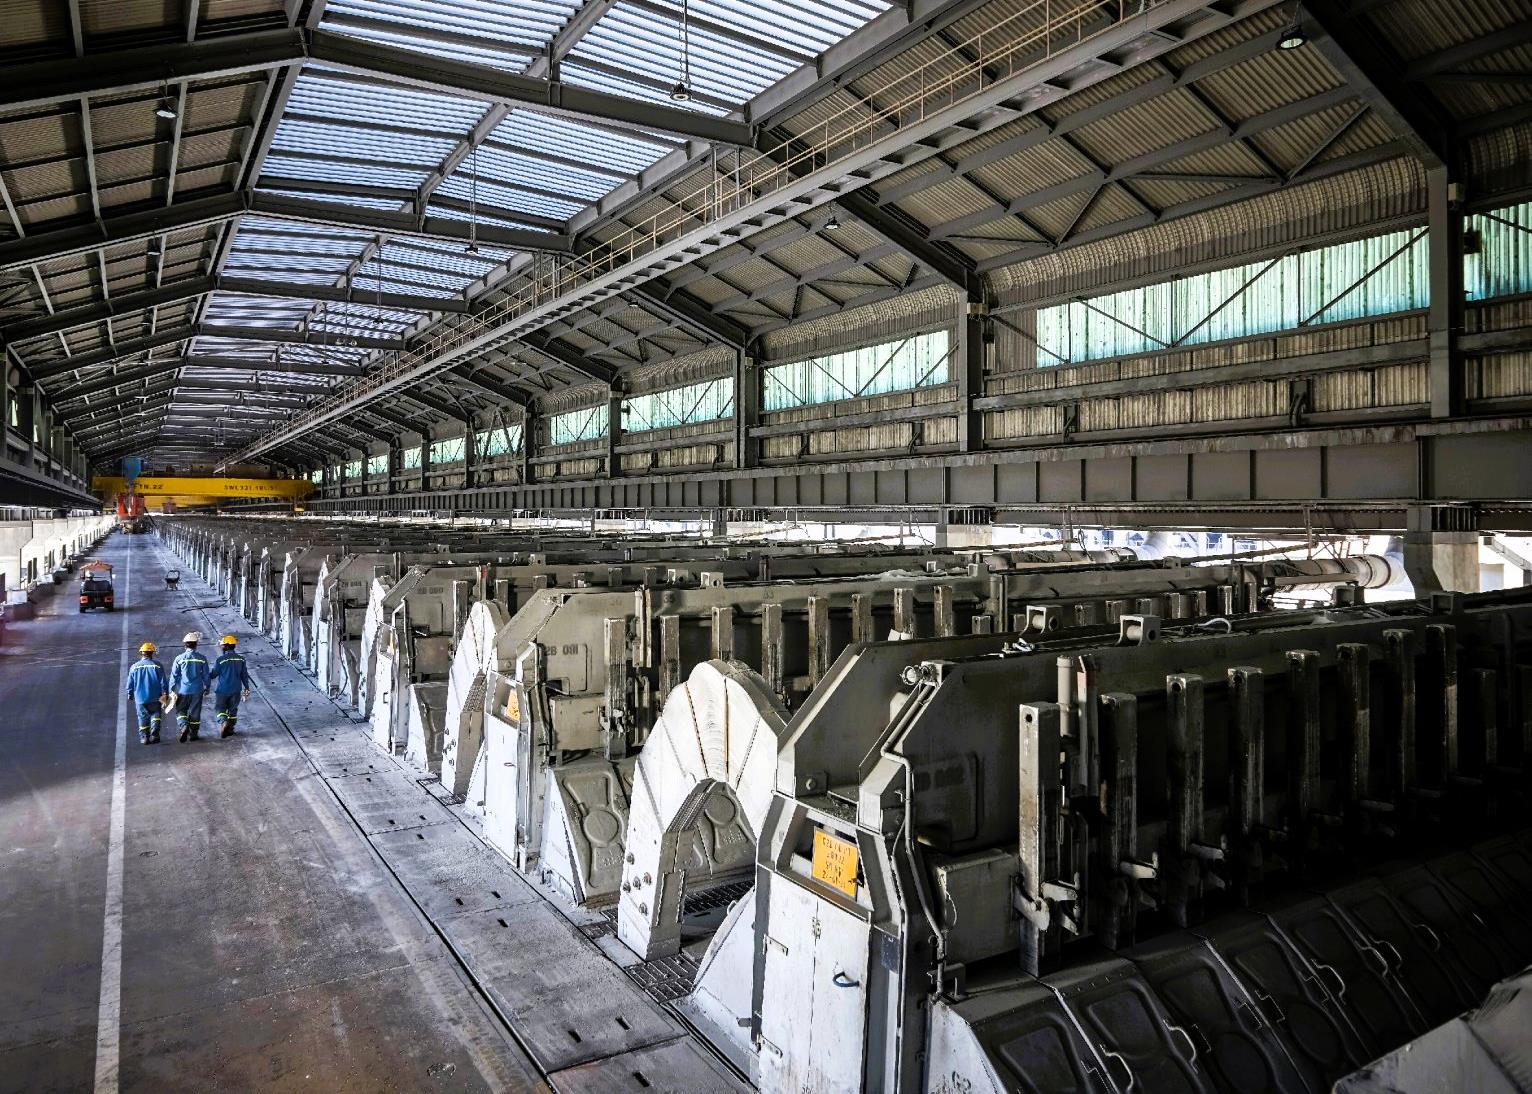
The UAE’s Emirates Global Aluminium (EGA) has announced that half of the reduction cells at its Al-Taweelah smelter in Abu Dhabi, which sustained damage from Iranian attacks in late March, have been restarted.
On 28 March, drone and missile attacks by Iran on Khalifa Economic Zone Abu Dhabi (Kezad), where the smelter is located, led to an emergency shutdown of the facility and injured two EGA employees, who were later discharged from hospital.
To restore hot metal production, EGA said it must progressively repair and restart each reduction cell. So far, 631 of the 1,262 reduction cells at Al-Taweelah have been restarted.
EGA – which is jointly owned by the governments of Abu Dhabi and Dubai – is working on all three potlines at Al-Taweelah in parallel, to accelerate the rate of reduction cell start-ups. Potline 1 was energised on 26 May, followed by Potline 3 on 13 July and Potline 2 on 3 August.
After being restarted, a reduction cell typically takes a week to stabilise and reach full production. Some hot metal is used to restart subsequent reduction cells, with the balance being delivered to EGA’s Al-Taweelah casthouse, to be cast into finished premium aluminium products.
Following the emergency shutdown, molten aluminium froze in every reduction cell at Al-Taweelah, leaving solid metal pads weighing up to 45 tonnes, which needed to be removed. Almost 80% of the reduction cells can then be restarted. The remaining reduction cells require repairs, potlining demolition and relining, depending on how long the reduction cells had been operating before the incident.
Periodically cutting out, repairing and relining reduction cells at the end of their operating life is routine in aluminium smelting. Compared to the normal rolling maintenance programme, EGA has more than tripled its capacity in order to safely repair and restart reduction cells at Al-Taweelah, by optimising workflows, adding equipment, strengthening employee capability and deploying industrial process innovations.
ALSO READ: EGA to receive first Guinea bauxite post-settlement
About 1,000 employees are working on the restoration of hot metal production at the Al-Taweelah smelter, EGA said in a statement on 26 August.
During the restoration, EGA has accelerated the deployment of a technology pilot at Al-Taweelah that would otherwise have required operating reduction cells to be shut down. The pilot E40 upgrades to 13 DX technology reduction cells will be used to prove the performance of the technology before industrialisation across all 808 DX technology cells at Al-Taweelah.
If applied to all DX reduction cells, EGA’s E40 technology has the potential to increase hot metal production by 67,000 tonnes a year (t/y).
EGA’s Al-Taweelah alumina refinery is located next to the Al-Taweelah smelter.
Alumina is the feedstock for aluminium smelters. It is transferred to storage and then into the smelter by a system of conveyor belts.
The Al-Taweelah alumina refinery continues to produce alumina at approximately 50% capacity, EGA said. While the alumina refinery is technically ready to ramp-up further, timing will be based on supply chain dynamics and the optimisation of EGA’s alumina sourcing strategy.
The company announced on 10 July that it had restarted alumina production at its main refinery in Al-Taweelah, adding at the time that it expected to have the technical capability to ramp up to full alumina production by the end of this year.
The Al-Taweelah alumina refinery began production in 2019 and has a nameplate capacity of 2 million t/y.
EGA’s Al-Taweelah smelter consists of 1,262 reduction cells and produced 1.6 million tonnes of cast metal in 2025.
The Al-Taweelah alumina refinery produced 2.4 million t/y of alumina in 2025, and met 46% of EGA’s alumina needs.
EGA also said in July that its site in the Jebel Ali area of Dubai is continuing aluminium production at full capacity. Average daily inbound deliveries of all major raw materials exceed EGA’s requirements to maintain metal production at Jebel Ali and meet the demands of restoration at Al-Taweelah, with raw material stocks in the UAE increasing.
Separately, the ramp-up of production at EGA’s new Al-Taweelah recycling plant remains on track, with full production expected by late in the fourth quarter of this year.
EGA’s recycling plants in the US and Germany, meanwhile, have continued production throughout 2026.
ALSO READ: EGA to receive first Guinea bauxite post-settlement
https://image.digitalinsightresearch.in/uploads/NewsArticle/20827987/main1007.jpg