Working towards a common energy-transition goal
28 November 2022
Published in partnership with

In the end, it went right to the wire. Just as it looked like the UN’s 27th Conference of the Parties (Cop27) would conclude without an accord, the weary delegates announced that they had reached a landmark agreement on setting up a fund to help compensate poorer nations for the economic and social destruction caused by climate change.
The statement, two days after the Sharm el-Sheikh summit’s original 18 November end date, was a culmination of some 30 years of negotiations between developed economies and developing nations. The latter had long argued that the damage they have experienced from global warming should be paid for by richer countries responsible for the crisis in the first place.
Although far from perfect, the global ‘loss and damage’ fund was hailed as an important and symbolic step towards hitting the agreed target of limiting global temperature increases to 1.5C above pre-industrial levels by 2030. It also marked the continuing engagement and collaboration by governments across the globe.
“We rose to the occasion,” said Egypt’s Minister of Foreign Affairs and president of Cop27 Sameh Shoukry.
“We worked around the clock, day and night, but united in working for one gain, one higher purpose, one common goal. In the end, we delivered. We listened to the calls of anguish and despair.”
Private sector involvement
While Cop27 has been and will continue to be a policy-setting mechanism negotiated at the highest level, companies played a critical role during the conference.
Firms representing a broad range of sectors, including Vodafone, Microsoft, Boston Consulting Group and Bloomberg, partnered with the event, and many more participated in the main conference and exhibition areas.
Ultimately, governments understand that the private sector will lead the drive towards net zero. Without corporates worldwide investing in clean energy projects and technology, there is little hope that targets will be reached.
 Five consistency points
A key supporter of Cop27 was Siemens Energy. Sharing its expertise through panels covering subjects as varied as the Mediterranean’s North-South Energy Partnership, improving power access in Africa by unlocking its green hydrogen potential, and overcoming the challenges of decarbonisation, the energy technology company played a pivotal role in discussions and thought leadership.
It also participated in the world leader’s summit at a roundtable discussing green hydrogen, reinforcing its positioning of energy transition at the heart of its strategy.
Before the Sharm el-Sheikh conference, Siemens Energy president and CEO Christian Bruch outlined five points of consistency that his company considers to be unifying elements in the decarbonisation drive.
The first is the acceleration of renewables. Replacing conventional power generation systems with solar, wind, hydro and other forms of renewable energy is essential to reduce greenhouse emissions.
Despite a considerable increase in the overall share of renewables in the past three years on the back of ever-lowering costs and more efficient technology, more must still be done.
For example, the US needs to triple its share of renewable energy as a proportion of the energy mix by 2050 for the energy transition to succeed. The Asia-Pacific region, meanwhile, will have to increase this figure fourfold.
Regional targets
In the Middle East, every country has now set ambitious targets to increase renewable energy. The likes of Saudi Arabia, Morocco and the UAE are aiming for renewables to account for up to 50 per cent of total production by 2030. To reach these objectives, almost all new power generation projects come in the form of renewables.
However, the impact of greener electricity production could be somewhat offset by continuing demand growth caused by an increasing global population and economic growth.
In this context, the second point is the requirement for improved energy conservation measures, such as policies to incentivise the electrification of industry and transport.
Regionally, the industrial electrification of energy-intensive industries is an optimal opportunity to reduce harmful emissions by harnessing electric boilers and/or electricity-based fuels. Future large-scale blue and green hydrogen production will also have a role to play in industrial processes.
Siemens Energy’s third point of consistency is improving electrical efficiency. The increase in renewable energy capacity and the growth in power capacity, in general, require significant investment in transmission and distribution networks.
This is particularly important in areas such as sub-Saharan Africa, where almost 25 per cent of the population has little to no access to electricity.
The fourth point covers the requirement to use existing conventional power infrastructure to help bridge the gap between the fossil-fuelled economies of today and the net zero of tomorrow.
Progress cannot be made in one step alone and requires a gradual transition. In the meantime, existing thermal plants can employ measures such as combined-cycle technology and carbon capture to make them as efficient and environmentally friendly as possible.
The energy transition is the biggest investment programme since the dawn of industrialisation. If governments, business and society work together, energy transition is a massive opportunity
Christian Bruch, Siemens Energy president and CEO
Mineral production
Finally, to achieve all of this, it is necessary to improve supply chains and increase the production of necessary minerals and rare earth metals required in net-zero technologies, such as lithium, nickel, cobalt and chromium.
Bruch gives the example of a typical electric car, which requires six times more mineral inputs than one powered by an internal combustion engine. He also cites onshore wind plants, which need nine times more than a gas-fired power plant.
If mineral production is not increased and geographically diversified, there is a risk of future supply bottlenecks.
In the Middle East, a good illustration of this is the potential future supply gap for electrolyser systems, and the anodes and cathodes typically made from metals such as zinc, nickel and lithium.
MEED estimates that about 75GW of electrolyser production capacity will be required by 2030 to meet the demand for the raft of planned green hydrogen plants in the region alone, compared with a total global output capacity of just 8GW today.
 Industrial decarbonisation alliance
All five consistency points make salient arguments. However, they can only be achieved with close cooperation between the private and public sectors. While the former can spearhead and implement the decarbonisation drive, the latter can provide the regulations and incentives to encourage these initiatives.
The newly formed Alliance for Industry Decarbonization initiated by Siemens Energy and coordinated and facilitated by the Abu Dhabi-based International Renewable Energy Agency (IRENA) is an example of greater collaboration between the public and private sectors.
The 28-member alliance – which encompasses a range of global energy, renewable, consulting and manufacturing companies – met for the first time during Cop27 to outline its joint vision and implementation plan. Its strategy focuses on six pillars and enablers that tie into the points of consistency: renewables, green hydrogen, bioenergy with carbon capture, utilisation and storage (CCUS), heat process optimisation, human capital and finance.
Only through this kind of stakeholder dialogue can the immense and existential challenges posed by global warming be overcome. Governments or companies acting in isolation will only achieve so much on their own. The points of consistency must be considered as a whole and in unison if the world’s climate objectives are to succeed.
As Bruch says: “The energy transition is the biggest investment programme since the dawn of industrialisation. If governments, business and society work together, energy transition is a massive opportunity. There is no excuse for waiting any longer.”
Related reads:
- New alliance forged to accelerate net-zero ambitions
- The journey towards net zero
- Solving Europe’s energy challenge
- Africa’s energy trilemma
- Region primed for global green hydrogen leadership

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Neom’s industrial pivot gathers pace
1 October 2026
-
 Contractor wins Dammam airport water infrastructure deal
1 October 2026
-
 Kuwait tenders LNG project
1 October 2026
-
 Riyadh approaches contractors for 2km tower
1 October 2026
-
 Aldar and Arada to pursue Abu Dhabi projects
1 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Neom’s industrial pivot gathers pace
1 October 2026
 Commentary
Colin Foreman
EditorReprioritisation has been the buzzword in Saudi Arabia over the past two years and nowhere has that been more evident than at Neom.
 The slowdown of development at The Line and the postponement of the 2029 Asian Winter Games at Trojena have dominated international headlines. As these projects scale back, Oxagon’s industrial and logistics base has become the $500bn gigaproject’s flagship development. There are tangible results: in August, the $8.5bn Neom Green Hydrogen project was commissioned, marking Neom’s most significant completion to date.
Construction activity elsewhere at Oxagon supports this trend. The AI data-centre campus being developed by Humain and DataVolt has broken ground on its first 100MW phase, backed by $5bn of investment and targeted for service in 2028. Neom has issued an expression of interest for a rail line linking the Port of Neom to Saudi Arabia Railways’ North-South network, tenders are out for an industrial wastewater plant and the upgrade of Highway 55, and the port itself is advancing towards a 2030 capacity target of 1.5 million TEUs.
The regional conflict that began in February has strengthened the business case by giving Oxagon’s Red Sea port added strategic weight as a second maritime gateway outside the Strait of Hormuz, at a time when Riyadh has committed to directing about 80% of the Public Investment Fund’s portfolio into domestic investment.
These developments reflect a kingdom recalibrating rather than retreating
Elsewhere, Saudi Arabia’s wider projects market is holding steady despite conflict-related disruption, with contract awards reaching $68bn so far this year. The regional power market is also diversifying, with Aljomaih, EDF and Kepco all more than tripling net capacity in recent years as Acwa retains its lead.
These developments reflect a kingdom recalibrating rather than retreating, with priority given to projects capable of delivering commercial returns.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20178338/main.gif -
Contractor wins Dammam airport water infrastructure deal
1 October 2026
Saudi Arabia-based Alkhorayef Water & Power Technologies has won an SR80m ($21.3m) contract to rehabilitate water and wastewater infrastructure at King Fahd International airport in Dammam in the kingdom’s Eastern Province.
The contract was awarded by Dammam Airports Company (DACO), and work is scheduled to be completed within 18 months, the firm said in a disclosure to the Saudi Exchange (Tadawul) on 29 September.
The scope covers the design, construction, supply, installation, replacement, rehabilitation and integration of water and wastewater infrastructure.
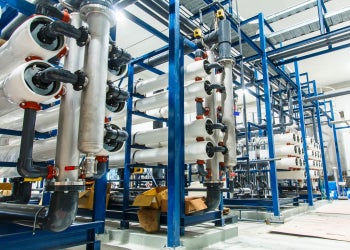
It includes pumps, storage tanks and reservoirs, reverse osmosis facilities, piping and tie-ins, as well as electrical and instrumentation works.
The award comes as DACO advances a wider programme of investment at King Fahd International airport.
DACO signed more than SR1.2bn ($320m) in agreements in June covering airport infrastructure, including a new power station, a medium-voltage distribution network and upgrades to the existing electrical grid.
In September, it also appointed WSP Middle East, the regional arm of Canadian engineering firm WSP, to develop the airport’s expansion under its masterplan.
The expansion is intended to increase annual passenger capacity to more than 19.3 million by 2030, with a longer-term target of 32 million passengers.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20169118/main.jpg -
Kuwait tenders LNG project
1 October 2026

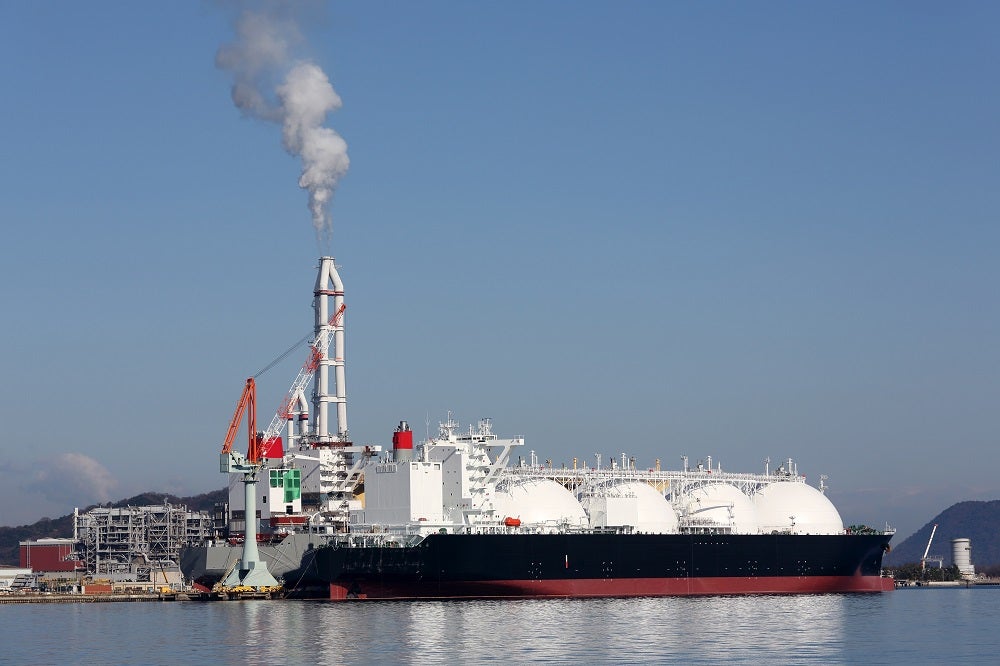
State-owned Kuwait Integrated Petroleum Industries Company (Kipic) has tendered a project to develop a reliquefaction unit at the Al-Zour liquefied natural gas (LNG) import terminal.
The project focuses on developing a boil-off gas (BOG) unit at the terminal, with bids due on 22 December.
A meeting for contractors to discuss the project is scheduled for 18 October.
The project scope includes engineering, procurement and construction works, along with pre-commissioning, commissioning and performance testing services.
The list of prequalified companies is:
- Fluor (US)
- GS Engineering & Construction (South Korea)
- Tecnicas Reunidas (Spain)
- Larsen & Toubro (India)
- Hyundai Engineering (South Korea)
- CTCI Corporation (Taiwan)
- Daewoo Engineering & Construction (South Korea)
- Hyundai Engineering & Construction (South Korea)
- Saipem (Italy)
- Samsung Engineering (South Korea)
- Sinopec Engineering (China)
- JGC Holdings (Japan)
- KBR (US)
- China National Petroleum Corporation (China)
- Technip (France)
A BOG unit at an LNG facility captures, compresses and processes natural gas vapours that evaporate from cryogenic storage tanks, enabling the gas to be recycled back into the system rather than flared.
In April, MEED revealed that contractors expected the project to be worth about $200m.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20168625/main2005.jpg -
Riyadh approaches contractors for 2km tower
1 October 2026
Register for MEED’s 14-day trial access
Saudi Arabia’s Public Investment Fund (PIF) has reached out to contractors as part of a market-sounding exercise for the construction of the proposed 2-kilometre megatall tower project.
MEED understands that a PIF subsidiary, the Tower District Real Estate Development Company, is undertaking the process.
It is understood that several experienced international contractors, as well as some prominent local contractors, have been approached.
The latest development follows PIF receiving offers in June last year from firms seeking a contract to provide project management consultancy (PMC) services for a new central business district (CBD) on the outskirts of Riyadh, which includes the proposed 2km tower.
The PMC role covers both the tower and the surrounding district.
Firms understood to have been invited to bid include US-based Aecom, Jacobs, Parsons and Turner, as well as the UK’s Mace.
UK-based Foster & Partners is working as the architect for the tower after winning a design competition launched in late 2022.
Record breaker
The proposed tower would be more than double the height of the world’s tallest building, Dubai’s Burj Khalifa, which stands 828 metres tall. It is expected to be at least several hundred metres taller than the 1,000-metre-plus tower under construction in Jeddah.
Contractors that have priced megatall towers in the region say a 2km-tall structure could cost about $5bn to construct, depending on the final design.
The 2km tower and the surrounding CBD – known as Project Rise – sit within a larger masterplanned development to the north of Riyadh called the North Pole.
MEED’s October 2026 report on Saudi Arabia includes:
> COMMENT: Saudi projects hold steady
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflict
> DATABANK: Saudi data indicates project spending shiftTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20156496/main.jpg -
Aldar and Arada to pursue Abu Dhabi projects
1 October 2026
UAE-based developers Aldar Properties and Arada have signed a partnership agreement targeting about AED15bn ($4bn) in development opportunities on Yas Island and in Abu Dhabi’s Seih Sdeirah.
The deal includes a masterplan joint venture to develop a mixed-use community at Seih Sdeirah, on the Abu Dhabi-Dubai border, and Arada’s purchase of three residential plots on Yas Island from Aldar.
The Seih Sdeirah project will cover up to 1.5 million square metres (sq m) and will include villas, townhouses, and retail and leisure facilities.
Arada will lead development and construction management, while both firms will jointly brand and market the community.
On Yas Island, Arada has bought two canal-facing plots totalling more than 27,500 sq m, with nearly 130,000 sq m of gross floor area, as well as a third residential plot.
Aldar said the companies will explore further collaboration across sectors and locations in the UAE.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20156829/main.jpg